 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
ETF share classes represent a structural innovation that combines the benefits of mutual funds and exchange-traded funds (ETFs) within a single pooled portfolio. This evolution expands investor choice, offering both ETF and mutual fund shares under a unified investment strategy.
ETF share classes give investors access to established mutual fund strategies while leveraging the structural efficiencies of ETFs, such as tax efficiency and lower transaction costs. By utilizing the in-kind creation and redemption mechanism, ETF share classes can minimize realized capital gains, benefiting all shareholders within the shared portfolio. While gross performance remains consistent across share classes, net performance may vary due to differing fee structures.
What is an ETF Share Class?
An ETF share class operates as an additional share class of a mutual fund and shares the same pooled portfolio and investment strategy. Unlike standalone ETFs, which maintain separate asset pools, ETF share classes leverage ETF mechanics — such as in-kind transactions and intraday trading — while mutual fund classes continue to transact at end-of-day net asset value (NAV). This structure lets investors choose their preferred wrapper without compromising on strategy.
Tax-Efficiency Benefits
ETF share classes enhance tax efficiency through in-kind transactions, where securities are exchanged instead of cash. This mechanism reduces taxable events, insulating all shareholders from capital gains. While mutual funds can technically transact in-kind, operational differences often limit their use. By introducing an ETF share class, mutual funds gain access to the scalable, tax-efficient in-kind creation/redemption mechanism of ETFs, benefiting all share classes.
For example, a mutual fund with an ETF share class can use in-kind redemptions to remove low-basis securities, maintain a higher average cost basis, and reduce capital gains distributions. This contrasts with traditional mutual funds, which typically rely on cash redemptions that may trigger taxable events.
Operational Considerations
Introducing ETF share classes requires significant operational infrastructure, particularly for inter-class exchanges. While it’s expected that investors will be able to move between mutual fund and ETF share classes without triggering taxable events, this capability depends on platform- and product-specific developments.
Suitability Across Strategies
Not all investment strategies are suitable for ETF share classes. Domestic equity strategies, which are fully in-kind eligible, are the strongest candidates. Developed international equity and certain fixed-income strategies may also benefit, depending on their ability to transact in-kind.
However, strategies with non-in-kind eligible securities, such as emerging market equities, may see limited advantages. Commercial viability, investor demand, and fund capacity also influence suitability.
Advisor Guidance
Financial advisors will play a crucial role in helping clients navigate the complexities of ETF share classes. By understanding the shared portfolio model, tax efficiency conditions, and operational limitations, advisors can set realistic expectations and guide clients toward informed decisions.
A Balanced Perspective
While ETF share classes offer multiple benefits, they are not a universal solution. Their effectiveness depends on strategy characteristics, market conditions, and investor preferences. ETF share classes should be viewed as one of several tools for portfolio construction and management, complementing traditional mutual funds and standalone ETFs.
Allspring’s Approach
Allspring Global Investments received SEC relief to use the ETF share class structure in January 2026. The firm is actively working with its board of trustees to identify suitable candidates for ETF share classes. Allspring believes this structure can deliver significant benefits, including access to established strategies, enhanced tax efficiency, and operational cost savings. Investors in mutual fund share classes are expected to have the option to move tax-free to corresponding ETF share classes, gaining intraday trading flexibility and other advantages.
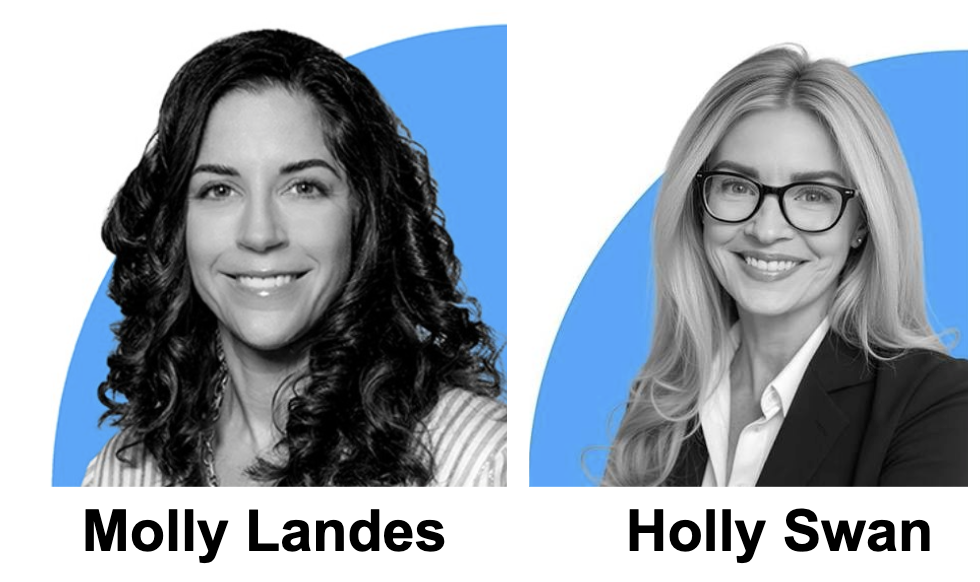
Molly Landes is Head of ETF Capital Markets and Holly Swan is Head of Wealth Solutions Global Client Strategy at Allspring Global Investments.
The ETF creation/redemption mechanism is a primary market process where authorized participants (APs) exchange underlying securities directly with ETF issuers for large blocks of shares ("creation units") to balance market supply and demand. Redemptions work in reverse order, with APs exchanging large blocks of ETF shares (“redemption units”) in exchange for underlying securities. This helps to keep the ETF's share price aligned with its net asset value (NAV) and enhances liquidity.
Authorized Participants (APs) are specialized financial institutions, typically large banks, or broker-dealers—that hold an exclusive agreement with an ETF issuer to create and redeem ETF shares in the primary market. They help to ensure market liquidity and keep the ETF’s price aligned with its NAV by trading underlying securities for "creation units".
A multi-class investment structure allows a single fund or company to issue multiple types of shares or interests, often with different fee structures, voting rights, or dividend priorities to suit various investor needs.
SEC exemptive relief for ETF share classes is a U.S. Securities and Exchange Commission (SEC) order permitting mutual funds to add an exchange-traded fund (ETF) share class to their existing structure, allowing both to operate within one portfolio.
Tactical ETF model portfolios are actively managed investment strategies that shift asset allocation to capitalize on short-term market trends, sector rotations, or economic shifts.
Allspring ETFs are not available for distribution outside of the United States.
Carefully consider a fund’s investment objectives, risks, charges, and expenses before investing. For a current prospectus and, if available, a summary prospectus, containing this and other information, visit allspringglobal.com. Read it carefully before investing.
Investing involves risk, including the possible loss of principal. It is possible that an active trading market for ETF shares will not develop, which may hurt your ability to buy or sell shares, particularly in times of market stress. Shares may trade at a premium or discount to their net asset value (NAV) in the secondary market. These variations may be greater when markets are volatile or subject to unusual conditions. There can be no assurance that active trading markets for the shares will develop or be maintained by market makers or authorized participants. Shares of the ETFs are not redeemable with the ETF other than in creation unit aggregations. Instead, investors must buy or sell the ETF shares in the secondary market at market price (not NAV) through a broker-dealer. In doing so, the investor may incur brokerage commissions and may pay more than NAV when buying and may receive less than NAV when selling. Investing involves risk, including the possible loss of principal. Consult a fund’s prospectus for additional information on these and other risks.
This material is for general informational and educational purposes only and is NOT intended to provide investment advice or a recommendation of any kind—including a recommendation for any specific investment, strategy, or plan.
ALL-02232026-rz71mzbu
This content and the information within do not constitute an offer or solicitation in any jurisdiction where or to any person to whom it would be unauthorized or unlawful to do so. It should not be considered investment advice, an investment recommendation, or investment research in any jurisdiction.
INVESTMENT RISKS: All investments contain risk. Your capital may be at risk. The value, price, or income of investments or financial instruments can fall as well as rise and is not guaranteed. You may not get back the amount originally invested. Past performance is not a guarantee or reliable indicator of future results. Returns may increase or decrease as a result of currency fluctuations.
Allspring Global Investments™ (Allspring) is the trade name for the asset management firms of Allspring Global Investments Holdings, LLC, a holding company indirectly owned by certain private funds of GTCR LLC and Reverence Capital Partners, L.P. These firms include but are not limited to Allspring Global Investments Luxembourg, S.A.; Allspring Funds Management, LLC; Allspring Global Investments, LLC; Allspring Global Investments (UK) Ltd.; Allspring Global Investments (Singapore) Pte. Ltd.; Allspring Global Investments (Hong Kong) Ltd.; Allspring Global Investments (Japan) Ltd.; and Galliard Capital Management, LLC.Unless otherwise stated, Allspring is the source of all data (which is current or as of the date stated).
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
More ETF Topics >
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
