Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
Following last week’s decision by the Federal Reserve to raise the Fed Funds rate by 25 basis points, investors face a critical question.
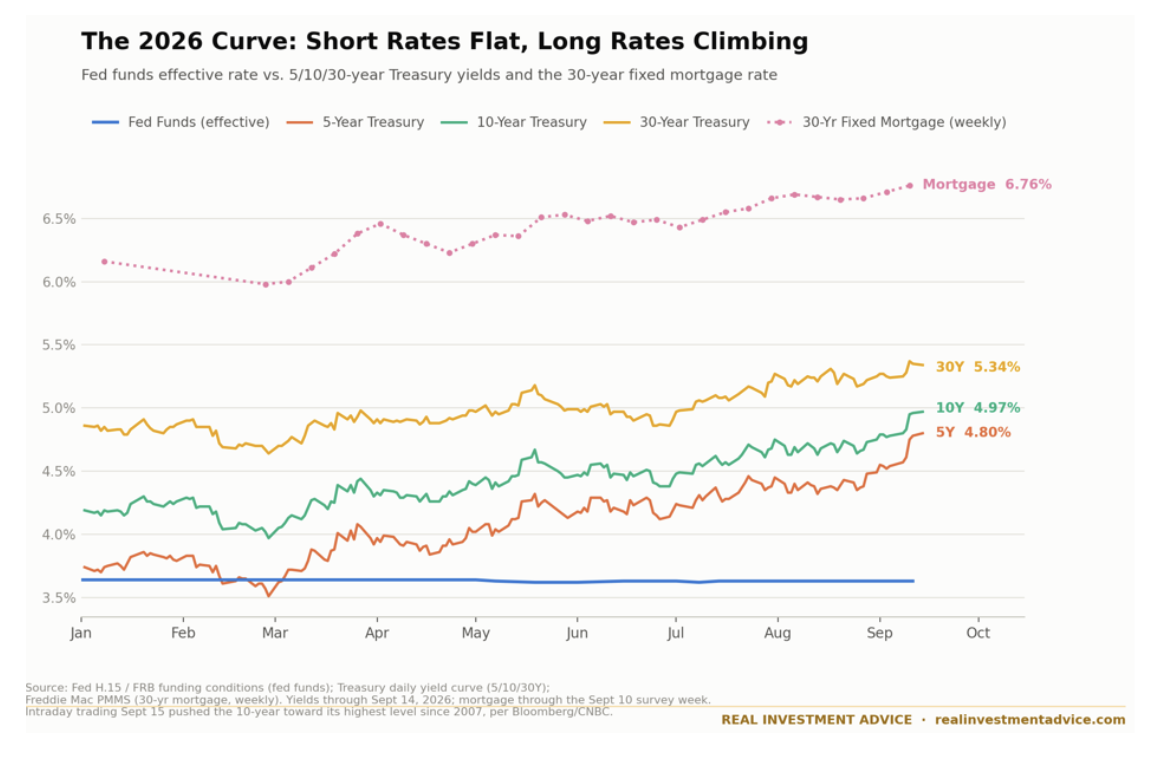
Prior to last week’s rate hike, policymakers had kept the Fed Funds rate steady even as inflation ran stubbornly above target. At the same time, longer-term bond yields had risen appreciably and, in the process, were tightening financial conditions. The 10-year Treasury recently surpassed 5%, and mortgage rates, corporate borrowing costs, and equity discount rates have all risen similarly.
The combination of prior Fed inaction followed by relatively significant market tightening raises a question: If long-maturity yields were already weighing on economic activity, did the bond market already do the Fed’s job?
The answer is complicated. The short and long ends of the yield curve impact the economy and inflation differently; accordingly, they are not necessarily substitutes for each other. Both affect GDP and inflation, but through separate channels and on different timelines.
What the Long End Impacts
The 5-year, 10-year, and 30-year yields influence personal consumption, corporate capex plans, and the pricing of assets valued off of a moderate or long stream of future cash flows.
Consider the following important sources of economic activity.
Housing
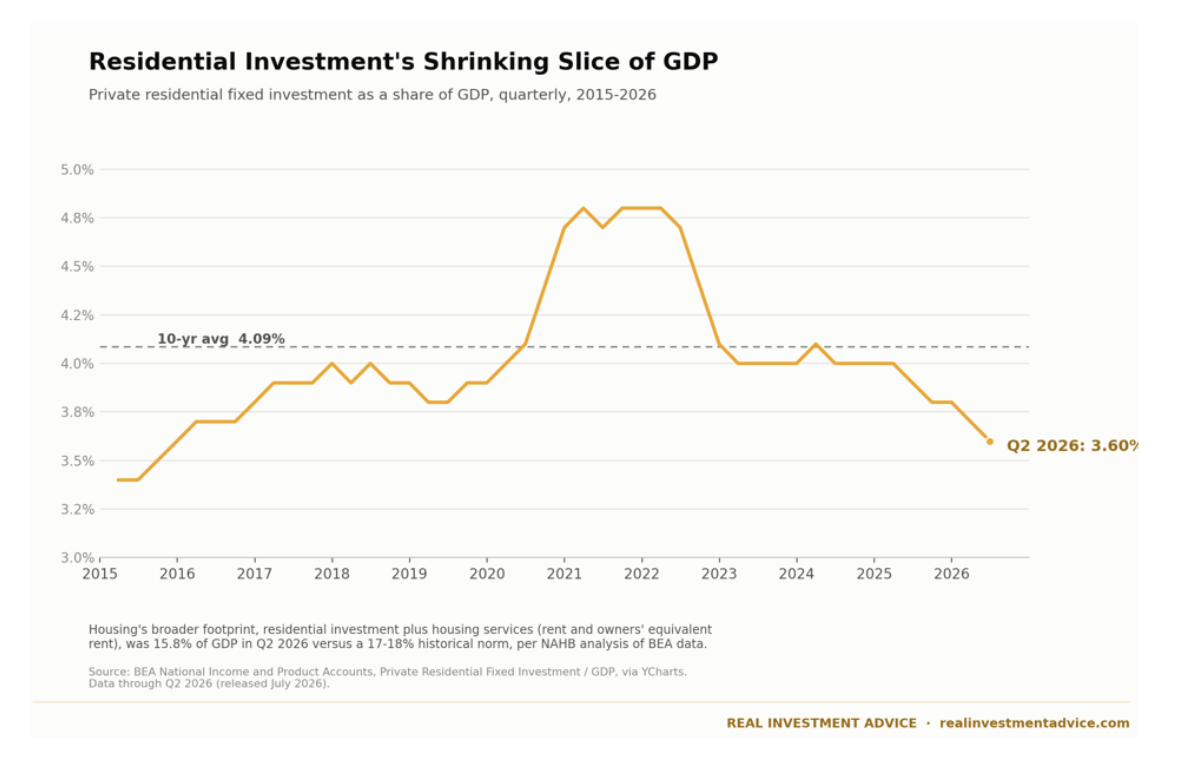
The 30-year mortgage rate closely tracks the 10-year Treasury plus a spread. With the 10-year yield hovering near 5.00% and mortgage rates near 7.00%, new and existing home sales, buyer demand, and housing turnover are depressed.
As a result, residential fixed investment as a percentage of GDP has fallen from nearly 5% in late 2021 to 3.6% today as mortgage rates have more than doubled.
Corporate Financing
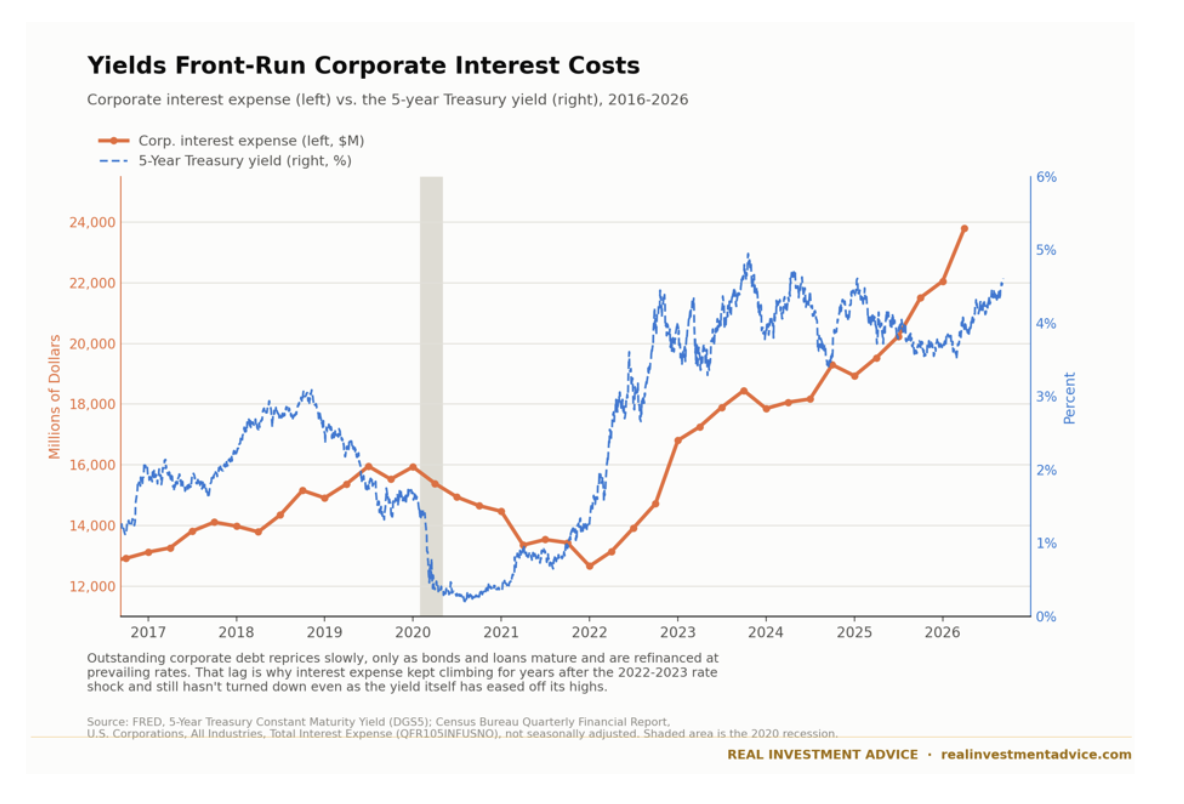
Corporate debt issuance is priced as a spread to Treasury yields. Thus, higher Treasury yields raise borrowing rates and increase corporate interest expenses. The impact lags, as shown in the graph below. Higher yields also raise project hurdle rates for capital expenditures.
Higher interest costs reduce profits that often result in executives cutting expenses, including payrolls. Higher project hurdle rates often cause firms to delay or reduce capex. In both cases, higher rates dampen economic activity over time.
It’s worth adding that higher rates today may have a greater impact than in the past because corporations borrowed extensively when rates were historically low in 2020 and 2021. A good portion of that cheap debt will mature over the next two years. Refinancing it at much higher rates will have a greater impact on interest expenses than in the past, even if Treasury yields stay at current levels or decline.
Auto Loans
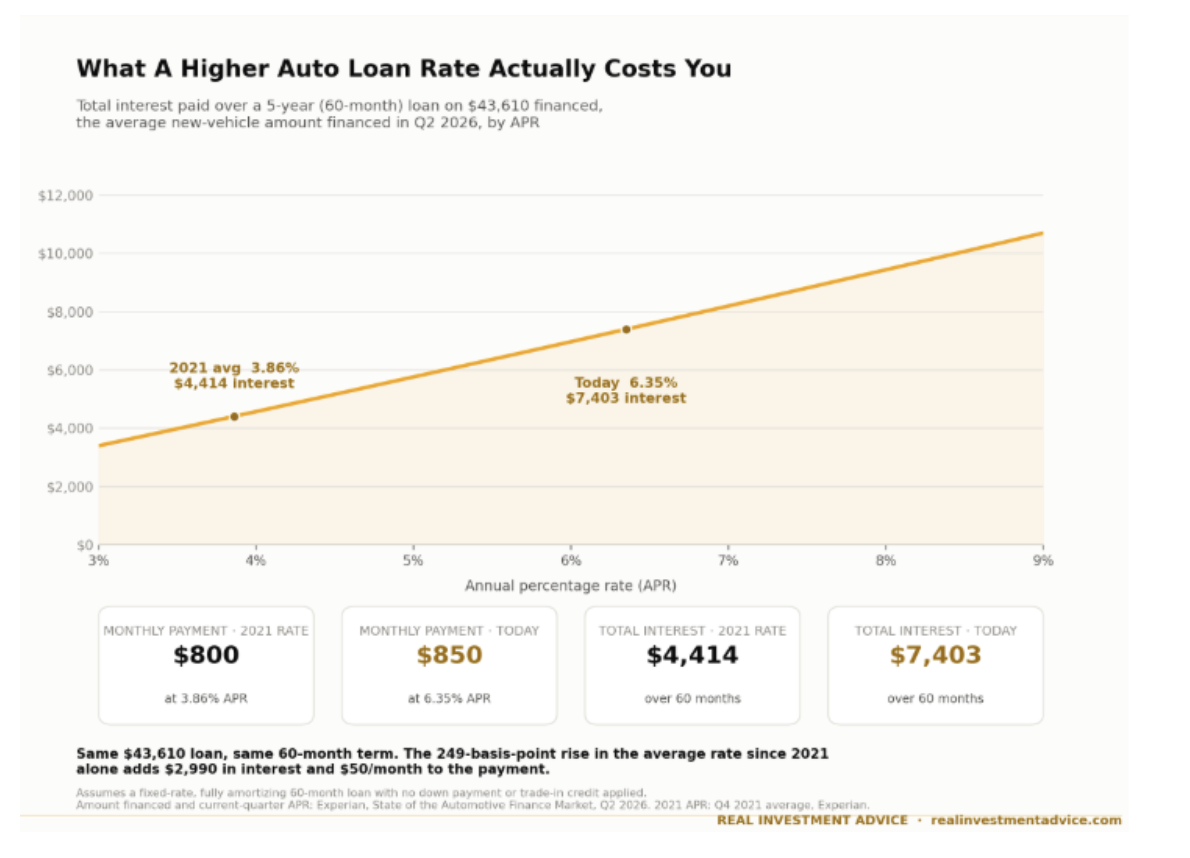
New and used auto loan rates price mainly off of the three- to seven-year part of the Treasury curve, which matches the loans’ duration. These short- to intermediate-term yields are up nearly 100 basis points since their late-February low, which pushed auto financing costs higher even before the Fed raised rates. Auto sales account for approximately 5% of GDP.
Equity Valuations
Equities are long-duration assets, with cash flow duration estimated at roughly 20 or more years on average. A higher long-term discount rate compresses fair-value calculations. Lower valuations, if they weigh on stock prices, can hurt consumer sentiment through the psychological wealth effect. It’s debatable whether higher yields have fully impacted equity markets yet, but regardless, the odds of them negatively affecting stocks rise as yields rise.
Federal Interest Expense
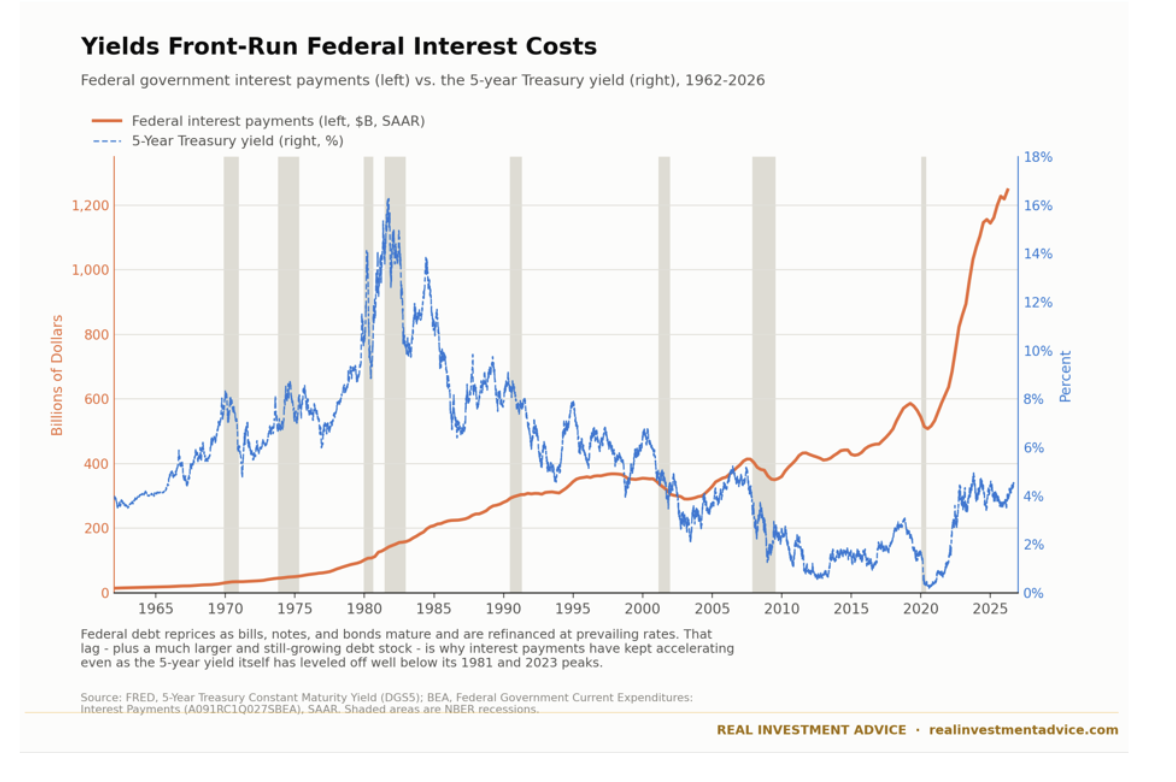
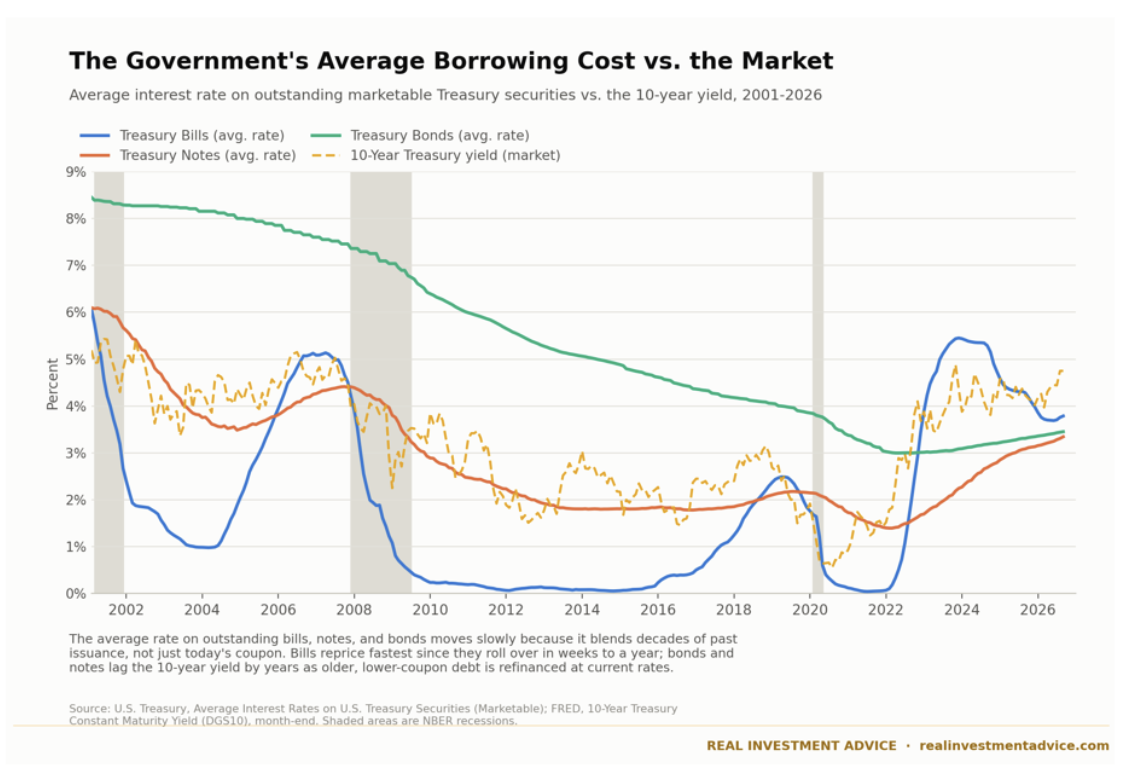
Higher yields raise the government's borrowing costs, but that increase in expense takes time, as most debt is set at lower rates and only resets when it matures. The first graph below shows the sharp increase in the government’s interest payments since 2020. The second graph shows the lag between changes in rates and changes in the government’s average interest rate. Note that longer-term bonds have a much longer lag than bills.
The important takeaway is that as the government demands more money to finance its debts, it crowds out financing for consumers and corporations, ultimately raising their borrowing costs.
Higher Long Rates Are a Headwind
While those economic sectors and assets are negatively impacted by higher long-term rates, none is a direct inflation channel. Rising long-term yields cool the economy by discouraging borrowing and spending, and lower demand or weak sentiment eventually feeds through to prices, but the diffusion is slow.
What the Short End Impacts
The Fed Funds rate and short-term Treasury bills govern a different set of financial channels that tend to influence inflation more directly and quickly than longer-term yields.
Consumer Revolving Credit
Credit card rates, home equity loans, and floating-rate auto and small business loans are typically priced off of the Prime Rate, which is the Fed Funds rate plus a fixed spread. A change in the Fed Funds rate — such as last week’s 25 basis point move — hits household and business cash flows within a billing cycle and directly alters consumption decisions with immediate effects on both prices and economic activity.
Bank Net Interest Margin & Credit Supply
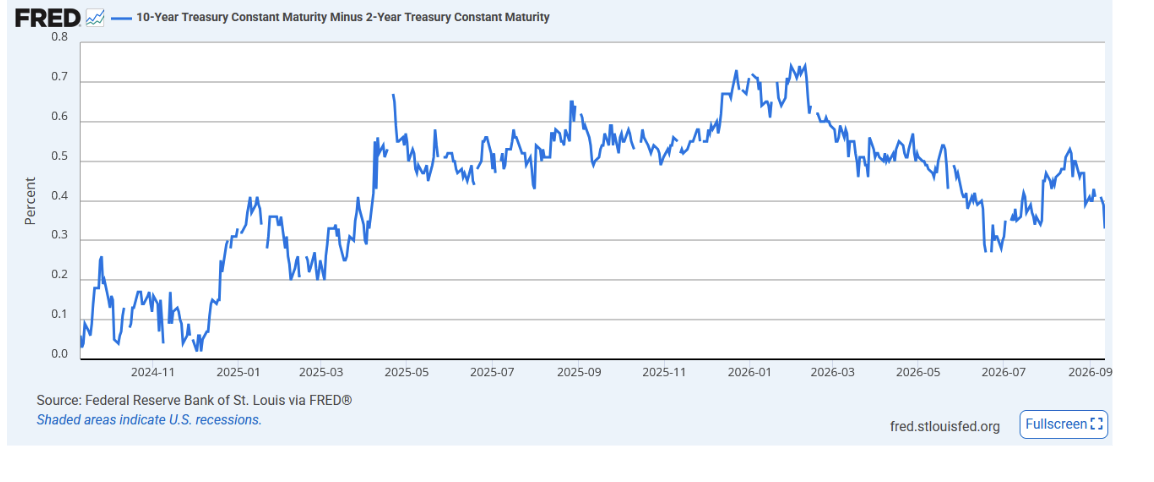
Banks tend to fund their long-term assets, like loans and mortgages, with short-term liabilities. Short-term rates, along with the shape of the yield curve, determine lending profitability, i.e., a bank's net interest margin. Banks are more willing to extend credit when lending margins are high. Thus, an increase in the Fed Funds rate, which often flattens the yield curve and shrinks banking profitability by default, can materially reduce lending activity.
As I show below, the yield curve has flattened further (tightening net interest margins) as the market digests last week’s monetary tightening.
Savings & Cash Yields
Money market and short Treasury Bill yields determine what households and businesses earn on cash. Those rates shape the propensity to spend versus hold cash. This can be a fast-moving channel that works opposite the slow equity wealth effect. Higher yields incentivize consumers to save rather than spend, thus slowing economic activity.
Inflation Expectations & Fed Credibility
This may be the most important factor in answering whether the market has done the Fed's job. The Fed Funds rate is the primary tool the FOMC uses to manage monetary policy. Consumers, businesses, and investors watch it closely as a credibility signal of whether the central bank is committed to its 2% inflation target.
A tightening bond market, as we currently have, can restrain growth but says little about the Fed's resolve. Only the Fed's policy actions on the Fed Funds rate can do that.
Federal Reserve Governor Christopher Waller made a similar point in comments prior to the recent vote, noting that policy was "currently only slightly restricting aggregate demand," and that "it may not take much acceleration in inflation to nudge me into supporting tighter policy."
That sentiment demonstrates that policymakers view the front end, not the back end, of the yield curve as the inflation-credibility lever.
Summary
Long-term yields affect the economy and inflation, but often with a significant lag. Thus, the impact of higher yields has not yet been fully felt. Short-term rates tend to affect growth and inflation more immediately. That said, while stubbornly high inflation is a big problem and was used to justify last week’s decision, the recent inflation uptick and deviation from the downward inflation trend has been largely due to the Iranian conflict and higher energy prices.
The Fed Funds rate can't solve the Iranian oil problem. So, we must ask: Is the price of “restoring inflation credibility” worth it, if higher Fed Funds rates have a very limited impact on geopolitical supply-driven inflation but risk meaningful damage to economic activity?
Hiking into a supply shock driven by geopolitical conflict could prove to be a big policy error. By raising rates last week despite existing market tightening, the Fed risks over-constraining the economy, increasing the likelihood that this hike may eventually have to be reversed if growth stalls.
Read more by Michael Lebowitz:
Michael Lebowitz is a portfolio manager with RIA Advisors and author for Real Investment Advice. For more information, contact him at [email protected] or 301.466.1204.
Join RIA Advisors and elevate your career within a deeply experienced team focused on innovation. Our collaborative environment is built on a foundation of advanced technology and effective investment models, designed to enhance your ability to serve clients and grow your practice. Benefit from a supportive culture that encourages professional development and fosters a forward-thinking approach. By joining our team, you’ll be part of a group dedicated to excellence and continuous improvement, empowering you to focus on building meaningful client relationships and pursuing your business ambitions. Discover the advantages of working with our accomplished advisory team by starting your conversation today.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Read more articles by Michael Lebowitz
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.