Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
A wirehouse financial advisor recently asked me to run the numbers on his group long-term disability (LTD) coverage. He had enrolled years earlier and looked at the benefit summary, which indicated coverage for 60% of his earnings — a figure that seemed generous enough.
What he didn’t check was what that 60% was applied to. When I pulled the certificate and double-checked it years later when his wife was pregnant with twins, he was disappointed to learn it provided 60% of his base salary only.
The trailing commissions that made up most of his compensation were not in the formula at all. He found that out because he checked, not because anyone told him.
It’s an easy thing to miss.
The enrollment page says the plan replaces 60% of your income, and most people read that as 60% of what they earn. But the definition that governs the benefit is typically buried deeper, in the certificate's definition of covered monthly earnings.
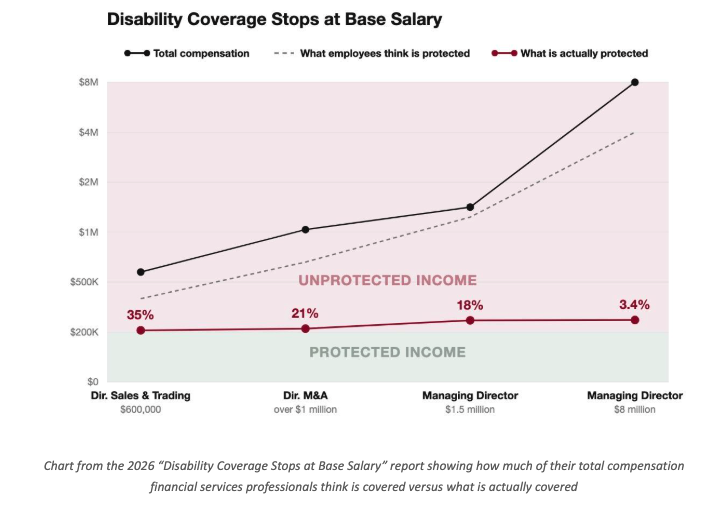
Many plans define the term as base salary. Some average commissions or bonuses over a prior period, and some leave them out entirely. Which plan you have depends on the contract. My firm's recent report, “Disability Coverage Stops at Base Salary,” documents the same base-salary pattern across the group plans of more than 2,900 financial services employers.
Running the Real Numbers: Base Versus Total Compensation
For a salaried employee, the difference is a rounding error. For a financial advisor who is paid on commission, it represents the bulk of their take-home pay.
Take a hypothetical financial advisor with a $120,000 base salary and $380,000 in commission income, so $500,000 in total compensation. A plan that replaces 60% of base pays $72,000 a year — or $6,000 a month — before taxes.
That is roughly 14% of what the household actually lives on, and that is before any monthly maximum the plan applies, as many do. Since it’s a group LTD plan paid by the employer, the benefits are taxable, reducing the net yield to closer to 40% of covered income.
None of this means group LTD plans are broken. Employers price and administer coverage against a fixed number. Commission income rises and falls with markets, clients, and production, so variable pay is excluded from the formula by design.
How to Calculate Your Unprotected Income
The fix starts with a document most people have never read. Check the actual certificate rather than the summary, and look for four things:
- Definition of covered monthly earnings
- Replacement percentage
- Elimination period
- Monthly maximum
Next, take your total compensation from the last two years of tax returns, average it, and subtract the annual benefit the group plan would actually pay. Whatever is left is your unprotected income. The open enrollment period, which runs from mid-October to the second week of November at most employers, is the ideal time to ask your benefits manager for a copy of the specimen policy so you can check.
Individual disability policies, which can be written as noncancelable with true own-occupation protection, are generally underwritten on documented earned income. For commission income, that usually means those same tax returns. My firm’s overview of how individual coverage works for commission income walks through what that calculation looks like.
Jamie K. Fleischner, CLU, ChFC, LUTCF, is the founder of Set for Life Insurance, an independent brokerage specializing in individual disability insurance near Wall Street. She can be reached at [email protected].
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Read more articles by Jamie K. Fleischner
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.