Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.
A client considering a passive ESG fund may associate “passive” with the low-cost, diversified market exposure familiar from broad-market index funds. But understanding how the fund tracks its index is different from understanding the sustainability judgments that index expresses.
When the Principles for Responsible Investment (PRI) consulted its signatories on passive ESG investing, respondents felt the need to challenge the choice of benchmark. In this context, the definition of passive was challenged, “given that ESG index construction and selection are active decisions.”1
Passive funds that mirror the S&P 500 or Russell 2500 have set the expectation that tracking a benchmark is mechanical. But in passive ESG funds, someone decides which activities matter when disqualifying a company, what rating is assigned and where the data comes from, where each threshold sits, when to review a holding, and how often the rules are revisited. Those benchmark decisions determine what a client owns.
Right now, flows returning to sustainable funds are going passive. U.S. sustainable funds returned to net inflows in the second quarter of 2026 after more than three years of withdrawals. Passive strategies drew $6.5 billion, while active funds lost $3.6 billion.2
As interest in passive ESG funds grows, advisors need to be prepared to explain not only the rules the funds follow, but also whose judgments those rules express — and whether they fit the client’s personal values.
Where the Judgment Lives
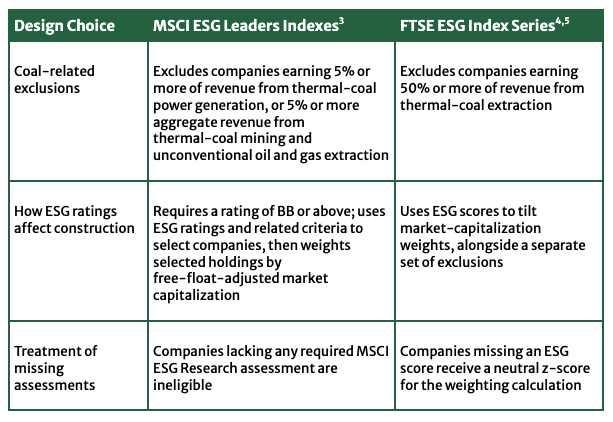
Two ESG index methodologies illustrate how choices about exclusions, ratings, and missing data can produce different investment exposures:
Both are rules-based, and both could be described as excluding coal. But their thresholds differ, and they define coal-based activities differently. Each benchmark provider is encoding a judgment, and a client who hears “this passive fund excludes coal” may not realize how much the definition of exclusion can vary.
Different Objectives, Different Judgments
In its earlier history, values-based investing meant excluding sin stocks. Known as socially responsible investing (SRI), a client-directed exclusion strategy identified businesses clients didn’t want to own, and the portfolio rules implemented those preferences.
The category has since expanded beyond SRI. Definitions published jointly by CFA Institute, the Global Sustainable Investment Alliance (GSIA), and PRI now distinguish five different approaches:6
-
Screening: applying rules based on criteria that determine if an investment is permissible; includes exclusionary, negative, positive, best-in-class, and norms-based screening
-
ESG Integration: ongoing consideration of ESG factors in the investment analysis and decision-making process; aims to improve risk-adjusted returns
-
Thematic Investing: selecting assets to access specified trends; focuses on forecasted trends and assets relevant to those trends
-
Stewardship: exercising investor rights and influence to safeguard and strengthen long-term value for clients and beneficiaries
-
Impact Investing: investing with the intention to improve social and/or environmental conditions; generate positive, measurable impacts alongside financial return on capital invested
These approaches can be combined, but they don’t make interchangeable promises. A client seeking to avoid particular businesses is asking a different question than one seeking to manage financially material ESG risks or support shareholder engagement. A standardized methodology can serve a defined objective, but the advisor must establish whether that objective, and its implementation, matches the client’s.
Where Customization Changes the Strategy
Some values-based advisors use client-specific overlays to adapt a common investment framework to individual preferences. In an index-guided account, a benchmark can provide the opportunity set and risk anchor, while a client-specific overlay excludes or reweights holdings within stated risk constraints.
The account remains index-guided, but client preferences now authorize departures from the benchmark’s holdings or weights. For a client whose values don’t match an off-the-shelf definition, that customization may be the point.
Adding proxy voting and engagement to a fund that holds the index as is changes how ownership rights are exercised, not what’s owned. This might meet some clients’ values-based preferences, but not all.
When Claims & Implementation Diverge
Over the past several years, the gap between what a fund holds and what it is named has caught regulators' attention. The SEC’s 2023 amendments to the Names Rule expanded the 80% investment-policy requirement to additional funds whose names suggest particular investment characteristics, including ESG-related factors. The amendments also require funds to review assets’ treatment under that policy at least quarterly.7 These requirements strengthen the connection between a fund’s name and its stated investment focus, but they don’t establish a common definition of sustainability.
An advisor also needs to distinguish a methodology that doesn’t fit their client from a screening process that doesn’t deliver what the fund promised. A separate SEC enforcement action against WisdomTree in 2024 (not brought under the amended Names Rule) illustrates the second problem. The SEC charged the firm with making misstatements and committing compliance failures involving ESG-marketed ETFs.
The SEC order stated that the funds were represented as excluding fossil fuels and tobacco, but they invested in companies involved in fossil fuels and tobacco, including coal mining and transportation, natural gas extraction and distribution, and retail sales of tobacco products. WisdomTree relied on vendor data that didn’t screen out all the companies involved in those activities, and failed to implement policies and procedures over the screening process.8
Although these were actively managed, model-based ETFs, not passive ESG funds, the case illustrates how disclosed screening criteria can fail in implementation. It doesn’t establish how prevalent such failures are.
What Advisors Need to Inspect
A passive ESG fund follows a set of rules, but those rules reflect judgments about what to include, exclude, and prioritize. The advisor needs to assess how well those choices match the client’s priorities:
-
Start with the promise. Is ESG being used to exclude activities, tilt toward higher scores, manage financially material risk, or support engagement? Which of those does the client think they’re buying?
-
Then move to the inputs. Whose ratings and what thresholds are used? What happens to a company with no data?
-
Last, determine what happens after the rules are set. How often does the index rebalance? Who changes the methodology and how often?
A fact sheet rarely reveals those answers. Methodology documents, prospectuses, and the holdings do.
A passive ESG fund can be a sound choice. Low cost and consistent rules are real advantages. But a client who buys one isn’t avoiding someone’s judgment. They’re adopting it. An advisor should be able to tell them whose judgment it is, and whether it fits.
Notes
1Felix Soellner, Toby Belsom, and Marisol Hernandez, “ESG & Passive Investment Strategies: Signatory Consultation Results” (Principles for Responsible Investment, 2020).
2Morningstar Manager Research, “Global Sustainable Fund Flows: Q2 2026” (Morningstar, July 2026).
3MSCI, “MSCI ESG Leaders Indexes Methodology” (MSCI, August 2024).
4FTSE Russell, “FTSE ESG Index Series Ground Rules,” v3.4 (LSEG, April 2026).
5FTSE Russell, “Guide to the Construction and Maintenance of Exclusion Lists used in FTSE Russell Indices,” v2.5 (LSEG, August 2026).
6CFA Institute, Global Sustainable Investment Alliance, and Principles for Responsible Investment, “Definitions for Responsible Investment Approaches” (November 2023).
7U.S. Securities and Exchange Commission, “SEC Enhances Rule to Prevent Misleading or Deceptive Fund Names,” press release, September 20, 2023.
8U.S. Securities and Exchange Commission, “SEC Charges Advisory Firm WisdomTree with Failing to Adhere to Its Own Investment Criteria for ESG-Marketed Funds,” press release 2024-17suggest g, October 21, 2024.
Lisa Marie Harast, CIPM® is the founder of The Write Investment, a strategic content consultancy specializing in sustainable finance communications. With over 20 years in investment communications and a CIPM from the CFA Institute, she helps sustainable finance firms close the credibility gap between rigorous methodology and clear, defensible communication.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
More Innovative ETFs Topics >
 Advisor Perspectives welcomes guest contributions. The views presented here do not necessarily represent those of Advisor Perspectives.