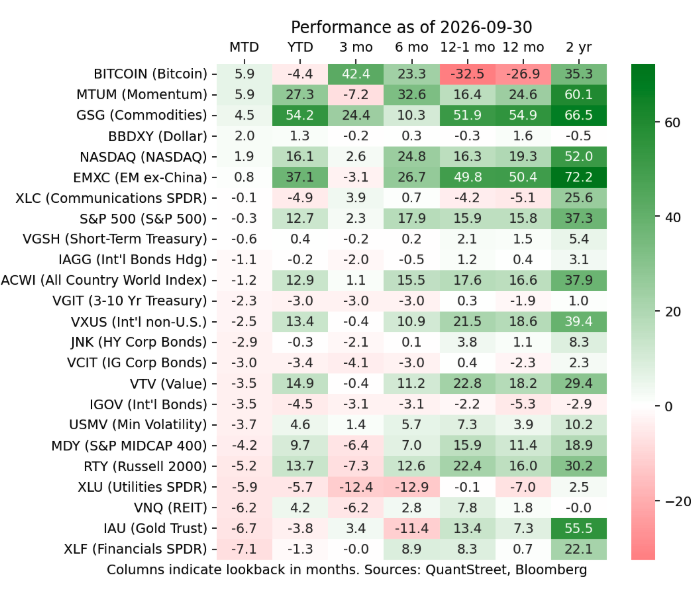
Societal angst about AI continues to grow. Whether it’s concern about misalignment or potentially misdirected investment, the AI-may-be-bad narrative is gaining traction. In stark contrast, the AI trade in financial markets was alive and well in September of 2026. Leading the way were Bitcoin and the iShares USA Momentum ETF (top holdings: AMD, Micron, Intel, Cisco, Applied Materials, etc.), with Nasdaq also positive. Surprisingly, commodities and the dollar both rallied, despite dollar strength usually being negative for commodities and news that oil shipments through the Strait of Hormuz have rebounded to 80% of their pre-war levels. The rest of the US stock universe fared poorly. Mid-caps and small-caps had an awful month (as did the equal-weighted S&P 500), and rate-sensitive sectors and assets got hammered (REITs, utilities, financials, and gold).
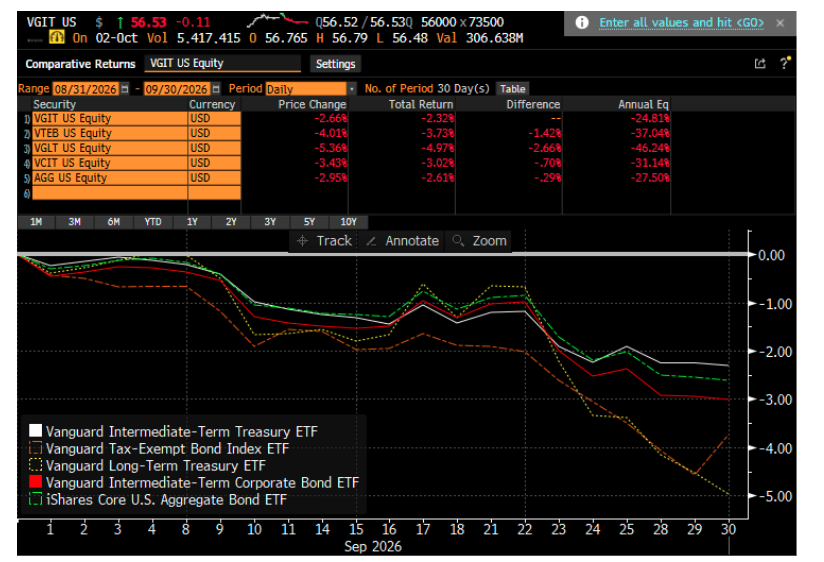
But the real carnage was reserved for fixed income markets. Ten-year Treasury yields finished the month over 50 basis points (0.5%) higher than their August close. And parts of the US fixed income markets were down between 2.3% and 5%.
Theories for why range from a loss of confidence in the dollar (hard to argue given the dollar’s appreciation in September), to a loss of confidence in the US government’s ability to repay its debts (also hard to argue given stable inflation breakevens, since the path to default for the US is through inflation), to anticipated high economic growth with large demand for capital by the hyperscalers. What gives more credence to this last point is that, usually, with such a large increase in interest rates, stock prices—which represent the discounted present value of future dividends—would be meaningfully lower. The fact that this did not happen suggests that markets believe that the numerator effect, i.e., higher future earnings and thus higher future dividends, is enough to offset the increase in the denominator, i.e., discount rates.
See more: When the Company Changes Before the Client
Our Balanced, Core, and Aggressive strategies were down on the month, though their performance was on average a bit better than that of benchmarks in September. You can see the performance numbers here. For relative performance, please reach out to us at [email protected]. Past performance is not indicative of future results, and we have had plenty of months of historical underperformance relative to benchmarks as well.
Fly in the ointment
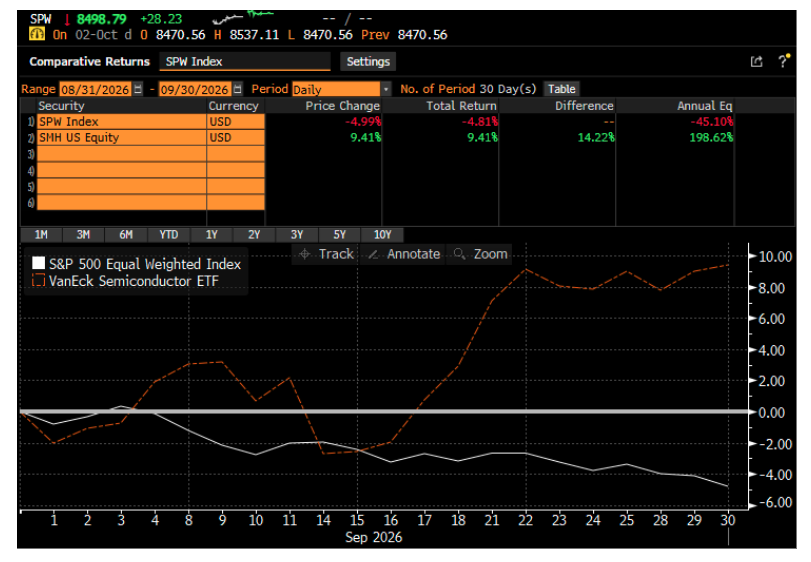
Here’s what’s bugging (couldn’t resist) us. Semiconductors, a big driver of momentum, had a great month in September, while the equal-weighted S&P 500 was a disaster. Here’s the picture:
I buy into the idea that companies are buying semiconductors, either directly or indirectly, in anticipation of productivity gains that these will facilitate and that will take time to materialize. Markets are willing to finance the buildout of capacity and software needed for these semiconductors to work in anticipation of profits that have yet to materialize. So not seeing profits yet in the rest of the corporate sector (ROCS) is not a surprise. But markets, being forward looking, should look forward to the future day when these profits will arrive and discount those back to today, to be reflected in higher current stock prices. But we did not see the latter in September. Semiconductors were up, but the ROCS weren’t. And if the latter don’t have the profitability to justify paying the former for their chips, then where does that leave us?
I learned long ago not to question market price action. Markets are usually smarter than any individual. But this month’s price action is puzzling.
Looking ahead
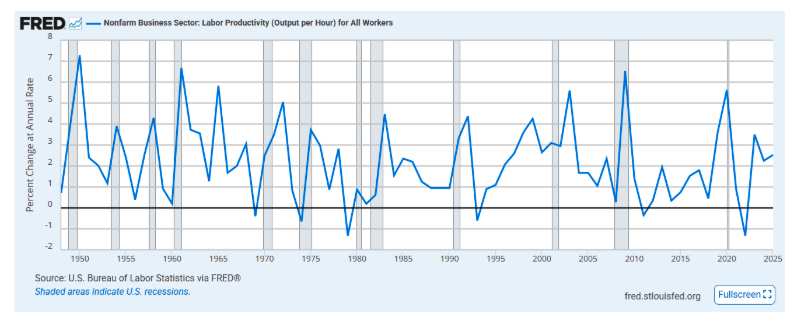
Our general feeling is that the AI trade is for real. We do not believe this is a bubble. Some very serious people (e.g., Jon Gray) take the AI buildout very seriously. But we are looking for signs that the benefits are starting to accrue to the rest of our economy. We’re starting to see signs of this in the BLS productivity data, which has been running well above its post-2010 average:
And we are looking for signs of this to start to show up in the profitability of companies outside of tech. We thus maintain relatively overweight exposures to value and low-volatility stocks, which give exposure to the ROCS but did not serve us well last quarter, while also keeping some outright tech exposure in our higher-risk portfolios. In the lower-risk portfolios we are moving to slightly longer duration exposures than we’ve been running for more than a year. Though our models still don’t like higher duration fixed income assets, a 5.25% 10-year Treasury yield is starting to look attractive. Despite this, we are still underweight duration relative to our benchmarks, though slightly less so than in the recent past.
While only appropriate for some clients, alternatives like private equity evergreen funds can provide useful diversification. As one reference point, some of these funds were up between 0.5% and 0.75% in September, behaving as diversifiers in a weak month for most stocks.
Working with QuantStreet
QuantStreet offers financial planning and wealth management services for individuals and families. For the advisor community, we offer model portfolios, portfolio analytics, and a platform for those looking to gain independence. The firm’s investment approach is systematic, data-driven, and shaped by years of investing experience. To work with or learn more about QuantStreet, join our mailing list or contact us at [email protected]. Also, please sign up for our Substack.
QuantStreet is a registered investment advisor. Registration does not imply a certain level of skill or training. All financial forecasts are fraught with risk and uncertainty. Our views may prove incorrect and market outcomes may be materially worse than we anticipate. Please see our full disclosure about the limitations of forward-looking statements and the risks of investing at https://quantstreetcapital.com/blog_disclosure/.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© QuantStreet Capital
More Volatility/Downside Protection Topics >