After years when yield was scarce and investors were pushed further out on the risk spectrum, income is investable again. High-quality bonds can once more provide meaningful cash flow, portfolio stability and a credible path to total return without requiring an aggressive call on interest rates or credit.
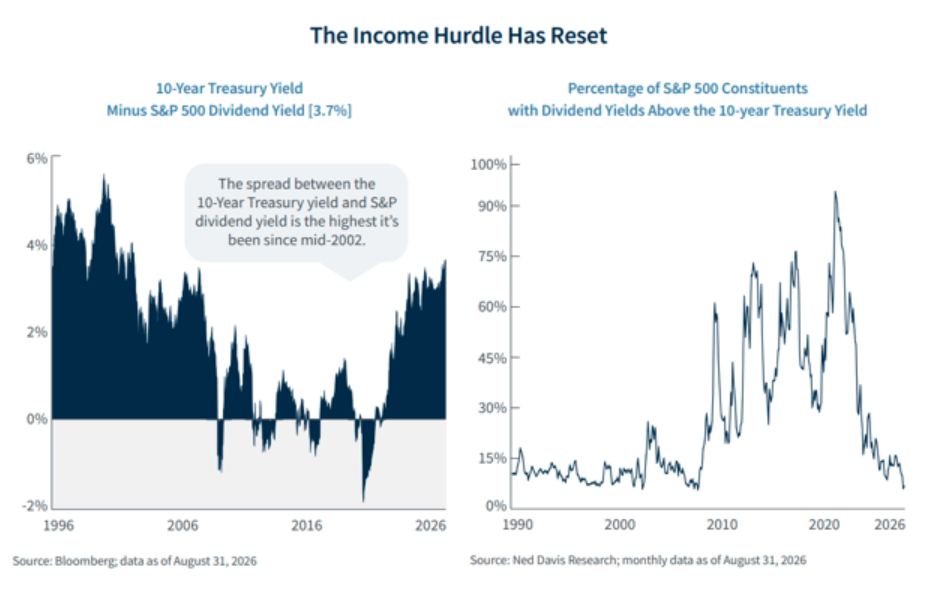
The 30-year Treasury recently moved above 5%, returning to a level not seen since before the Global Financial Crisis. Across the broader market, Treasuries and high-quality fixed-income sectors now offer yields in the mid-4% to mid-5% range, substantially above the dividend yield available from the broad equity market with the current spread between the 10-year Treasury and the S&P dividend yield the highest it’s been since mid-2002. The result is a materially different portfolio environment, one in which bonds can again serve as both a defensive allocation and a meaningful source of return.
From yield scarcity to yield choice
For more than a decade following the Global Financial Crisis (mid-2007 through early 2009), investors seeking income faced an uncomfortable choice: accept very little from high-quality bonds or reach for yield through longer duration, lower-quality credit, dividend-paying equities and less-liquid alternatives. That environment reflected slow growth, disinflation, central bank bond purchases and strong demand for a limited supply of high-quality assets. It lasted long enough that ultra-low rates began to feel permanent. They were not.
See more: Bonds. Worth a Look?
Although yields will continue to move with the economic cycle, we believe the equilibrium has shifted higher. Larger fiscal deficits, heavy Treasury issuance, more persistent inflation and a capital-intensive investment cycle are creating greater competition for capital. We also believe those forces leave longer-term yields with an upward bias, particularly as investors demand greater compensation for absorbing growing Treasury supply and duration risk.
The Federal Reserve can exert considerable influence over short-term rates, but longer-term yields are set primarily by the market’s view of growth, inflation, supply and term premium. Slower growth or market stress can still pull yields lower, but our base case is a higher structural range, not a return to the persistently low yields of the 2010s.
The equity-bond income hurdle has reset
The change is particularly visible in the comparison between bond yields and equity dividend yields. Treasuries and high-quality taxable fixed income sectors currently offer yields in the mid-4% to mid-5% range, while municipal bonds can provide even higher income on a tax-equivalent basis. That stands in sharp contrast to the dividend yield available from the broad equity market and represents a significant reversal from much of the post-Global Financial Crisis period.
The divergence extends beyond the index-level comparison. As of August 31, fewer than 4% of S&P 500 constituents offered dividend yields above the 10-year Treasury yield, according to Ned Davis Research, the lowest share since May 2007. In July 2016, more than 60% did. That reversal illustrates how much the current-income hurdle for equities has changed.
That does not mean bonds should replace stocks. A bond’s coupon is generally contractual, subject to the issuer’s ability to pay. An equity dividend is not guaranteed, but a well-selected dividend stream can grow over time, helping preserve purchasing power and participate in the growth of the underlying business. Bonds can provide higher current income and lower volatility; high-quality dividend-paying equities can provide growing income and long-term appreciation. Both can play distinct roles in an income-oriented portfolio.
Bond math is working again
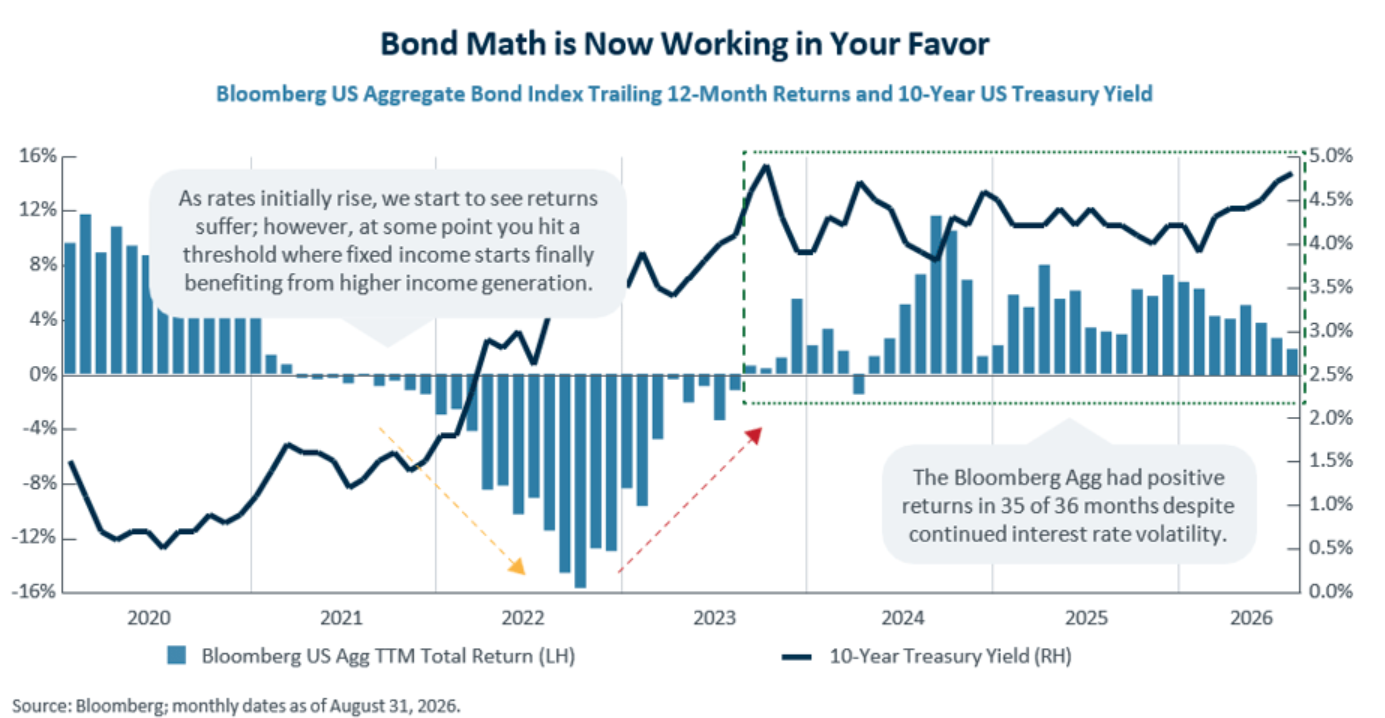
The scars of 2022 remain fresh because bonds failed to provide the stability many investors expected. Yields rose rapidly from an exceptionally low starting point, and coupons were too small to offset the price decline, particularly in longer-duration portfolios. Today’s starting point is different after that rip the band-aid moment. As of August 2026, the Bloomberg US Aggregate Bond Index had generated positive trailing 12-month returns in 35 of the prior 36 months despite continued rate volatility. Higher coupons, carry and reinvestment income have helped absorb periodic price weakness, while intermediate-maturity bonds may also benefit from roll down as they move closer to maturity.
The diversification case is also more nuanced than it was during the low-inflation era. Stock-bond correlations tend to become more positive when inflation is elevated, so bonds may not rally every time equities decline. But diversification was never solely about maintaining a permanently negative correlation. Bonds still provide contractual cash flows, daily liquidity and exposure to different economic risks. The preservation bonds provide today, with income doing the heavy lifting, is more stable and sustainable than negative price correlations as investors can benefit over a longer time horizon.
Treasuries can also regain their traditional ballast when growth, rather than inflation, becomes the market’s primary concern. For investors with ongoing spending needs, a high-quality bond allocation can also provide liquidity during periods of equity stress, reducing the risk of becoming a forced seller.
Attractive yields, but not everything is cheap
Investment-grade corporate bonds recently offered yields around 5.5%, but option-adjusted spreads were approximately 0.78%, well below their non-recessionary average of approximately 1.28%. Much of today’s all-in yield therefore comes from the higher underlying Treasury rate rather than unusually generous compensation for credit risk. Tight spreads leave less room for deteriorating fundamentals and less potential return from further spread compression. That reinforces the case for selectivity. Investors can earn attractive income without stretching aggressively down in quality or relying on further spread tightening. We favor staying up in quality, managing duration deliberately and using periods of heavy new issuance or spread widening to add exposure more opportunistically.
What this means for portfolios
The rise of bonds does not demand a wholesale retreat from equities. High-quality fixed income can once again fund spending needs, provide liquidity and carry more of a portfolio’s return requirement. That allows equity allocations to focus on long-term growth and dividend-growth potential rather than asking stocks to provide both current income and appreciation.
For investors approaching or in retirement, that liquidity can be particularly valuable. Aligning the fixed income allocation with near and intermediate-term spending needs can provide a source of capital during an equity market downturn and reduce the likelihood of having to sell stocks after prices have fallen. Forced selling can lock in losses and limit participation in an eventual recovery. With equity valuations elevated and bonds offering substantially more income than they did for much of the last decade, investors have an opportunity to build that liquidity before it is needed. The objective is not to predict the next downturn, but to structure the portfolio so that a downturn does not dictate when long-term assets must be sold.
Cash remains useful for near-term liquidity, but it is not a complete substitute for fixed income. Cash yields can reset quickly when monetary policy changes. Selectively extending into short- and intermediate-maturity bonds can lock in income for longer, reduce reinvestment risk and add the possibility of price appreciation if growth slows. With longer-term rates likely to remain elevated and potentially move higher, we continue to favor a deliberate approach to duration rather than relying on a large decline in yields to generate returns. That makes decisions around duration, credit and tax treatment increasingly important.
Bottom line
The low-rate era trained investors to think of income as scarce and risk-taking as the price of participation. Today, that tradeoff looks very different. Quality fixed-income sectors offer meaningful yields, the income advantage of high-quality bonds over the broad equity market is historically wide and higher starting coupons provide a better cushion against volatility. Higher rates create challenges for borrowers and governments; for savers and income-oriented investors, they create a more investable market. Income is back. The opportunity now is to capture it with quality, discipline and flexibility.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Eagle Income is an affiliate of Raymond James & Associates, Inc., and Raymond James Financial Services, Inc.
All expressions of opinion reflect the judgment of the author(s) and the Investment Strategy Committee and are subject to change. This information should not be construed as a recommendation. The foregoing content is subject to change at any time without notice. Content provided herein is for informational purposes only. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Past performance is not a guarantee of future results. Indices and peer groups are not available for direct investment. Any investor who attempts to mimic the performance of an index or peer group would incur fees and expenses that would reduce returns. No investment strategy can guarantee success. Economic and market conditions are subject to change. Investing involves risks including the possible loss of capital. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Diversification and asset allocation do not ensure a profit or protect against a loss.
Bond prices and yields are subject to change based upon market conditions and availability. If bonds are sold prior to maturity, you may receive more or less than your initial investment. Holding bonds to term allows redemption at par value. There is an inverse relationship between interest rate movements and fixed income prices. Generally, when interest rates rise, fixed income prices fall and when interest rates fall, fixed income prices rise.
Treasury securities are direct obligations of the United States Government. US government bonds are issued and guaranteed as to the timely payment of principal and interest by the federal government. There are special risks associated with investing with bonds such as interest rate risk, market risk, call risk, prepayment risk, credit risk, reinvestment risk, and unique tax consequences. To learn more about these risks and the suitability of these bonds for you, please contact your financial advisor.
Bloomberg US Aggregate (BBAG): The index is a measure of the investment grade, fixed-rate, taxable bond market of roughly 6,000 SEC-registered securities with intermediate maturities averaging approximately 10 years. The index includes bonds from the Treasury, Government-Related, Corporate, MBS, ABS, and CMBS sectors. S&P 500: This index is a broad-based measurement of changes in stock market conditions based on the average performance of 500 widely held common stocks. It consists of 400 industrial, 40 utility, 20 transportation, and 40 financial companies listed on US market exchanges. This is a capitalization-weighted calculated on a total return basis with dividends reinvested. The S&P represents about 75% of the NYSE market capitalization. Dividends are not guaranteed and must be authorized by the company’s board of directors.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website's users and/or members.
Raymond James & Associates, Inc., member New York Stock Exchange / SIPC, and Raymond James Financial Services, Inc., member FINRA / SIPC, are subsidiaries of Raymond James Financial, Inc.
Raymond James® and Raymond James Financial® and power of personal® are registered trademarks of Raymond James Financial, Inc.
© Raymond James
More Municipal Bonds Topics >