Key takeaways
-
AI diversification is becoming a key challenge for credit investors. The U.S. midterm election results could slow the AI buildout and near-term issuance but are unlikely to materially reduce its ultimate scale or financing needs. The pace of supply may slow, but concentration risk is unlikely to dissipate, reinforcing the case for diversification into high quality securitized products and emerging markets (EM).
-
Agency mortgage-backed securities (MBS) markets appear resilient, with attractive carry. The agency MBS sector has handled this cycle’s higher interest rates and volatility better than it did in 2023, offering a meaningful carry pickup relative to broader investment grade credit for comparable risk. Also, real estate investment trusts (REITs) have shown an ability to buy into weakness rather than being forced sellers.
-
In non-agency residential MBS, we see attractive risk-adjusted return potential. Extension risk, rather than credit risk, has pushed AAA spreads wider among nonqualified mortgages (non-QM) and improved the asset class’s carry profile. The market is starting to respond by issuing deals designed to speed up senior tranche paydowns.
-
EM debt offers less correlated sources of risk. The diversification argument for EM debt is that it offers exposure to a different mix of risks than the domestic U.S. market. The EM opportunity set is also expanding beyond index-eligible bonds.
The U.S. midterm election results have introduced a new source of friction for the AI buildout. As our colleague Libby Cantrill noted, many of the new Democratic governors-elect, along with other local, state, and federal officials, ran on platforms that included varying degrees of restrictions on data center development (see the 4 November 2026 article, “With Echoes of 1974, a Decisive Victory for the Democratic Party”).
These restrictions could slow the pace of data center construction and, with it, the near-term pace of AI-related issuance. But they are more likely to change the journey than the destination. Demand for compute remains strong, and the ultimate scale of the AI buildout is unlikely to shift materially simply because capacity takes longer to come online.
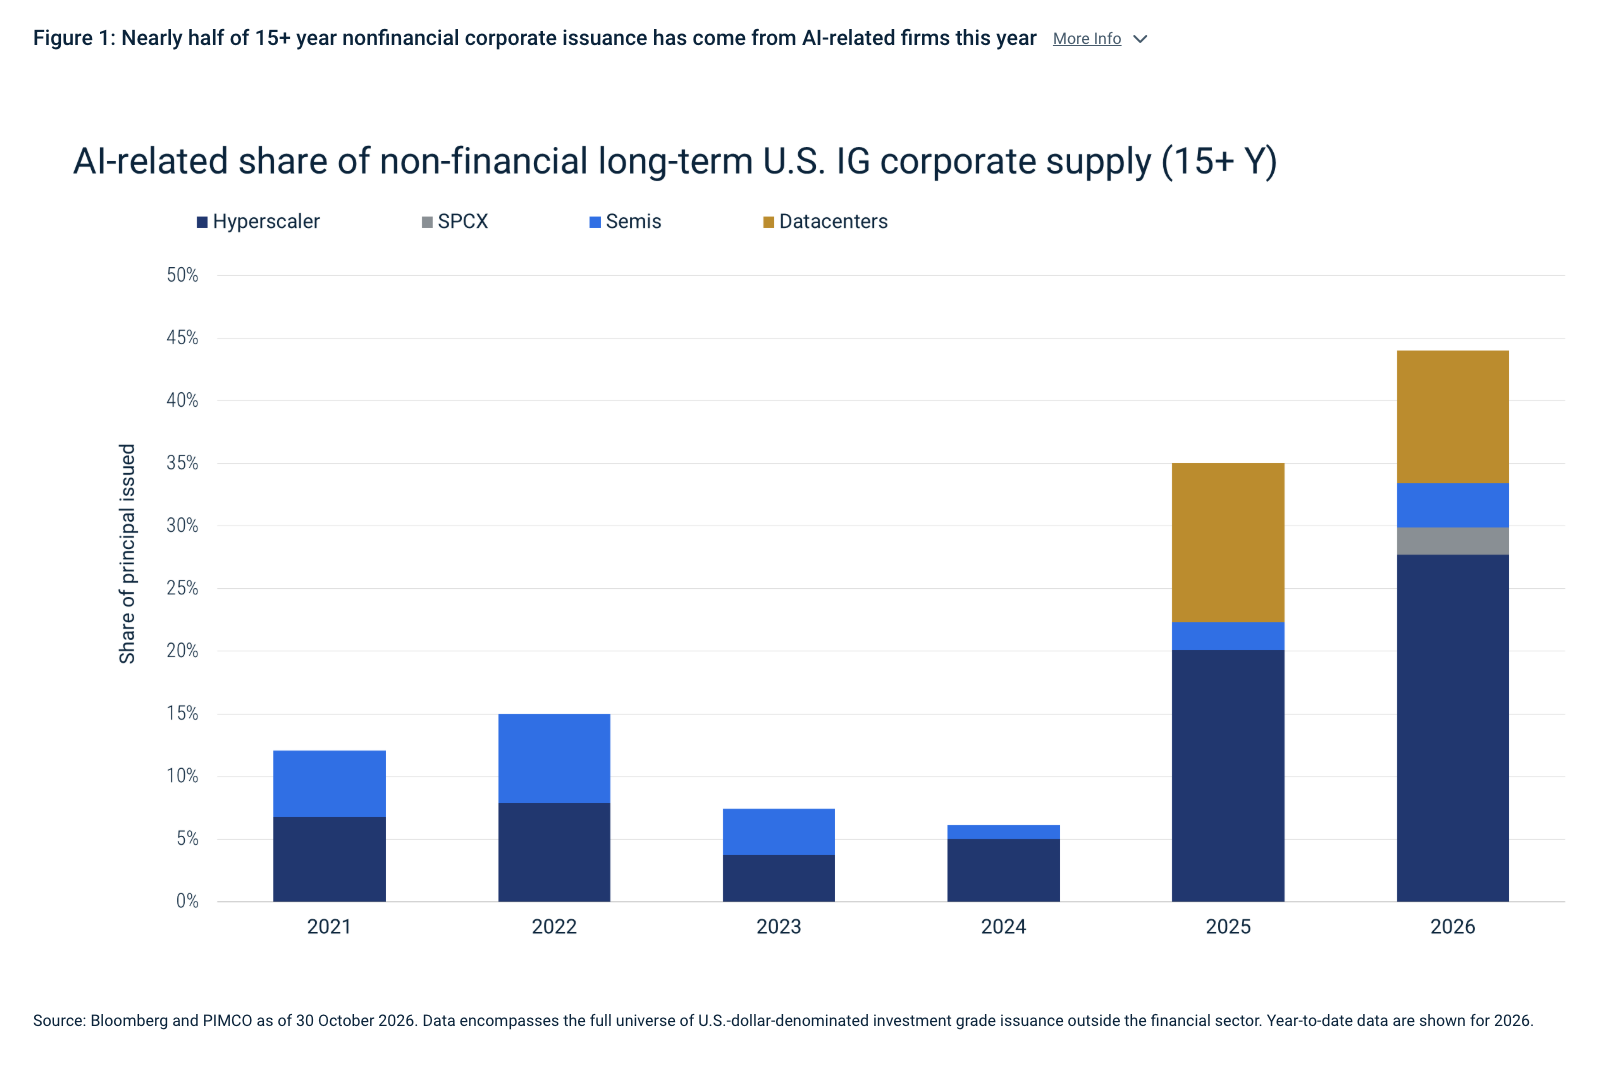
For credit investors, that means the pace of supply may slow, but the concentration challenge is unlikely to dissipate. A more gradual buildout could spread capital spending and financing over a longer period, but it does not eliminate the substantial funding needs associated with AI infrastructure. Concentration is already significant, particularly at the long end of the yield curve: Among nonfinancial sectors of the U.S. investment grade (IG) credit market, AI-related borrowers account for nearly half of year-to-date gross supply with maturities beyond 15 years (see Figure 1).
See more: AI Multiplies Advisor Expertise: A Computer Nerd Comes Clean
For long-duration investors in particular, the question therefore remains: Where can they source diversification from the AI investment theme?
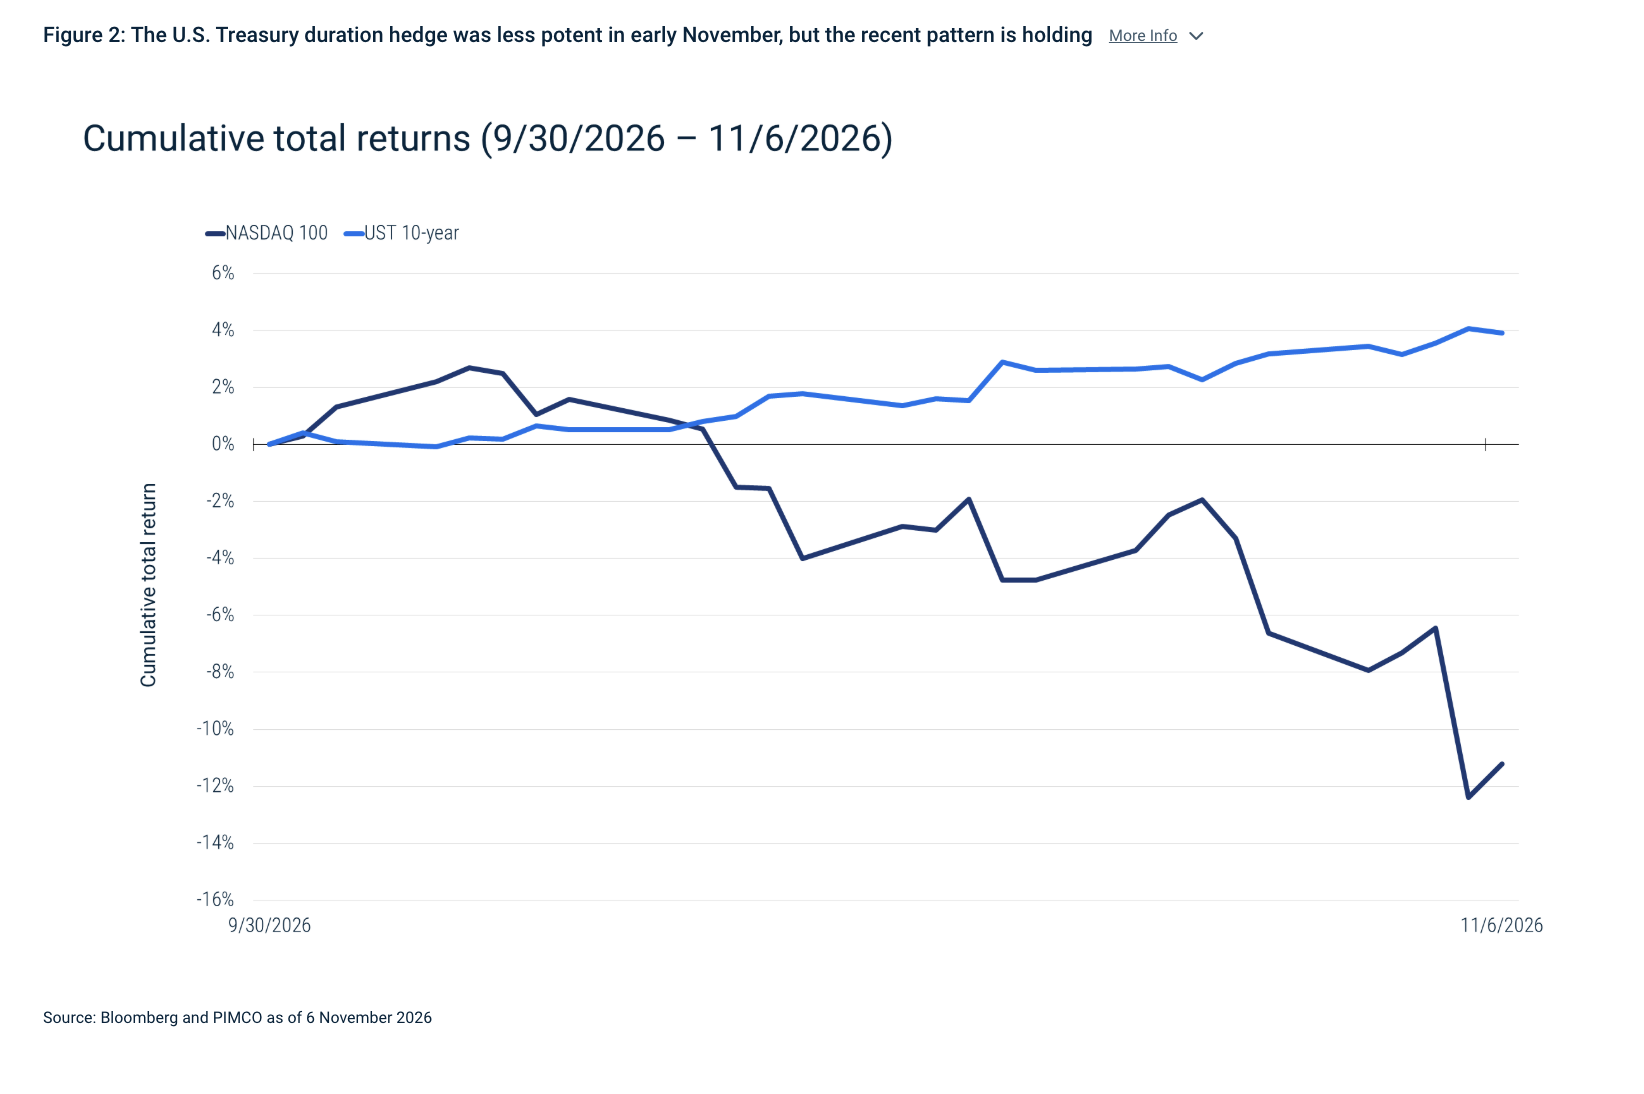
The classic portfolio hedge is U.S. Treasuries, and especially since the end of September, Treasuries have indeed rallied while risk assets have sold off – albeit with volatility across the board (see Figure 2).
But where else can investors diversify without paying too much for it? Within corporate credit, financials offer a large pool of IG exposure with much less direct sensitivity to the AI capex cycle, while “old economy” sectors such as energy can play a similar role in high yield (HY) markets. Both, however, are expensive, in our view – their spreads above like-maturity Treasuries generally appear tight relative to their risk-adjusted return potential.
Instead, we see other opportunities with more favorable diversification characteristics for investors wary of AI-related investment themes. In the U.S., high quality securitized products such as agency mortgage-backed securities (MBS) and non-agency residential MBS may provide meaningful uncorrelated exposure to the AI theme while still offering decent excess carry versus the broader IG market. Outside of the U.S., EM debt offers another source of diversification through a different mix of economic, policy, and country-specific risks.
Agency MBS: greater resilience, attractive carry
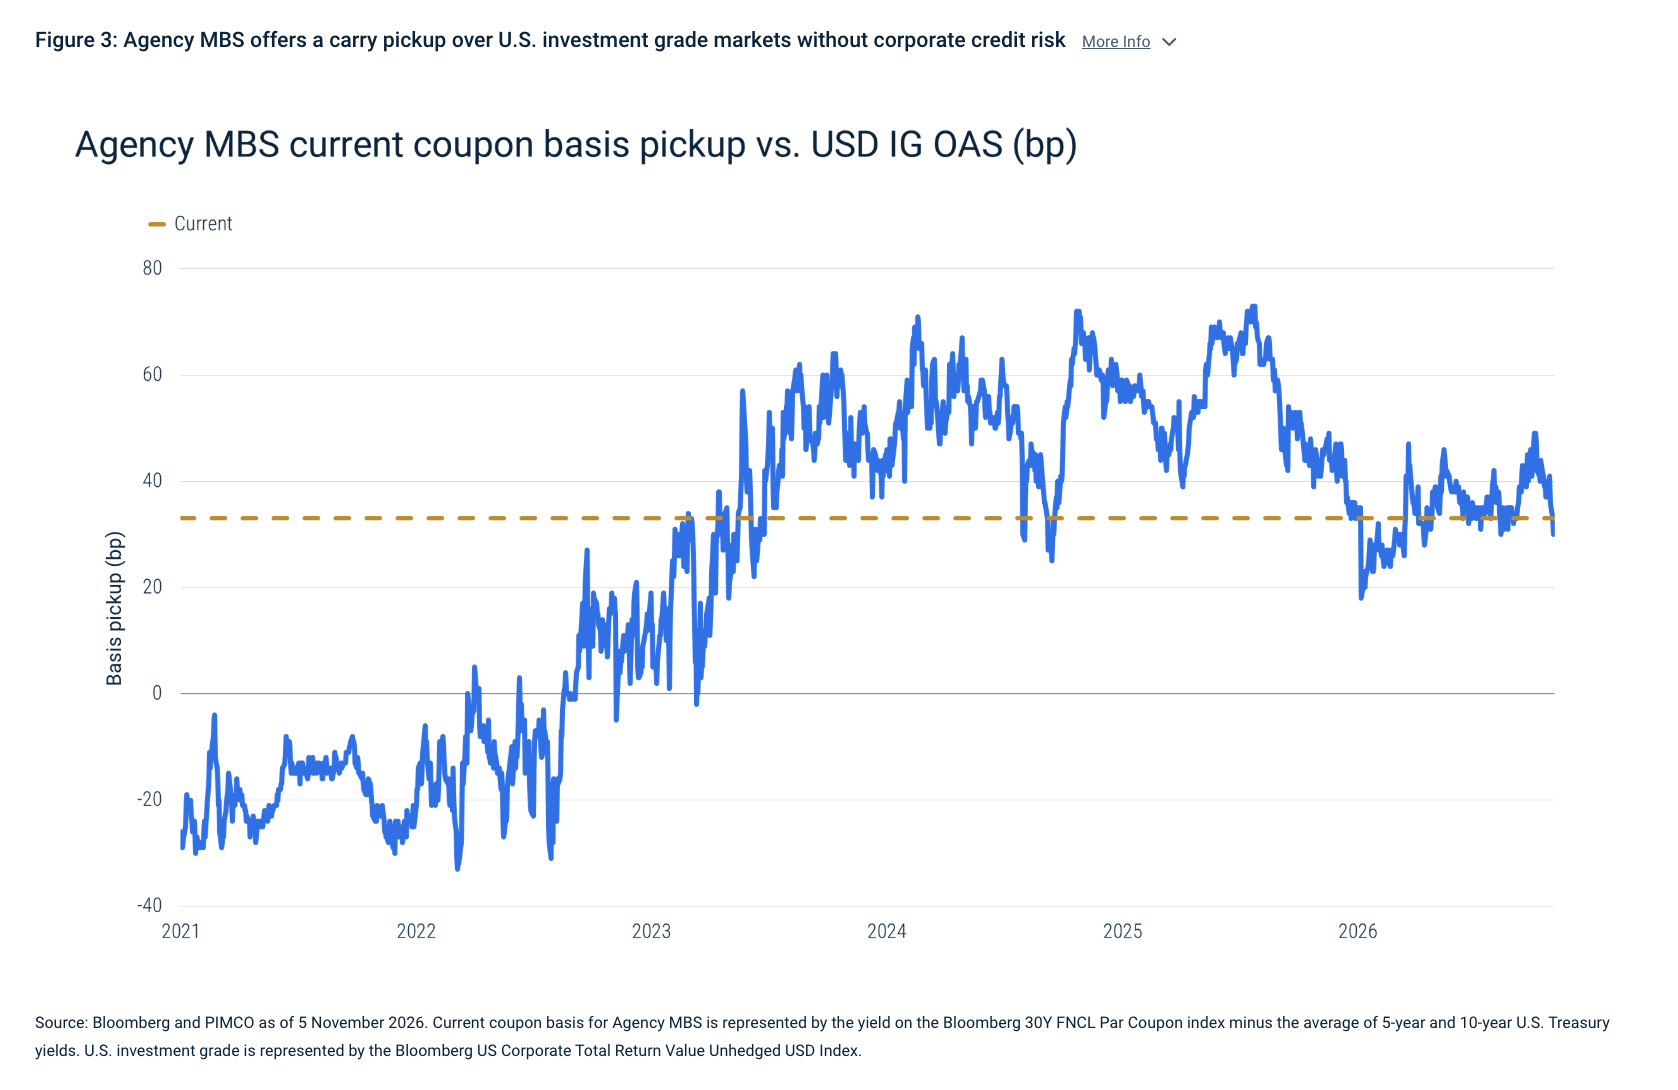
Agency MBS has been more resilient to higher rates and rate volatility this cycle than in 2023, supported by healthier balance sheets and stronger demand. Recent mortgage REIT earnings suggest REITs can increasingly buy into weakness rather than being forced to sell under pressure.
Elevated rate volatility still weighs on option-adjusted valuations, but nominal spreads offer positive excess carry over the broader IG universe without taking on corporate credit risk (see Figure 3).
In AAA nonqualified mortgages, potential benefits likely outweigh risks
For AAA rated nonqualified mortgage (non-QM) tranches, extension risk outweighs credit risk: Slower prepayments extend collateral life, while mortgages originated at lower rates make refinancing bonds at today’s higher coupons less economical, reducing issuers’ incentive to call existing deals.
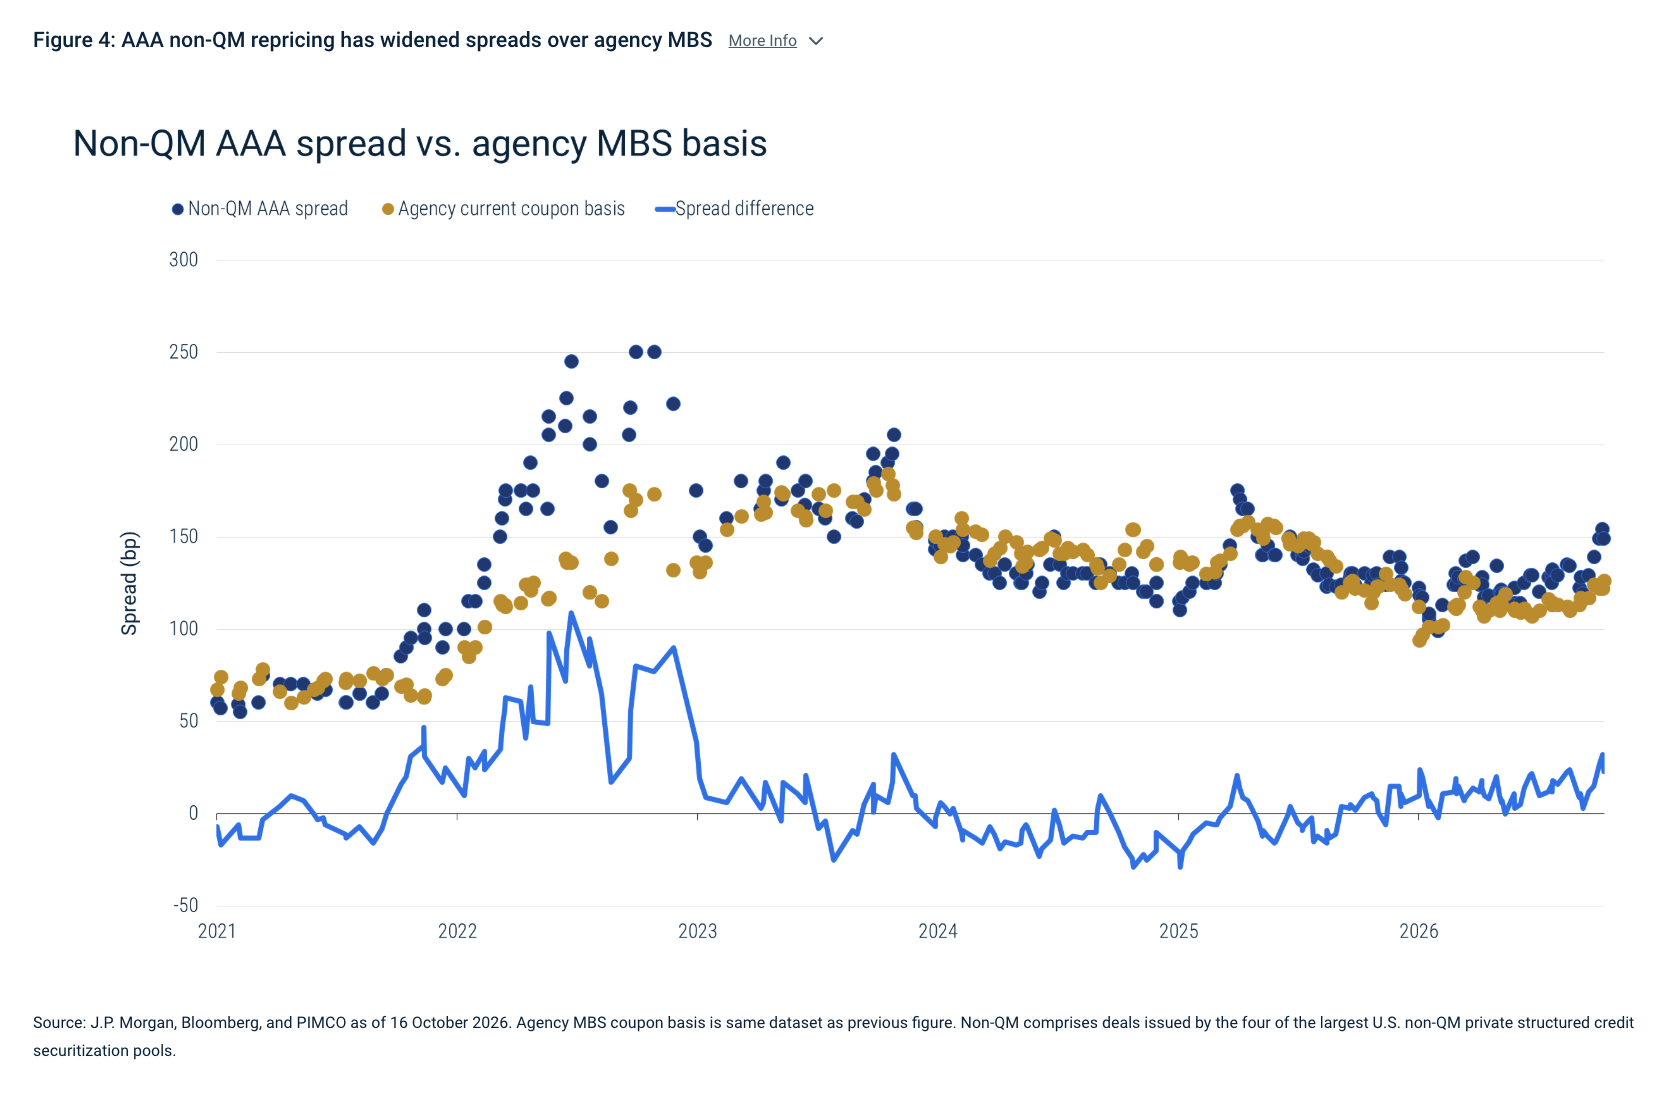
That concern has driven the recent widening in AAA spreads (see Figure 4). Extension risk is particularly problematic for deals issued earlier in 2026: If they remain outstanding beyond their call dates, senior coupons step up, raising funding costs and further compressing the excess spread available to support the structure. The market is starting to respond with new issues being redesigned to mitigate this risk. Many deals have shifted their principal waterfall structures to accelerate AAA paydowns and build credit enhancement faster. Many also allow lower-rated tranche interest payments to help fund senior coupon step-ups, thus reducing the burden on excess spread.
We think the repricing in AAA non-QM creates an intriguing opportunity. Wider spreads largely compensate investors for extension risk and structural risk tied to materially higher expected credit losses, and today’s new issues embed better mitigations against those risks than earlier deals.
Emerging market debt: less-correlated sources of risk
Although there are pockets of EM with meaningful AI exposure, notably South Korea and Taiwan, much of that is an equity story rather than a fixed income one. For bond portfolios, EM debt therefore remains a relatively differentiated source of yield, duration, and country-specific risk.
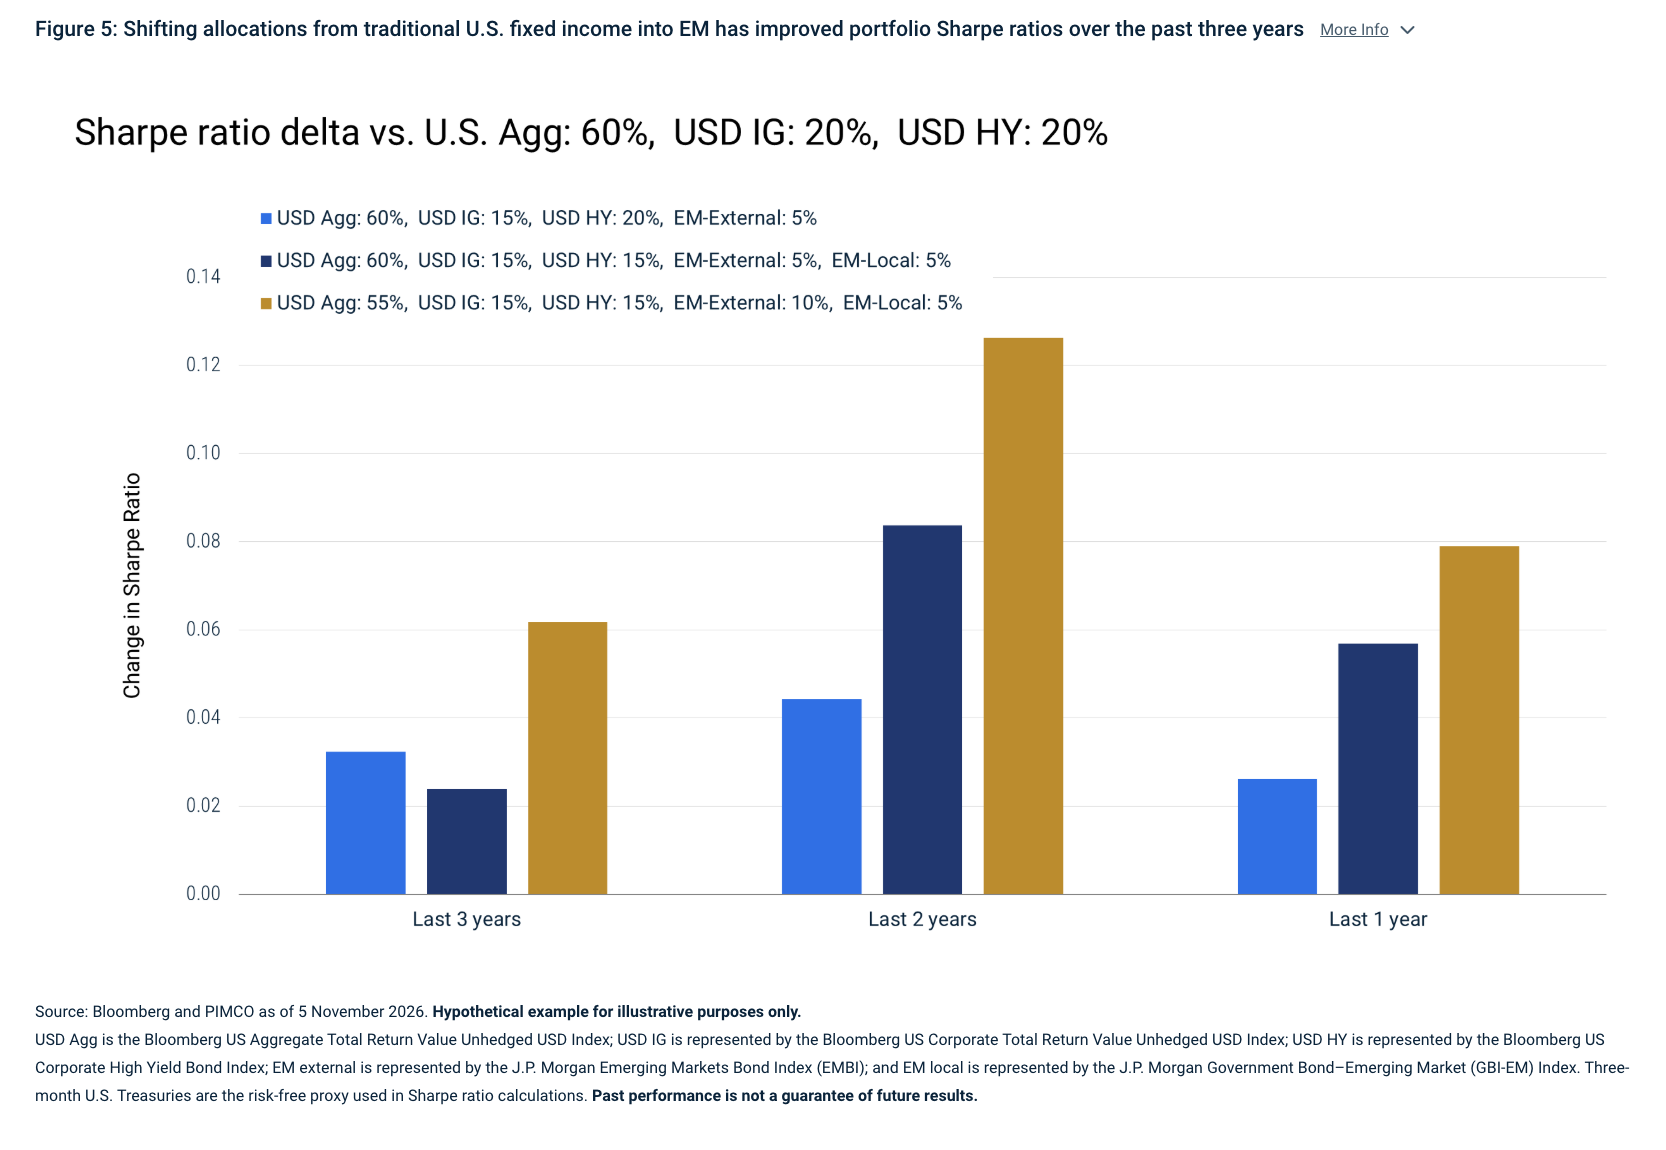
The diversification benefit has been meaningful, not just theoretical. Figure 5 illustrates the point with a hypothetical look at bond portfolio allocations. Starting from a conventional fixed income portfolio allocated 60% to the U.S. Agg, 20% to U.S. IG and 20% to U.S. HY, shifting modest allocations into EM external and local debt increased ex post Sharpe ratios (a measure of risk-adjusted return) by up to 0.13 over the past three years, depending on the allocation mix. In other words, EM improved returns per unit of risk for an overall fixed income portfolio.
To be clear, it is not that EM is a lower-risk asset class. Rather, it is that EM debt is exposed to a mix of political, fiscal, and monetary forces that are different than the risks facing the domestic U.S. market. Moreover, given the heterogeneity across EM countries, the next phase of the cycle may be less about buying EM beta, writ large, and more about choosing the right EM beta exposures. For example, commodity-exporting EMs would give fixed income portfolios a return driver that looks very different from U.S. credit or AI.
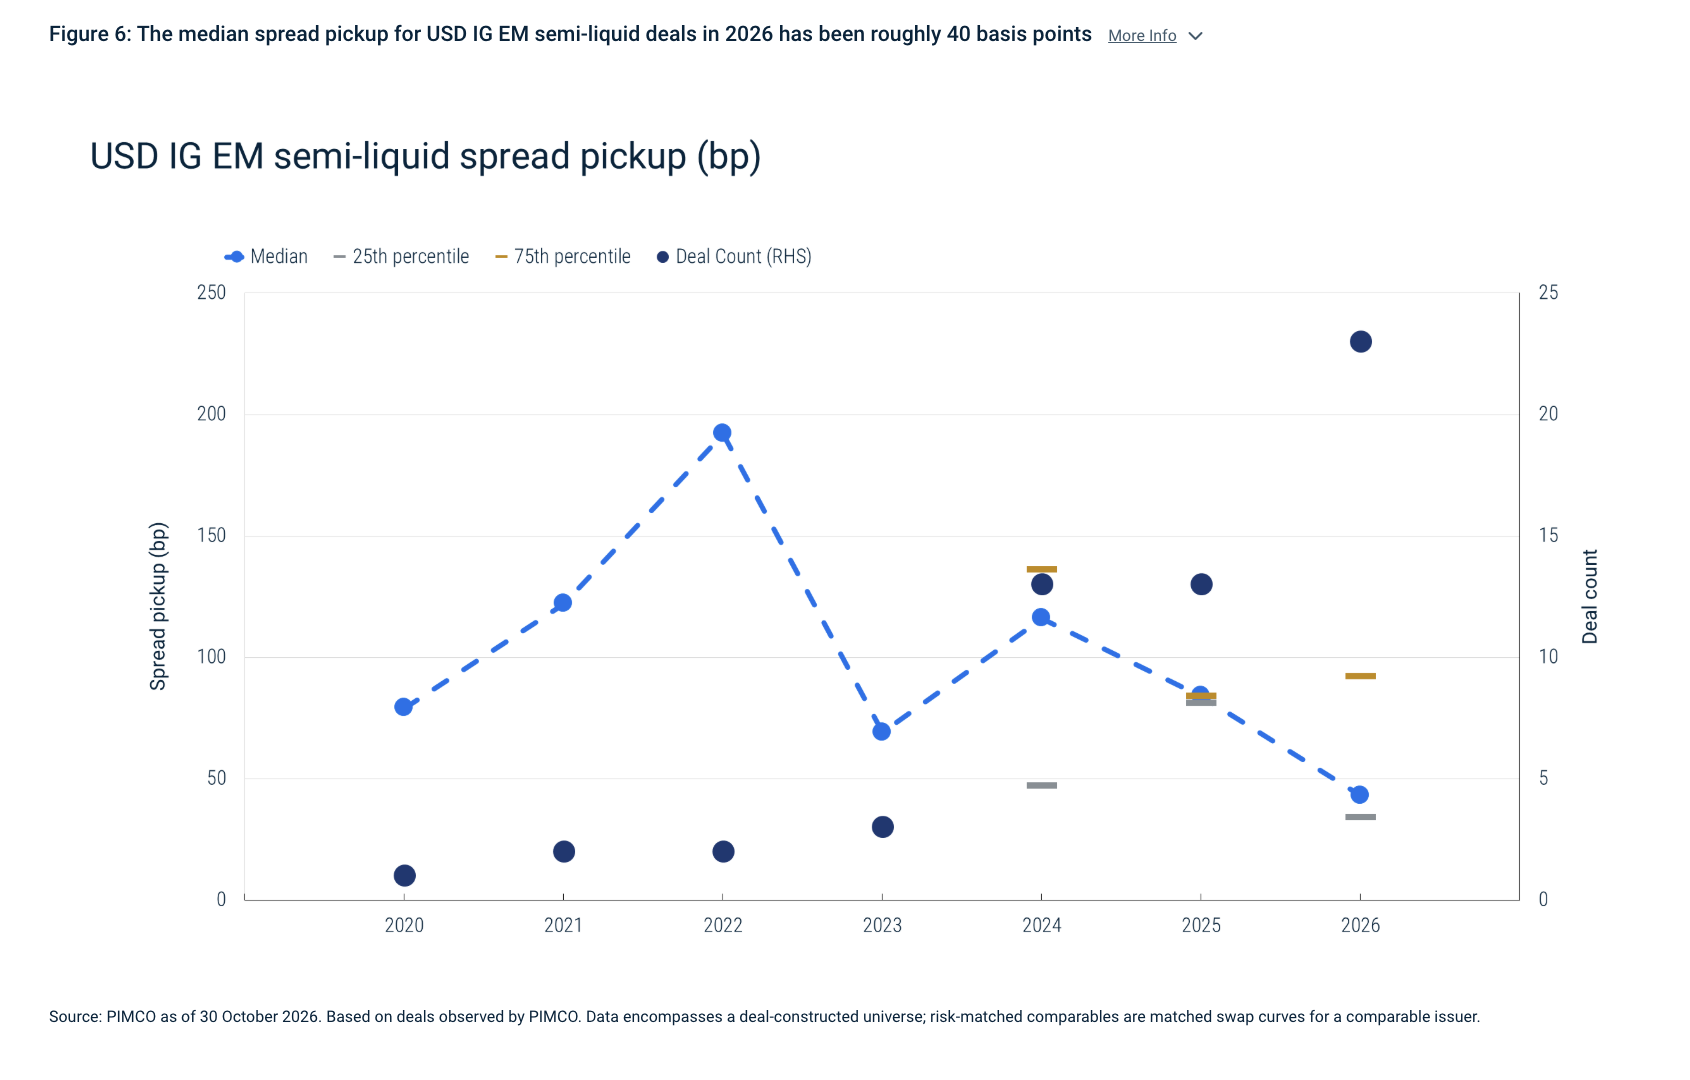
The EM opportunity set is also expanding beyond index-eligible bonds. Semi-liquid structures, often used to finance infrastructure investment, can offer a complexity premium over plain-vanilla EM bonds. For example, among U.S.-dollar-denominated IG deals for which we have data, the median spread pickup over risk-matched comparables – meaning the same issuer or similar risk, but matched to calculate the spread pickup – has been around 40 basis points so far this year (see Figure 6).
Michael Puempel and Gabriel Cazaubieilh contributed to this report.
Disclosures
Statements concerning financial market trends or portfolio strategies are based on current market conditions, which will fluctuate. Outlook and strategies are subject to change without notice.
Past performance is not a guarantee or a reliable indicator of future results. Forecasts, estimates and certain information contained herein are based upon proprietary research and should not be considered as investment advice. There is no guarantee that stated results will be achieved.
All Investments contain risk and may lose value. Investments with exposure to the artificial intelligence sector may involve heightened risks, including rapid technological change, competitive disruption, elevated valuations, regulatory uncertainty, data privacy and cybersecurity concerns, infrastructure dependencies, and reliance on third-party models or platforms. AI-related opportunities may not develop as expected, fail to produce anticipated productivity or revenue benefits, or be concentrated among a limited number of issuers, and could result in increased volatility or loss of capital. Bond investments are subject to market, interest rate, issuer, credit, inflation, and liquidity risks. Bond prices generally fall when interest rates rise, with longer-duration bonds typically more sensitive to rate changes. Reduced market liquidity may increase price volatility. Investors may receive more or less than their original investment upon redemption. Mortgage- and asset-backed securities may be sensitive to changes in interest rates, subject to early repayment risk, and while generally supported by a government, government-agency or private guarantor, there is no assurance that the guarantor will meet its obligations. U.S. agency mortgage-backed securities issued by Ginnie Mae (GNMA) are backed by the full faith and credit of the United States government. Securities issued by Freddie Mac (FHLMC) and Fannie Mae (FNMA) provide an agency guarantee of timely repayment of principal and interest but are not backed by the full faith and credit of the U.S. government. Investing in foreign-denominated and/or -domiciled securities may involve heightened risk due to currency fluctuations, and economic and political risks, which may be enhanced in emerging markets. Certain U.S. government securities (U.S. Treasuries) are backed by the full faith of the government. REITs are subject to risk, such as poor performance by the manager, adverse changes to tax laws or failure to qualify for tax-free pass-through of income. Equity investments may decline in value due to both real and perceived general market, economic and industry conditions, while debt investments are subject to credit, interest rate and other risks. The current regulatory climate is uncertain and rapidly evolving, and future developments could adversely affect the technology and AI sector.
The correlation of various indexes or securities against one another or against inflation is based upon data over a certain time period. These correlations may vary substantially in the future or over different time periods that can result in greater volatility. Option-Adjusted Spread (OAS) measures the yield spread of a fixed-income security over a benchmark interest rate curve after accounting for the value of any embedded options.
Hypothetical illustrations have many inherent limitations, some of which are described below. No representation is being made that any account will or is likely to achieve results similar to those shown. In fact there are frequently sharp differences between hypothetical results and actual results subsequently achieved by any particular trading program.
One of the limitations of hypothetical results is that they are generally prepared with the benefit of hindsight. In additional, hypothetical scenarios do not involve financial risk, and no hypothetical illustration can completely account for the impact of financial risk in actual trading. For example, the ability to withstand losses or to adhere to a particular trading program in spite of trading losses are material points which can also adversely affect actual trading results. There are numerous other factors related to the markets in general or to the implementation if any specific trading program which cannot be fully accounted for in the preparation of a hypothetical illustration and all of which can adversely affect actual results.
References to specific securities and their issuers are not intended and should not be interpreted as recommendations to purchase, sell or hold such securities. It is not possible to invest directly in an unmanaged index. Diversification does not ensure against loss.
PIMCO as a general matter provides services to qualified institutions, financial intermediaries and institutional investors. Individual investors should contact their own financial professional to determine the most appropriate investment options for their financial situation. This material contains the opinions of the author and such opinions are subject to change without notice. This material has been distributed for informational purposes only and should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information contained herein has been obtained from sources believed to be reliable, but not guaranteed. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission. PIMCO is a trademark of Allianz Asset Management of America LLC in the United States and throughout the world.
CMR2026-1106-6098132
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© PIMCO
More Innovative ETFs Topics >