Key takeaways:
- Regulatory fears regarding the AI buildout are likely overblown
- 3Q26 earnings reflect tech fundamentals remaining on solid footing
- Tech next-twelve-months (NTM) valuations are trading at a discount to the S&P 500
A chill has swept through the technology sector. After a red-hot start to the year, outperforming the S&P 500 by an impressive 1,608 basis points through September, tech has cooled considerably, lagging the broader market by 9.3% quarter to date. The sector is now on pace for its worst quarterly relative performance since 3Q02, as concerns over AI capital investment, increased equity issuance and policy implications from the midterm elections weigh on sentiment. Yet we believe this cooling period is more of a seasonal shift than a fundamental change. Here are five reasons we remain optimistic on technology's long-term prospects.
Strong demand absorbs new supply
A key overhang for tech has been the anticipated equity supply from IPOs of major frontier AI companies. On Thursday (November 19), Anthropic is set to go public in what could be the second-largest IPO in history, behind only SpaceX. With concerns mounting over AI financing and a potential slowdown in capital investment, this IPO could provide important insights on two fronts.
First, Anthropic is reportedly targeting a market cap above $1.5 trillion, with the offering already well oversubscribed, signaling strong investor appetite for AI assets. Second, its S-1 filing offers a revealing look at frontier AI economics, highlighting robust revenue growth, expanding compute commitments and improving profitability dynamics (e.g., declining compute costs as a percentage of revenue). Together, these developments may help ease concerns over AI funding and the durability of AI demand.
Regulatory headwinds may be overstated
It is important to put the potential economic impact of state-level data center moratoriums into perspective. Such restrictions primarily affect future data center projects in the pipeline, not those already under construction. In fact, the total power capacity of data centers currently being built is more than 1.5x that of existing facilities, highlighting the substantial runway for AI infrastructure investment over the next several years. Reinforcing this outlook, commentary from companies across the AI ecosystem, including Duke Energy, Micron, GE Vernova and Seagate, suggests demand and backlogs remain strong through at least 2028.
Looking further ahead, given the economic benefits many data center investments bring to local communities, we expect the industry to more effectively address common misconceptions surrounding water usage and electricity prices. Greater transparency should help ease concerns, paving the way for continued data center expansion and sustained technology investment.
See more: The Fed Risks a Policy Error Fighting Oil Prices
Earnings remain on solid footing
In recent quarters, earnings season has typically been a catalyst for technology stocks, with the sector gaining an average of 4.5% during the last 10 earnings seasons.* This quarter, however, tech has fallen approximately 10% throughout 3Q26 earnings, marking its worst earnings-season performance since 1Q22. We believe this selloff is disconnected from the fundamentals.
Consensus earnings per share (EPS) estimates for 2027 have risen 3.4% since earnings season began, the second-largest upward revision of any sector, trailing only energy. Meanwhile, consensus is calling for 2027 EPS growth to outpace the rest of the index by 37%, exceeding this year's 34% premium. Although concerns have intensified around semiconductors, which are projected to drive approximately 60% of next year's EPS growth, leading chipmakers continue to signal demand will exceed supply through at least 2027, supporting expectations for 67% EPS growth next year.
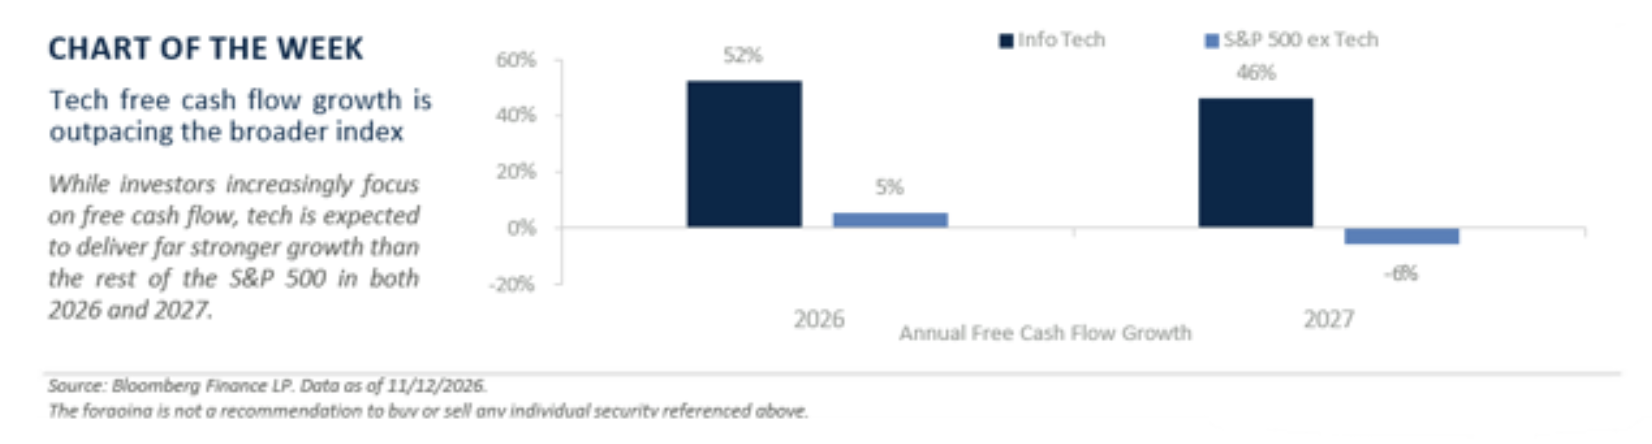
Moreover, select key tech firms (mainly among hyperscalers) have seen declines in free cash flow to finance AI infrastructure, but the tech sector's free cash flow in aggregate is projected to surge 52% in 2026 and 46% in 2027. This dwarfs growth for the rest of the index (5% and -6%, respectively). Taken together, these trends reinforce our conviction that tech's fundamentals remain very strong.
AI demand still healthy
While AI-related capex has dominated headlines, the tangible benefits of these investments are becoming increasingly clear. 3Q26 earnings provided compelling evidence. Cloud computing revenue at major hyperscalers jumped 63% year over year, accelerating from 54% in 2Q26, while cloud backlogs surged 141% to $1.8 trillion.
These expanding backlogs signal sustained demand for AI solutions and help justify hyperscalers' continued investment. Importantly, AI adoption is also gaining momentum across industries. According to Ramp, 57% of businesses now use AI-related products, up from 44% a year ago. Together, these trends highlight a healthy AI ecosystem, where accelerating adoption, growing backlogs and demand exceeding supply continue to support the investment cycle.
Tech valuations increasingly attractive
Tech entered 2026 facing a significant valuation hurdle, with its NTM P/E at 27x, near its highest level since 2002. Fast forward to today, and the picture looks very different. Despite a 15% year-to-date gain, tech's NTM P/E has fallen 32%, its steepest contraction at this point in a year since 2008, driven by strong earnings growth.
The sector now trades at its lowest multiple since 2020 and at a discount to the S&P 500 for the first time since 2019. With valuations reset and AI capex and earnings still on solid footing moving forward, we believe much of the bad news is priced in, creating an attractive opportunity for investors.
*Measured as Micron through NVIDIA release dates.
All expressions of opinion reflect the judgment of the author(s) and the Investment Strategy Committee and are subject to change. This information should not be construed as a recommendation. The foregoing content is subject to change at any time without notice. Content provided herein is for informational purposes only. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Past performance is not a guarantee of future results. Indices and peer groups are not available for direct investment. Any investor who attempts to mimic the performance of an index or peer group would incur fees and expenses that would reduce returns. No investment strategy can guarantee success.
Economic and market conditions are subject to change. Investing involves risks including the possible loss of capital.
The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Diversification and asset allocation do not ensure a profit or protect against a loss.
The S&P 500 Total Return Index: The index is widely regarded as the best single gauge of large-cap U.S. equities. There is over USD 7.8 trillion benchmarked to the index, with index assets comprising approximately USD 2.2 trillion of this total. The index includes 500 leading companies and captures approximately 80% coverage of available market capitalization.
Sector investments are companies focused on a specific economic sector and are presented here for illustrative purposes only. Sectors, including technology, are subject to varying levels of competition, economic sensitivity, and political and regulatory risks. Investing in any individual sector involves limited diversification.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website's users and/or members.
Raymond James & Associates, Inc., member New York Stock Exchange / SIPC, and Raymond James Financial Services, Inc., member FINRA / SIPC, are subsidiaries of Raymond James Financial, Inc.
Raymond James® and Raymond James Financial® and power of personal® are registered trademarks of Raymond James Financial, Inc.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Raymond James
More Innovative ETFs Topics >