Wrappers rarely make headlines, but for taxable investors, they could be just as decisive as other choices.
Most investors spend their time thinking about what they own and who manages their money—active or passive, stocks or bonds, public or private. But few stop to consider how those assets are held. Two investors with identical strategies might see very different outcomes simply because of vehicle choice. That structure—or “wrapper”—can also impact taxes, flexibility and, ultimately, returns.
What’s in an Investment Wrapper?
By taking the same assets and putting them in a different vehicle, investors can materially alter the taxes they incur. The shift can show up immediately in after-tax returns, but it also affects how investment decisions are handled for different investors. For instance, the wrapper determines who controls when capital gains are realized, how much flexibility a portfolio manager has to reposition (and how evenly those changes are felt by different investors), and the cost and complexity of the portfolio.
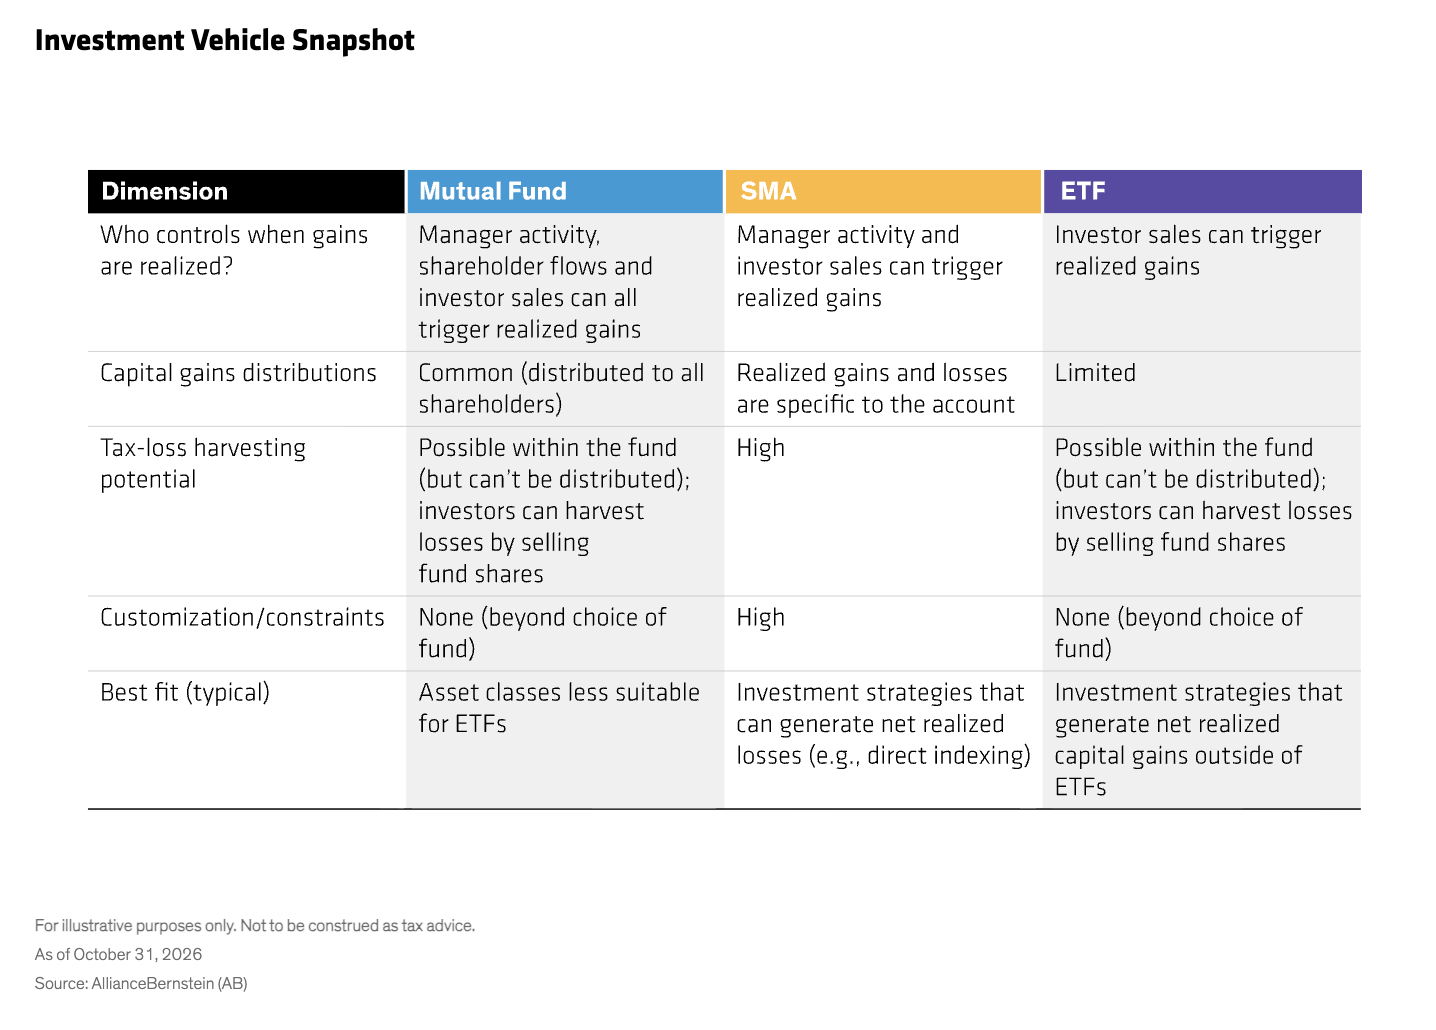
The Display below provides a quick way to compare three common wrappers at a glance.
In the early days of the investment industry, mutual funds became the primary vehicle of choice. Investors valued their professional management, diversification, administrative simplicity and liquidity in a world where those attributes were hard to find.
For decades, mutual funds were the most practical way for most investors to access the markets. But in taxable accounts, they come with an unavoidable drawback: shareholders have no control over when taxes are realized. Capital gains generated inside the fund must be distributed to all shareholders in the year the gain is realized. That happens whether an investor bought the fund days earlier or years earlier—and even if they didn’t sell a single share.
Mutual funds’ design allows investors to pool their capital, diversify and access regular liquidity. But it also leaves fund investors sharing tax burdens with a broad pool of shareholders whose time horizons, tax situations and goals may look nothing like their own.
For tax-sensitive investors, that loss of control may be costly over time. It often means paying taxes sooner than they’d like, shrinking the amount left over to compound.
With that said, mutual funds still have their place. They provide access to certain asset classes that are too difficult to reach operationally through other structures. And for non-taxable or tax-exempt accounts, these tax challenges simply don’t apply.
See more: Municipal vs. Corporate Bonds: How to Decide?
SMAs: Sophisticated, but Not an All-Purpose Tool
Over the past decade or so, separately managed accounts (SMAs) have come into vogue, thanks to their greater control over taxes and customization. This control is especially attractive for investors with concentrated wealth, specific constraints or large embedded capital gains. Because SMAs involve owning individual securities, they enable tailored tax-loss harvesting. The more investors value these benefits, the more likely an SMA will be an appropriate choice.
An SMA’s effectiveness depends heavily on the nature of the underlying investment strategy. Passive strategies based around an index tend to have inherently low turnover. With relatively few realized gains to manage, the tax focus shifts toward systematically harvesting losses, which an SMA can make immediately available while mutual funds and ETFs can’t. In many cases, it’s possible to generate net capital losses that investors can immediately put to use.
In contrast, active strategies typically involve higher turnover. Here, the tax challenge revolves around controlling the timing and character of realized gains: deferring them where possible and favoring long‑term over short‑term gains. In practice, tax managing a highly active strategy in an SMA—while staying faithful to the investment approach—often involves trade-offs between realizing gains and increasingly deviating from an ideal portfolio.
Those trade-offs become more pronounced when investors withdraw cash. Raising liquidity inside an SMA may force additional realized gains and push the portfolio away from its intended targets. While managers can skew sales toward lots with losses or smaller gains—often with the potential to improve tax outcomes relative to a simple pro‑rata sale—that flexibility may come at the cost of higher tracking error. For some investors, the compromise is worth it; for others, the calculus may look very different.
ETFs Offer Efficiency and Scale
Exchange-traded funds (ETFs) were designed to avoid many of the structural inefficiencies investors had previously deemed unavoidable.
Most ETFs are designed to manage portfolio turnover without triggering capital gains distributions to remaining investors, thanks to an in-kind creation and redemption process. As a result, taxes are primarily driven by an investor’s own buying and selling decisions, rather than from ongoing activity inside the portfolio or decisions made by other shareholders.
In our view, this enables portfolio managers to focus on building and maintaining portfolios without worrying about generating taxable gains for ETF holders. Positions can be adjusted or exited without causing gains or losses for investors, allowing the portfolio to reflect insights and strategy more accurately.
For many diversified, active equity strategies, ETFs may be as or more tax efficient than SMAs, while letting managers keep portfolios aligned with their views. Add in lower costs, daily liquidity and operational simplicity, and ETFs become a very compelling option indeed.
That said, ETFs aren’t the perfect fit for everyone or every situation. Sometimes, an SMA is still the best option.
Different Investor Needs, Different Wrappers
A discussion of investment vehicles isn’t really a good, better or best story. It’s more about how finance has evolved and how different investment structures fit different needs. Each wrapper comes with its own set of trade-offs, making it better suited for certain situations, whether that’s existing portfolios, tax implications, varying degrees of market liquidity, or more.
In practice, ETFs tend to suit a wide range of client needs. But SMAs may be especially valuable for investors facing specific tax challenges or concentrated stock positions. Even mutual funds have their place, offering exposure to strategies that might not be available through other vehicles. The key is to ensure that the right investors are matched with the right allocations inside the right wrappers.
The views expressed herein do not constitute research, investment advice or trade recommendations, do not necessarily represent the views of all AB portfolio-management teams and are subject to change over time.
Paul Robertson is the Chief Investment Officer of AllianceBernstein’s Tax Managed Strategies team, a part of the Equities department.
Gavin Romm is a Senior Vice President and Head of Separately Managed Accounts (SMA).
Mark Gleason is a Senior Vice President, Managing Director and Head of the Multi-Asset and Hedge Fund Business Development team for the Americas, where he's broadly responsible for portfolio strategy and communications.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© AllianceBernstein
Read more commentaries by AllianceBernstein