Consumer sentiment rises in November to the highest level in three months. The preliminary November reading for the University of Michigan Consumer Sentiment Index came in at 51.0. This marks a 6.3% (3.0 points) increase from October. Consumer sentiment sits flat compared to a year ago and is currently in the 1st percentile in the series' history.
Key Takeaways
-
The University of Michigan Consumer Sentiment Index preliminary reading rose to 51.0 in November, a 6.3% increase from October.
- The Current Economic Conditions Index rose 9.2% to 51.0, while the Consumer Expectations Index rose 4.3% to 50.9.
- Year-ahead inflation expectations decreased from 4.7% to 4.3% from October.
Joanne Hsu, the director of surveys, made the following comments:
Consumer sentiment ticked up about 6% in the preliminary read. Modest improvements in multiple domains, including expected personal finances and business conditions, were concentrated primarily among independents. While sentiment lifted for lower- and middle-wealth consumers, it fell 5% for those with the largest stock portfolios in the wake of a relatively turbulent period in stock markets. Moreover, consumers’ comments revealed growing anxiety over a possible AI bubble. AI worries, however, were dwarfed by cost of living concerns, which continue to be at the forefront of consumers’ minds across the population. About 57% spontaneously mentioned that their living standards have been eroded by high prices, the highest seen since May and up from 46% in February, just prior to the Iran conflict. Despite this month’s improvement, sentiment is down 10% from February. Interviews for this release were conducted between October 20 and November 2. In the two months leading into the election, more than two-thirds of consumers expected Democrats to win the House, and over half anticipated the same for the Senate (see the October 30th special report on election expectations).
Background on the University of Michigan Consumer Sentiment Index
The Michigan Consumer Sentiment Index is a monthly survey of consumer confidence levels in the U.S. with regards to the economy, personal finances, business conditions, and buying conditions, conducted by the University of Michigan. There are two reports released each month; a preliminary report released mid-month and a final report released at the end of the month.
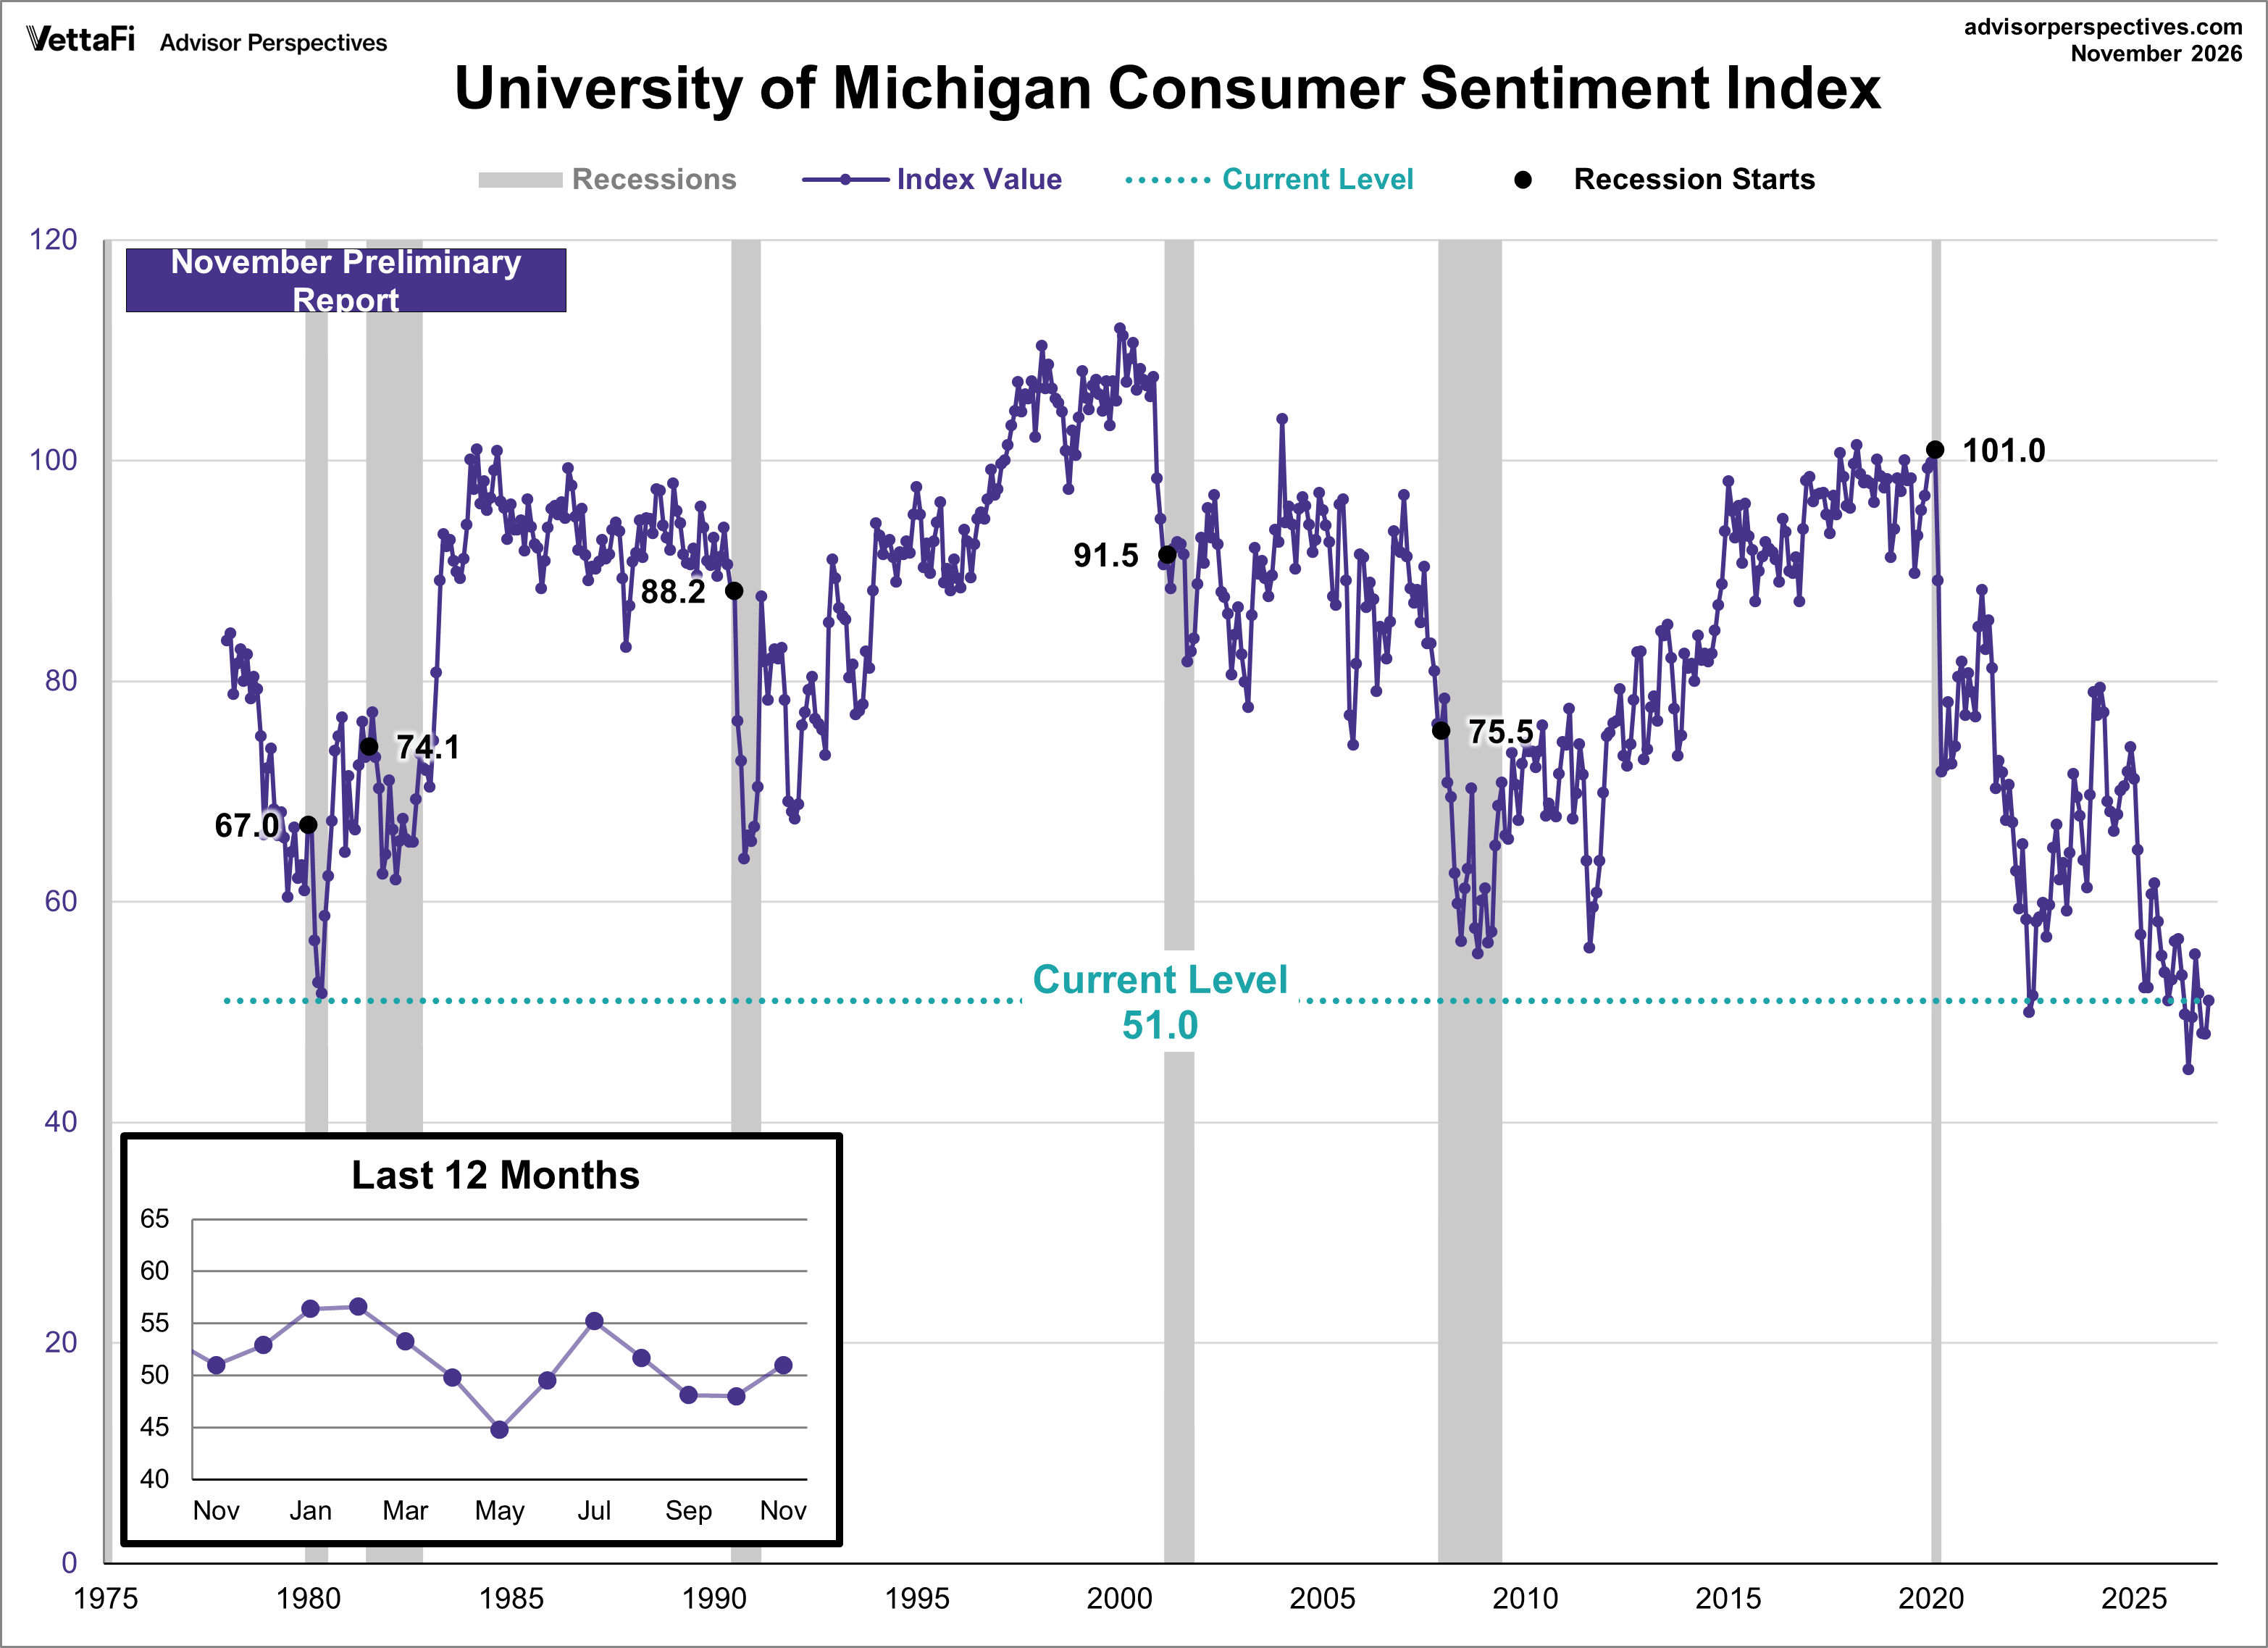
The chart below provides a long-term perspective on this widely watched indicator. We have highlighted the index's value at the start of each recession. The current level of 51.0 is below the index's value at the start of all six recessions since its inception.

To put today’s report in historical context, consumer sentiment is currently 38.9% below its average reading of 83.5 (arithmetic mean) and 38.0% below its geometric mean of 82.2, based on data dating back to 1978.
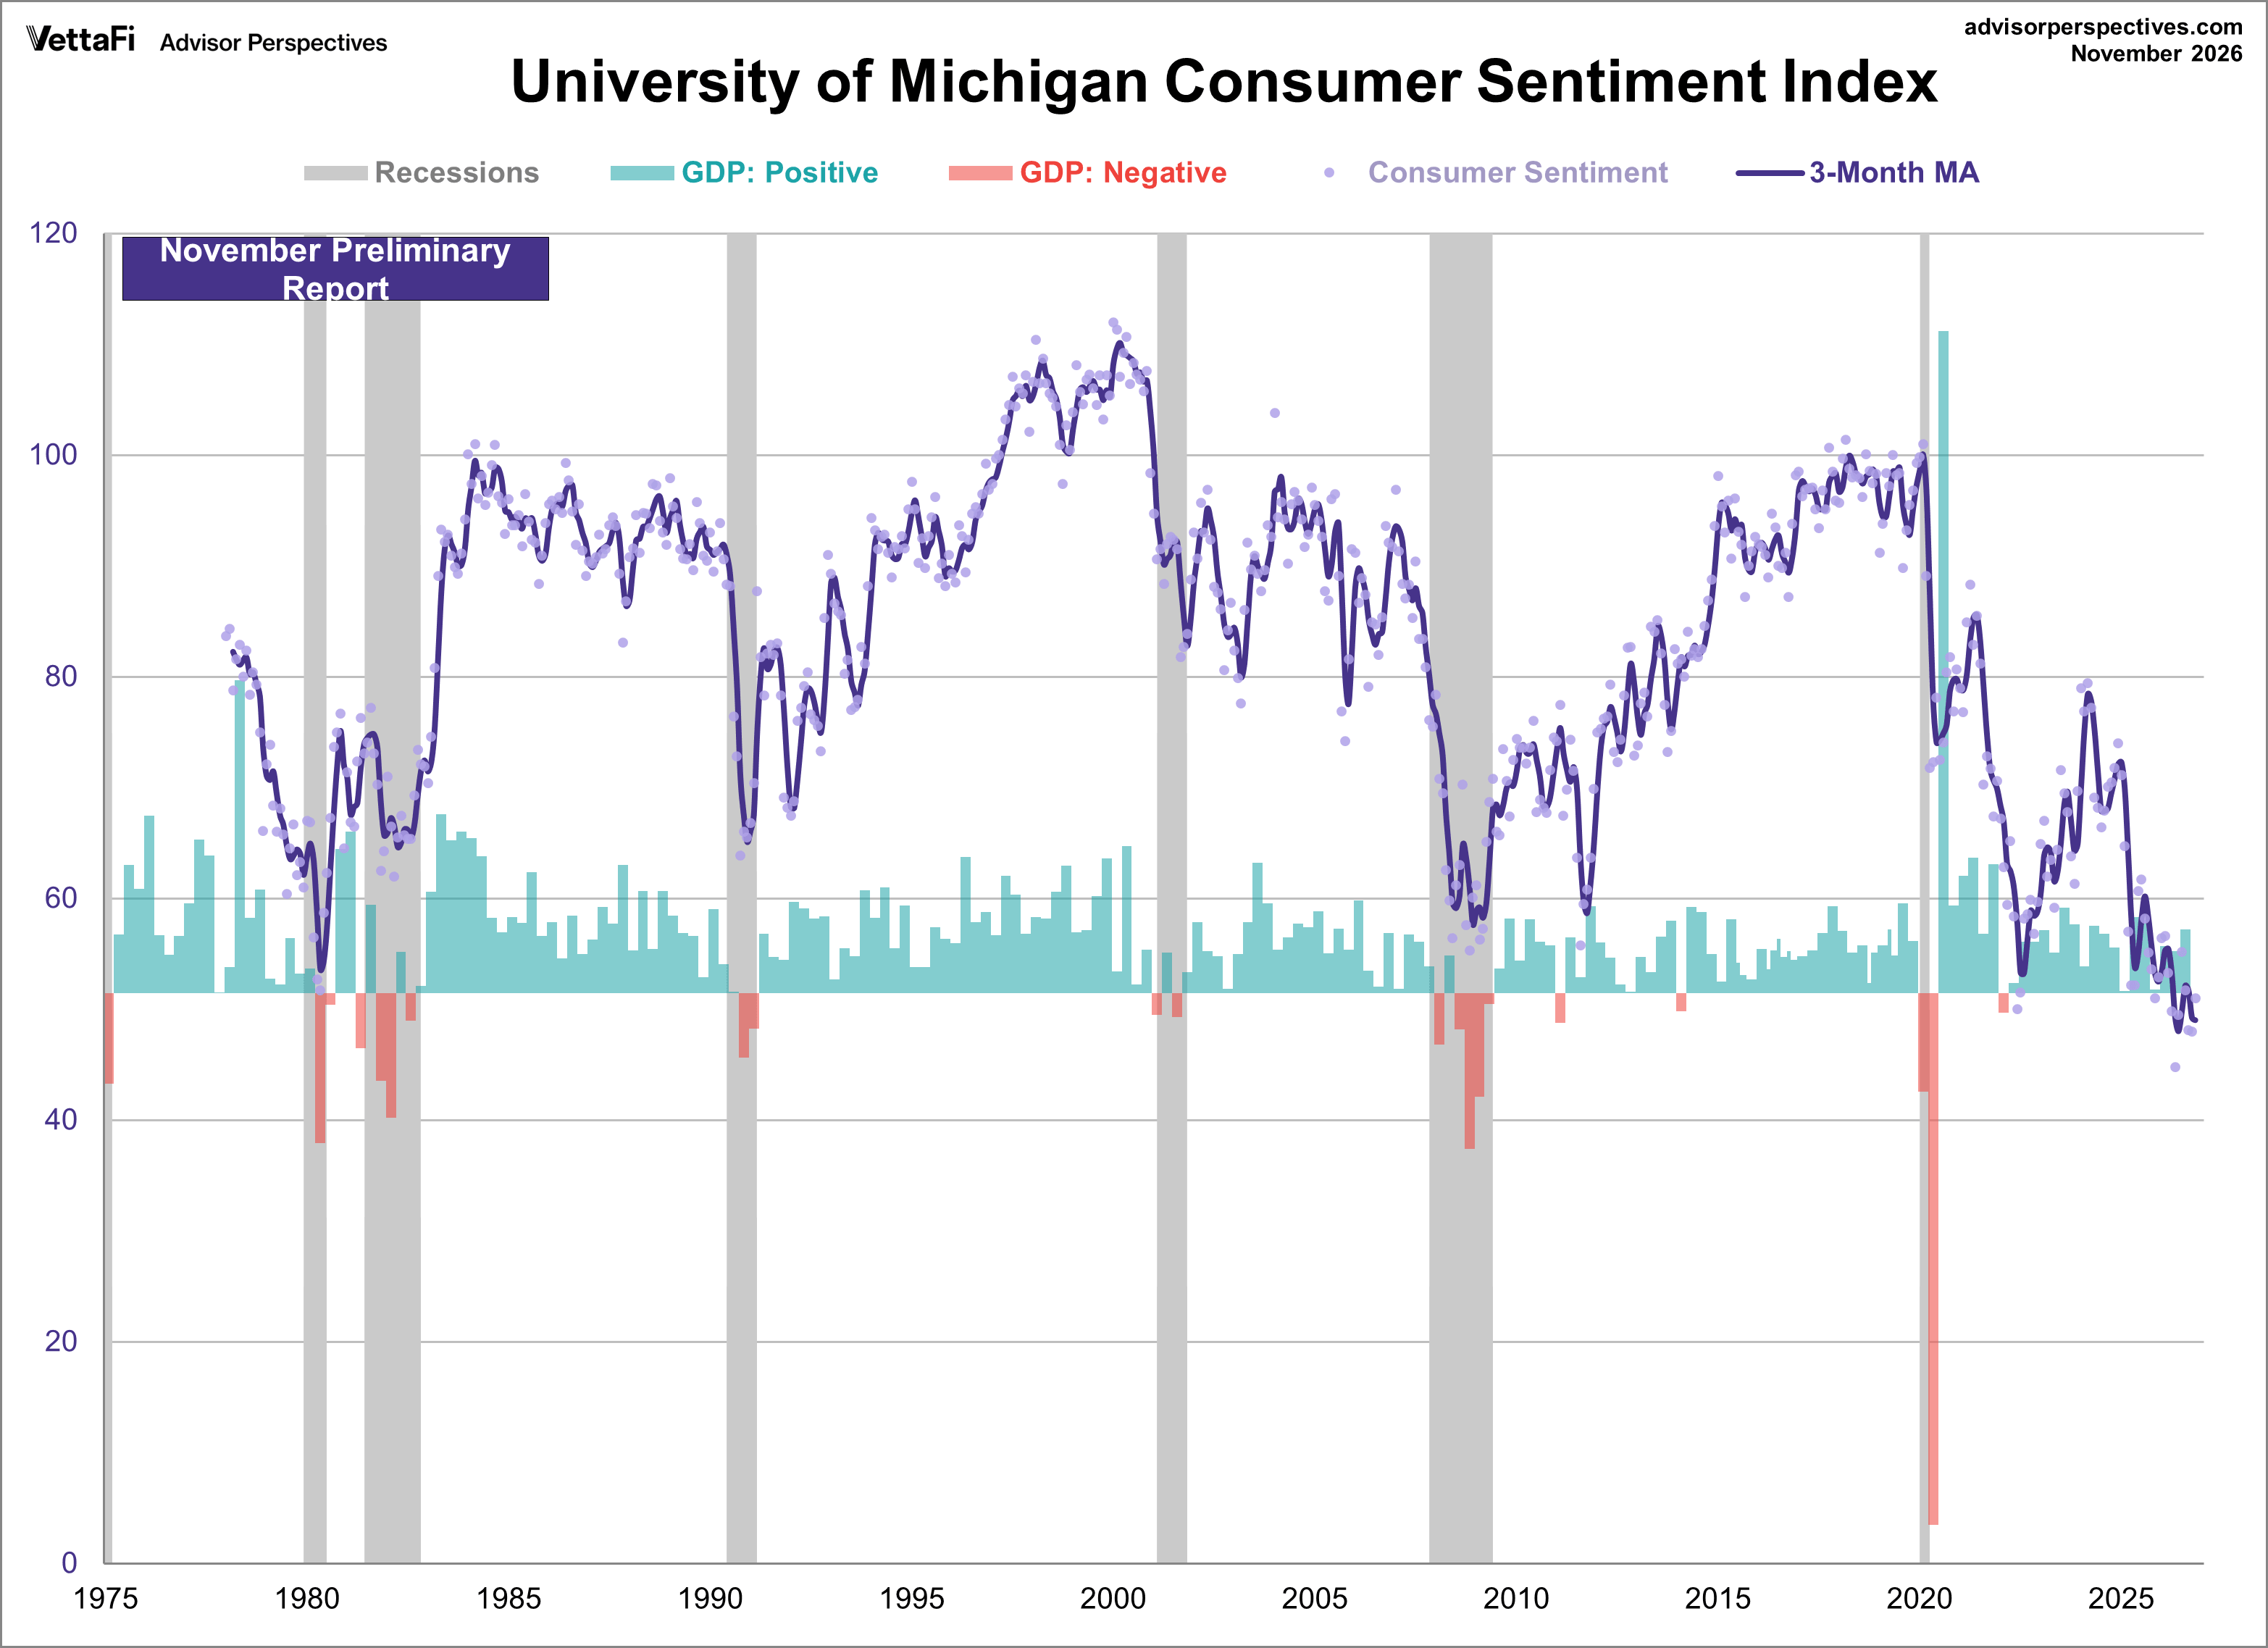
To visualize the volatility and its impact on the broader economy, the following chart includes a three-month moving average and real GDP. Historically, prolonged periods where the moving average remains at these depressed levels have closely correlated with negative GDP growth (the red bars below).
The Political and Presidential Lens of Consumer Sentiment
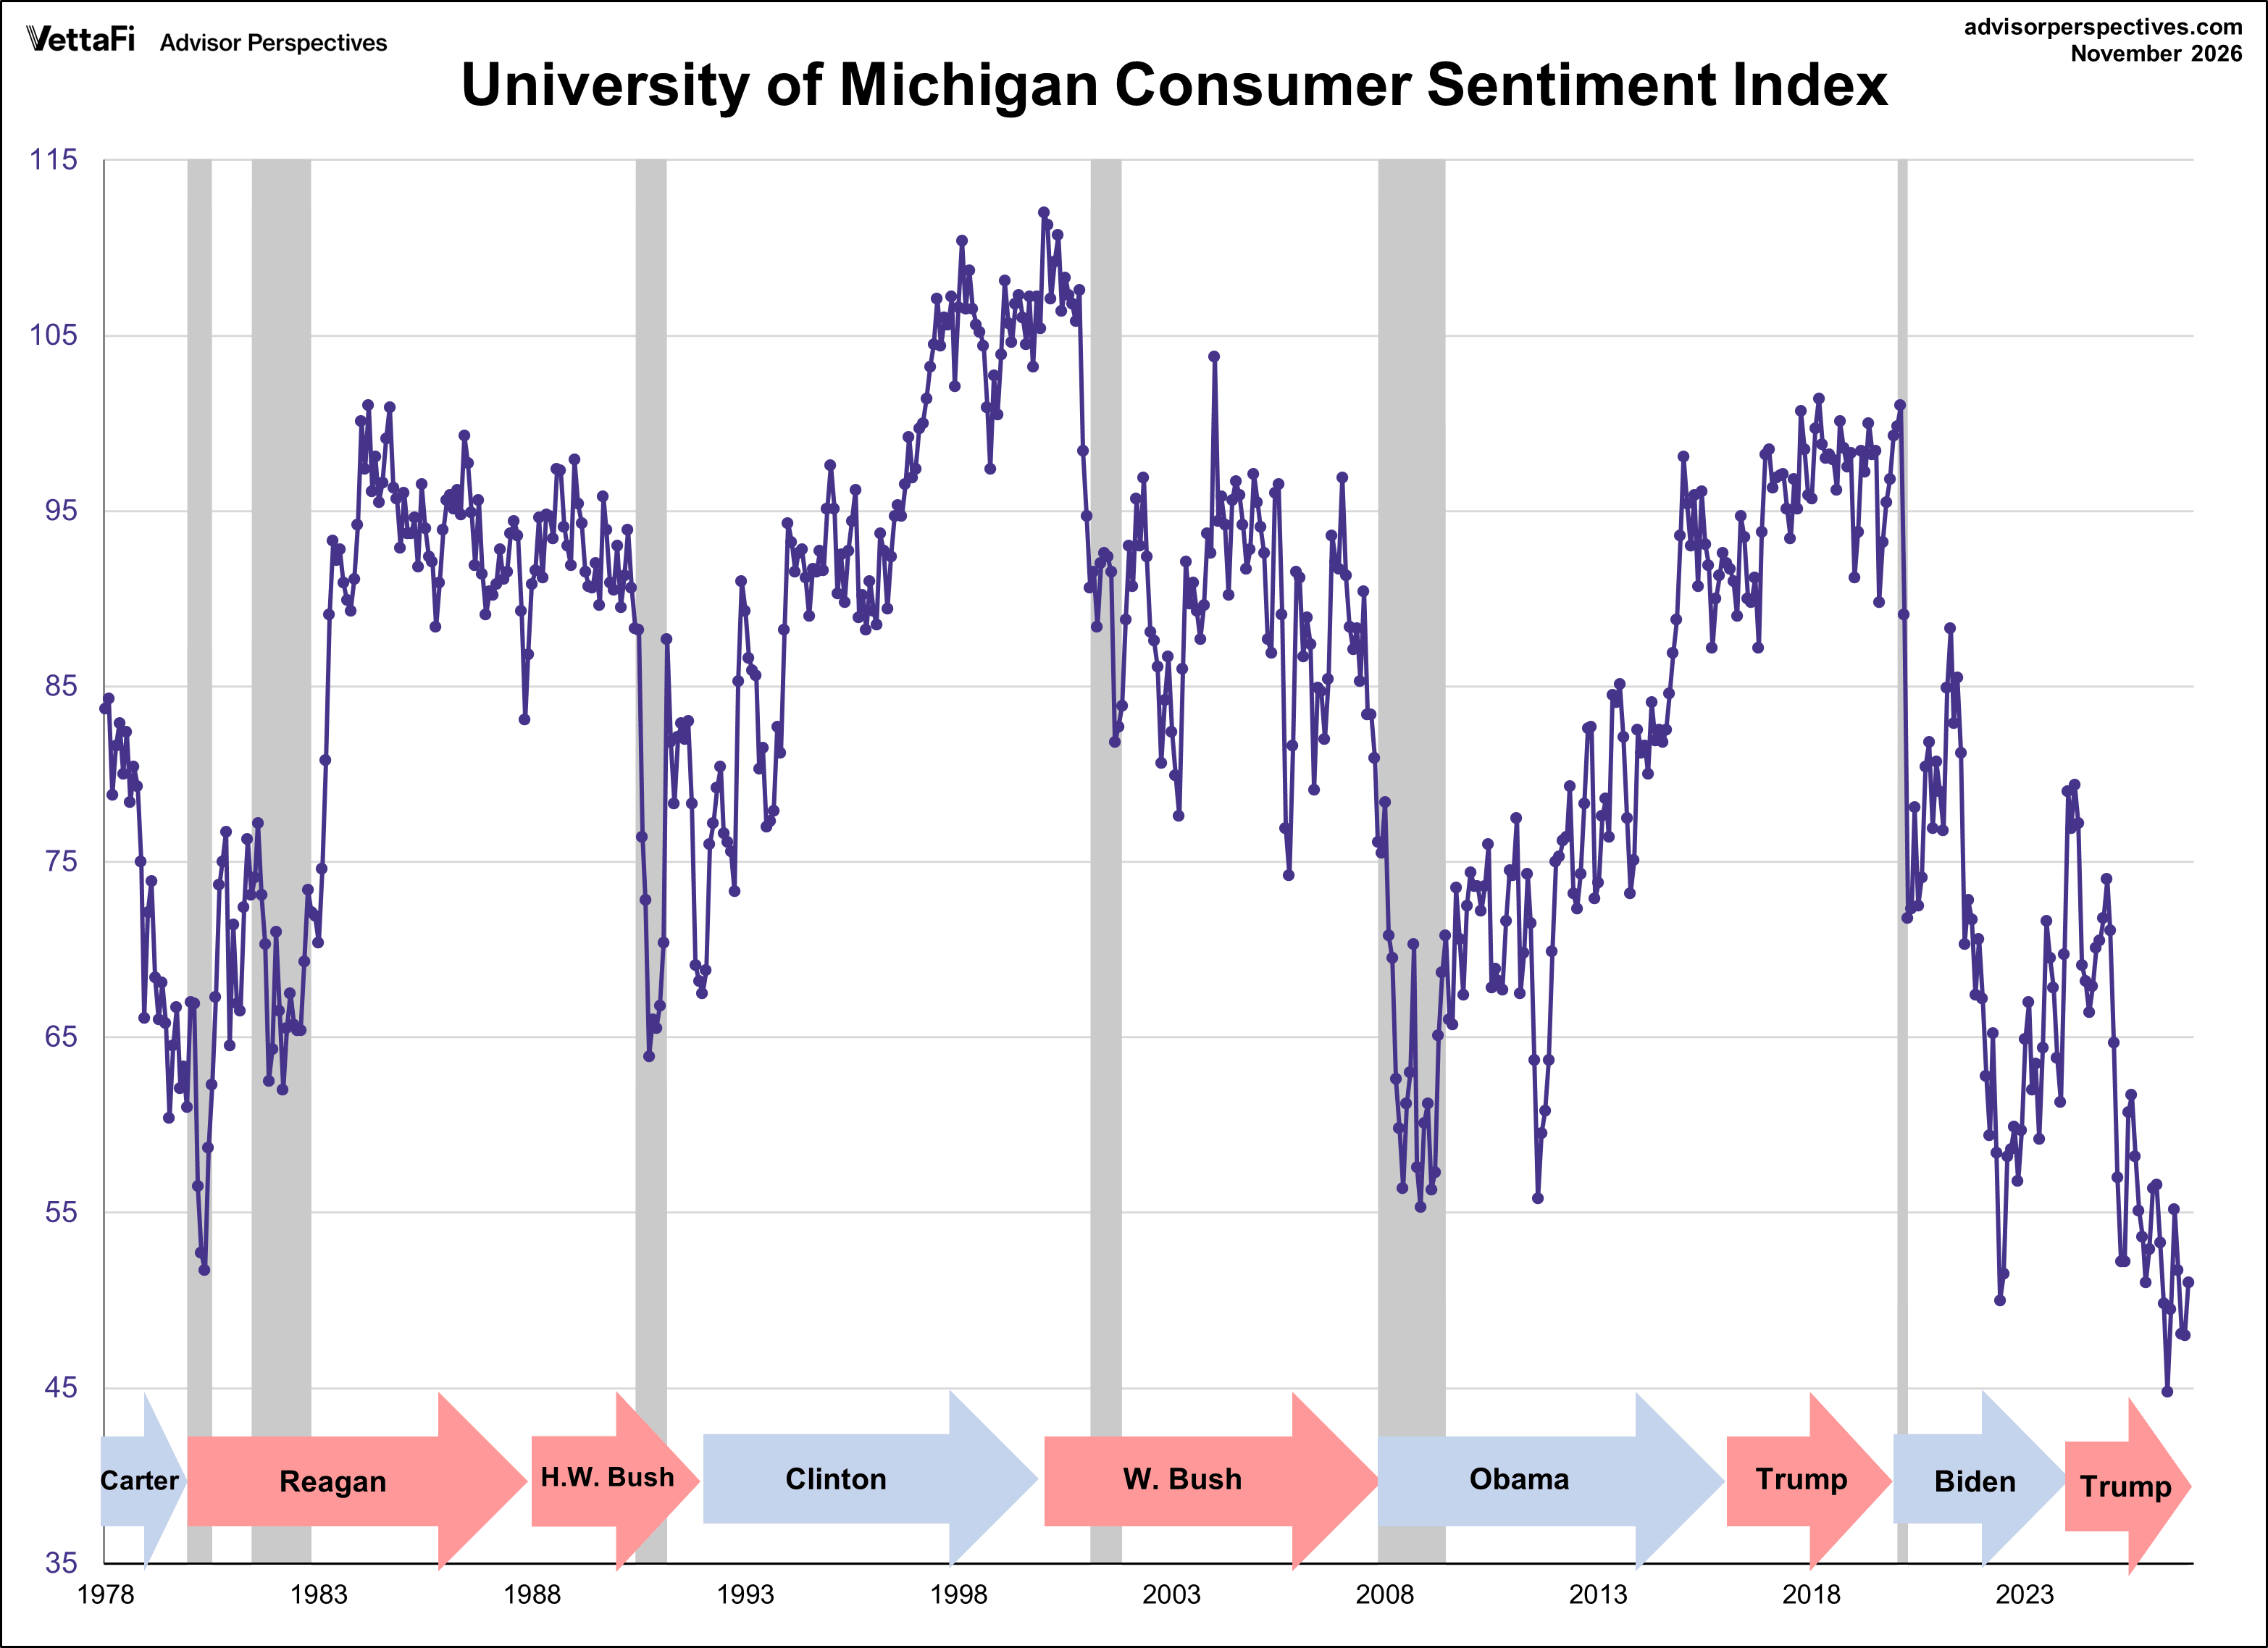
Each month, the survey results highlight sentiment within each political party. Sentiment is often viewed through a partisan lens, but the data shows that sentiment has fluctuated both positively and negatively under both Republican and Democratic administrations. As the chart below illustrates, the current "plunge" is a rare moment of bipartisan agreement, with declines seen across the political spectrum as energy costs hit every household.
University of Michigan Consumer Sentiment Index: Components
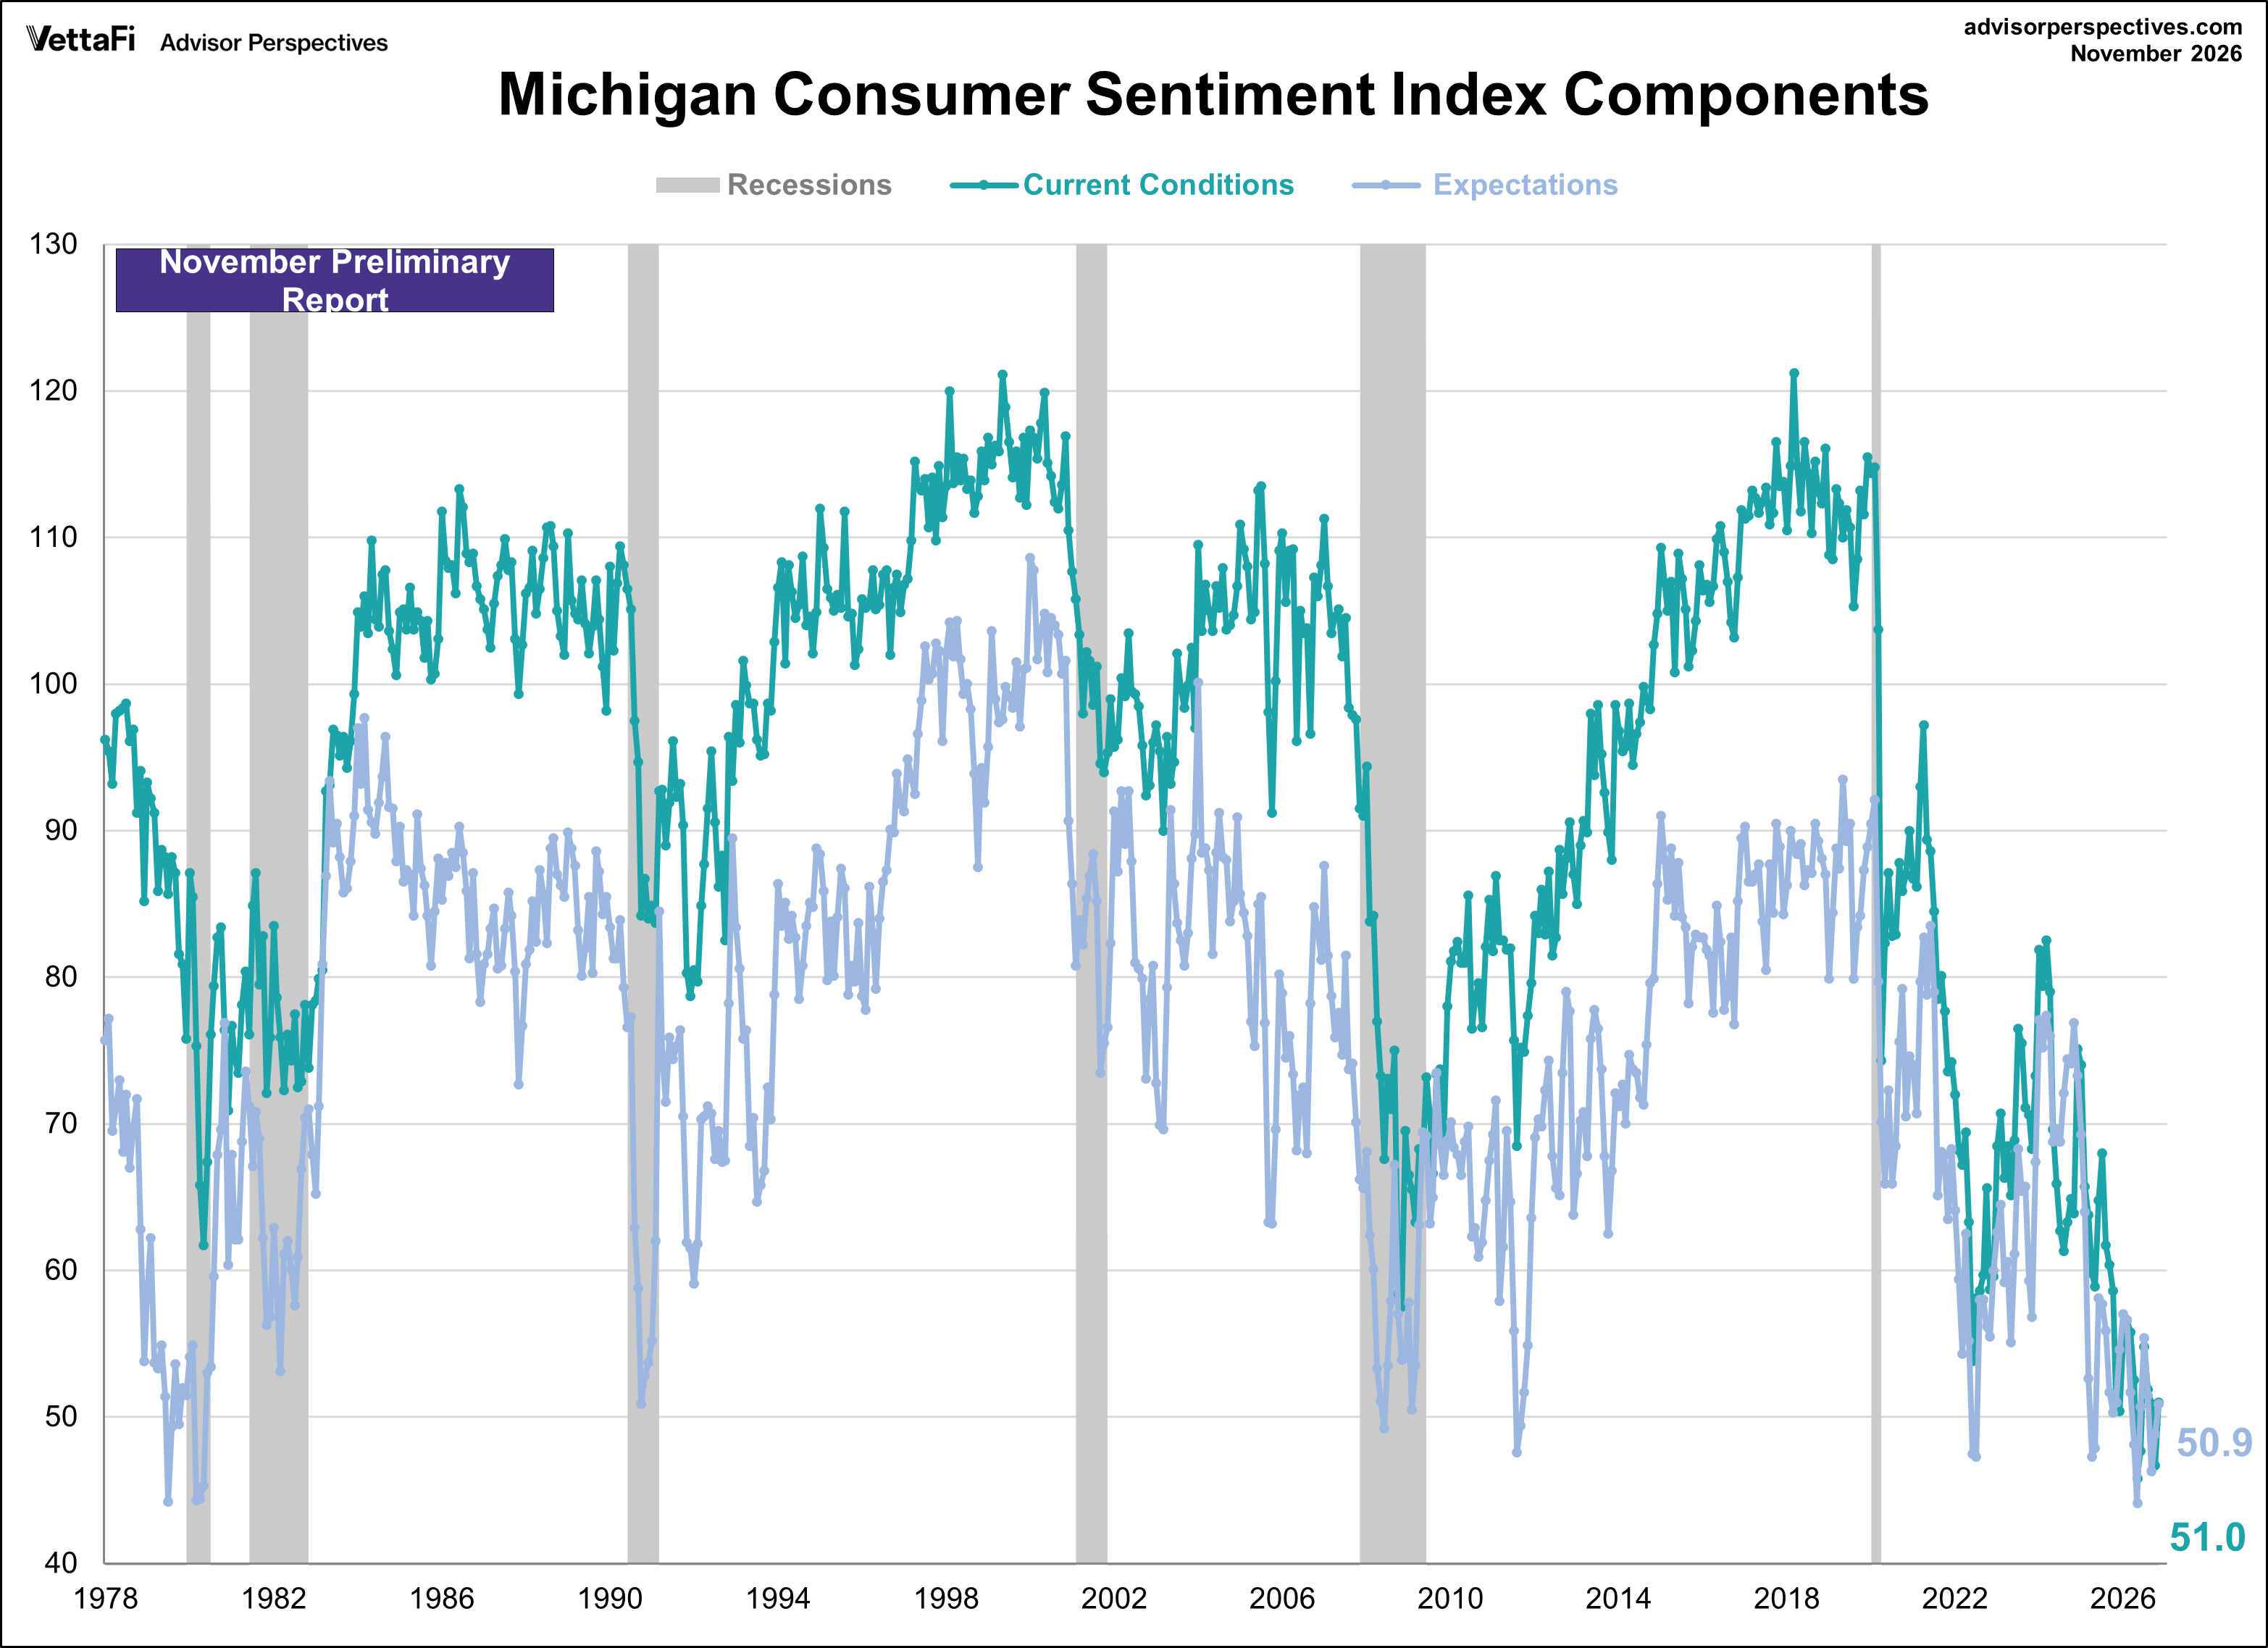
The Michigan Consumer Sentiment Index consists of two sub-indexes: the Current Economic Conditions Index (CECI) and the Consumer Expectations Index (CEI). The CECI reflects consumers' views of their current financial situation and the overall economy, while the CEI gauges their outlook for the future.
Current Economic Conditions Index (CECI)
The Current Economic Conditions Index fell to 51.0. This represents a 9.2 increase from the previous month and a 0.2% drop from a year ago. The latest reading was higher than the forecast of 48.0.
Consumer Expectations Index (CEI)
The Consumer Expectations Index fell to 50.9. This represents a 4.3% increase from the previous month and a 0.2% drop from one year ago. The latest reading was higher than the forecast of 49.5.
University of Michigan Consumer Sentiment Index: Inflation Expectations
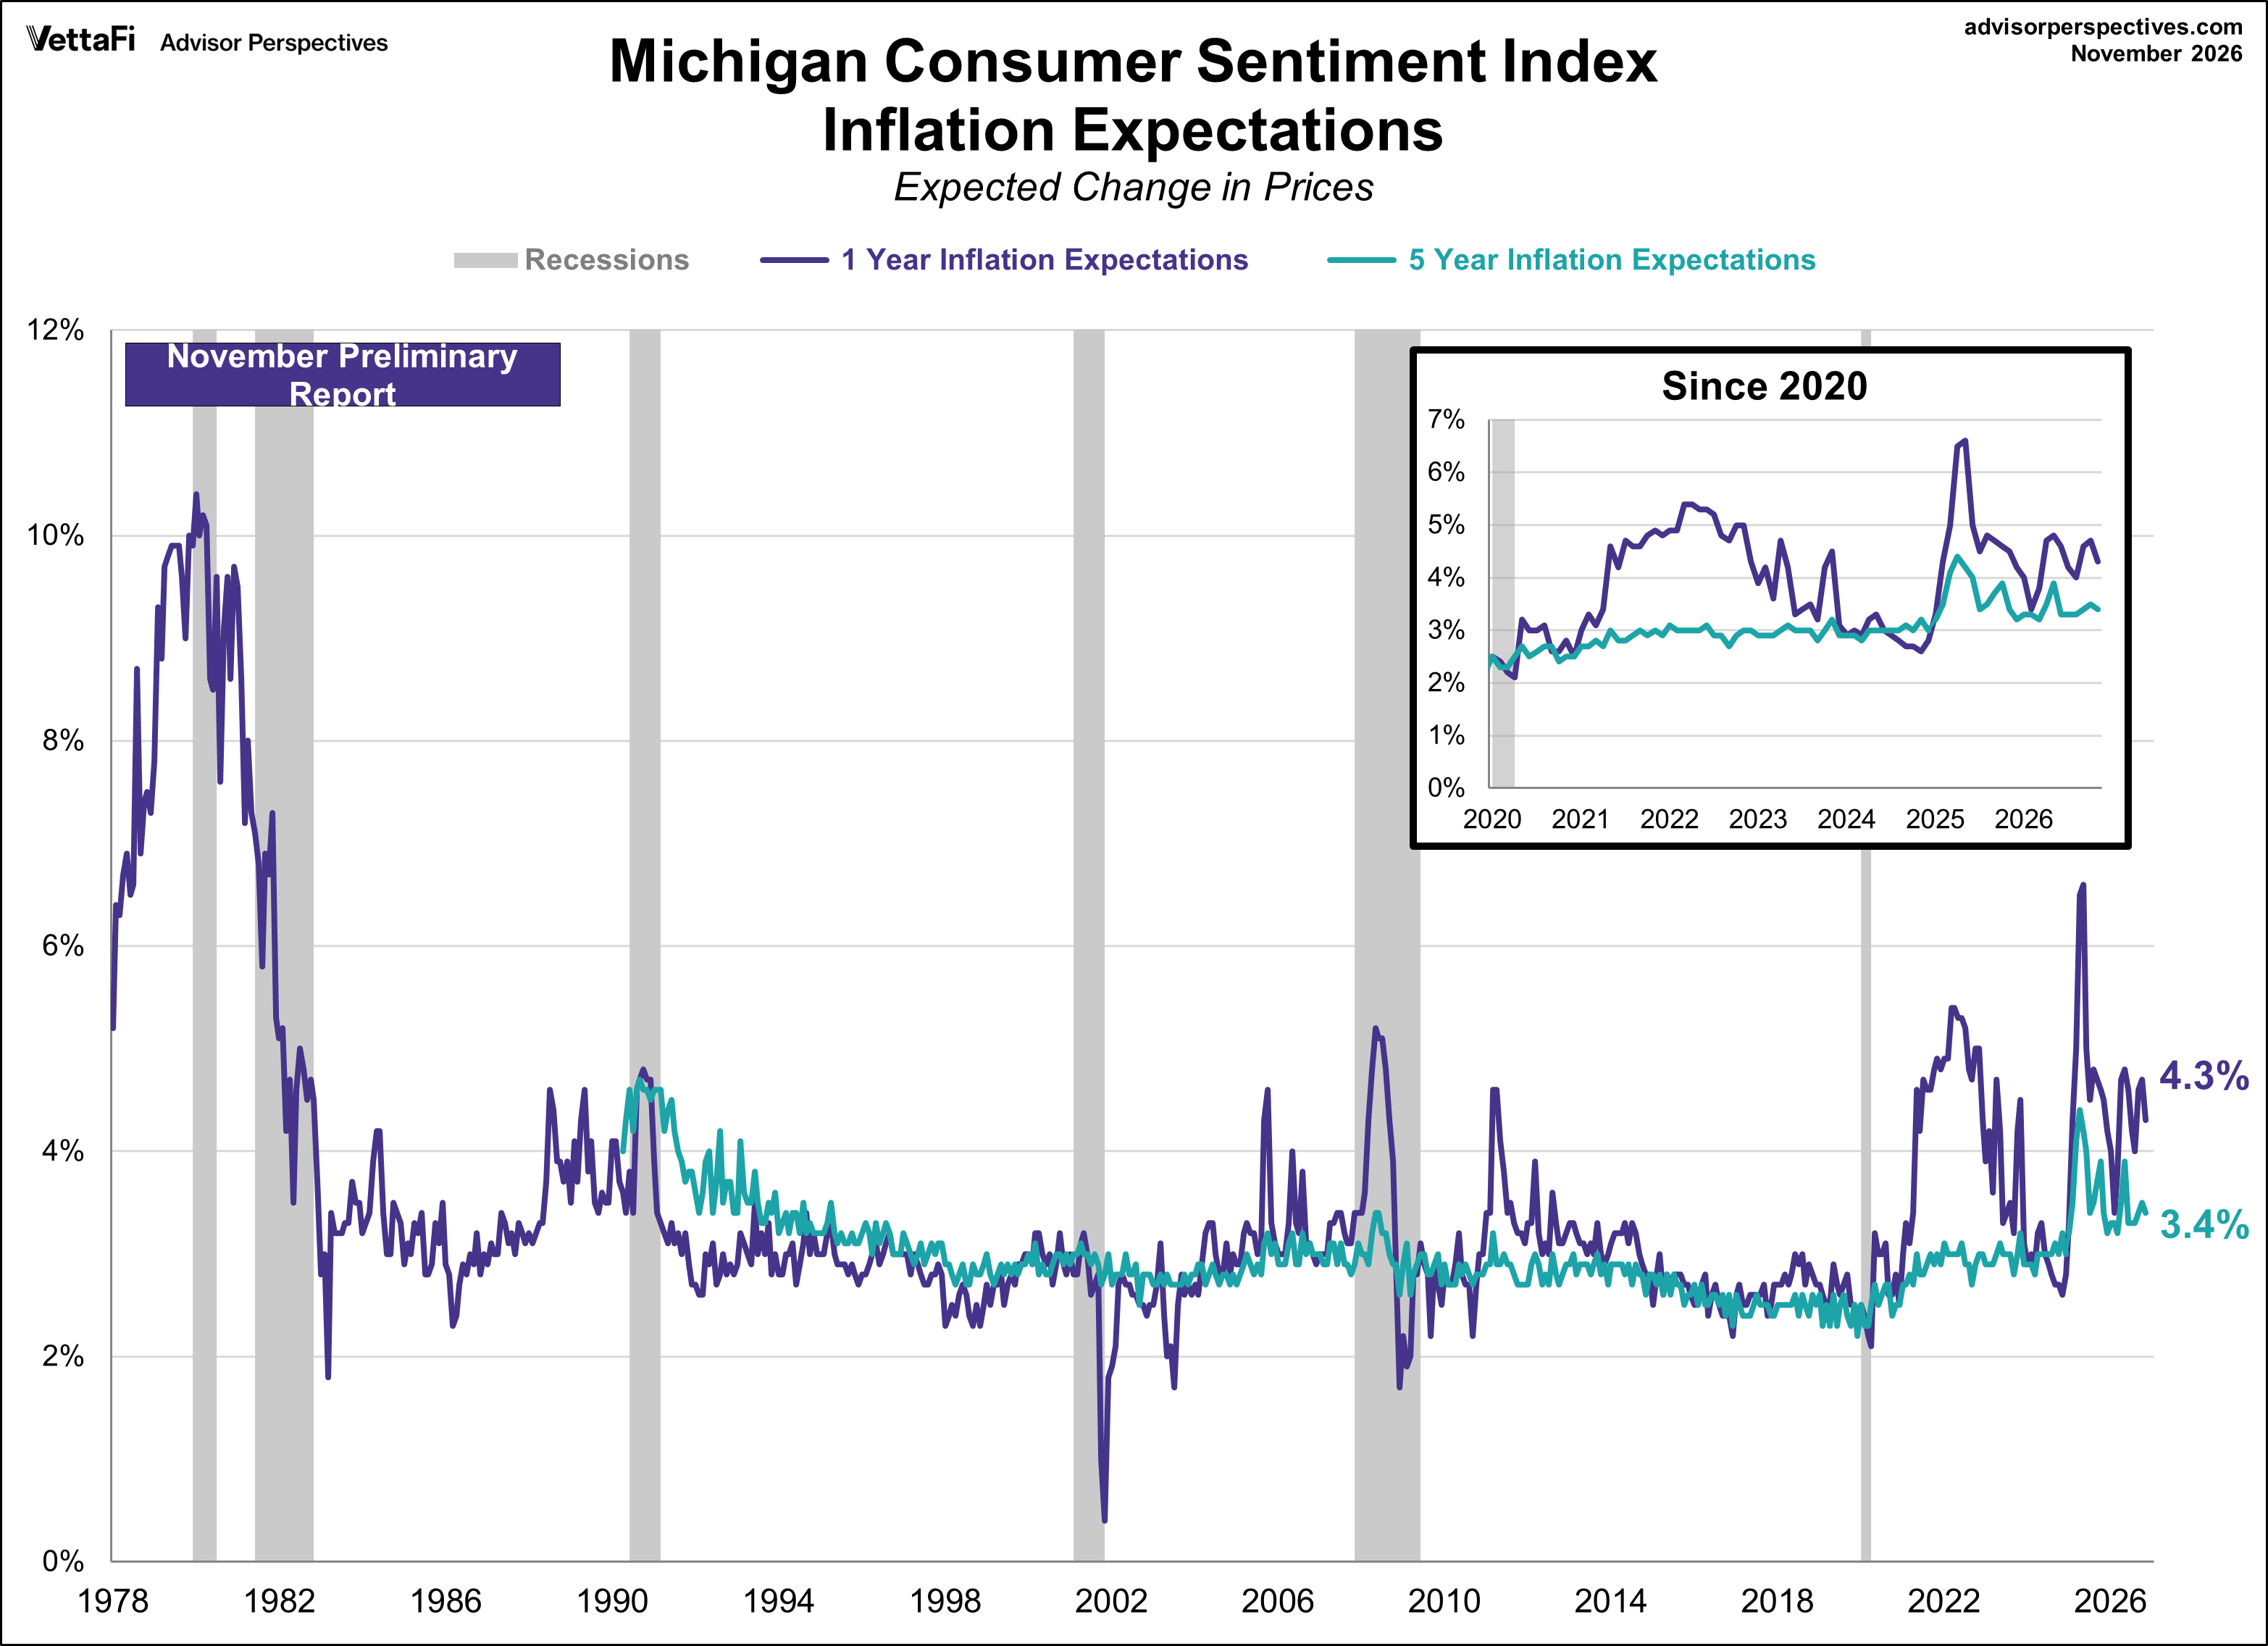
Year-ahead inflation expectations declined from 4.7% last month to 4.3% this month. Although the current reading is the lowest since August, it remains substantially above the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations inched down from 3.5% in October to 3.4%, notably higher than their 2024 range of 2.8% to 3.2%.
The next update to this report will be published on November 20th.
Other Sentiment Indicators
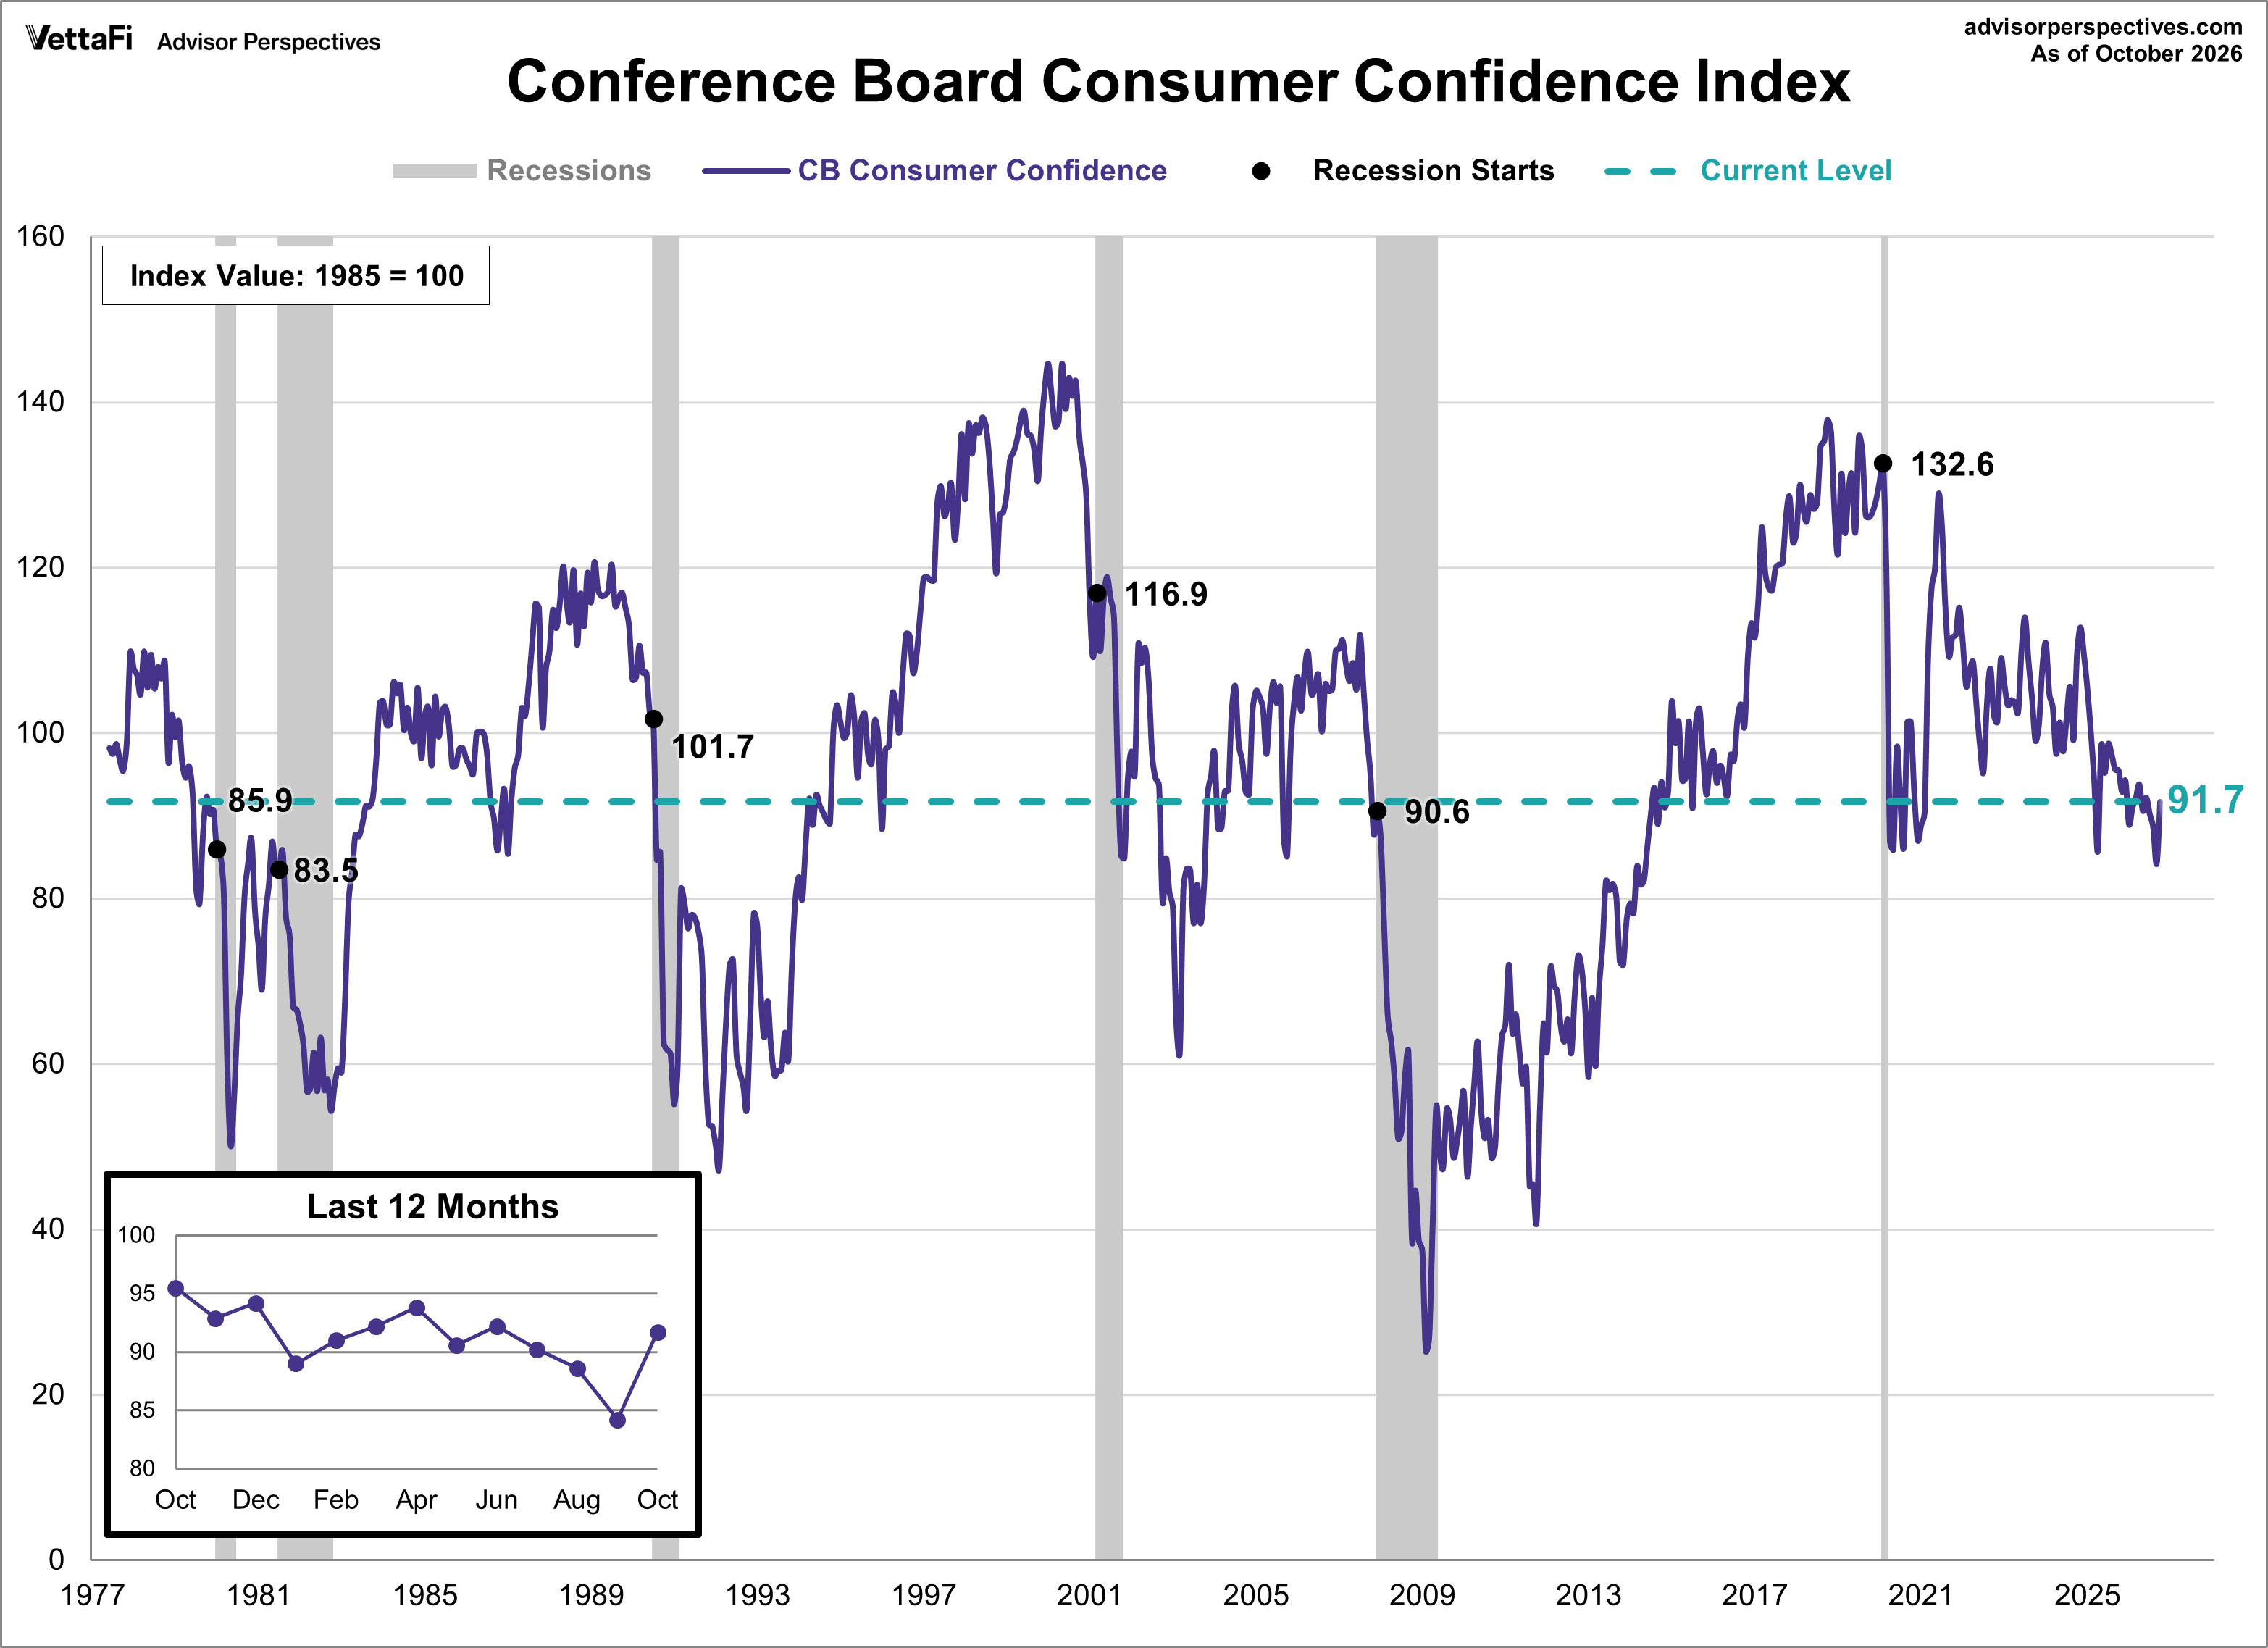
For an additional perspective on consumer attitudes, see the most recent Conference Board's Consumer Confidence Index. Both indexes gauge consumer attitudes toward the current and future strength of the economy. However, the Consumer Confidence Index is more influenced by employment and labor market conditions while the Michigan Sentiment Index is more focused on household finances and the impact of inflation.
The Conference Board index is the more volatile of the two, but the broad pattern and general trends have been remarkably similar to the Michigan index.
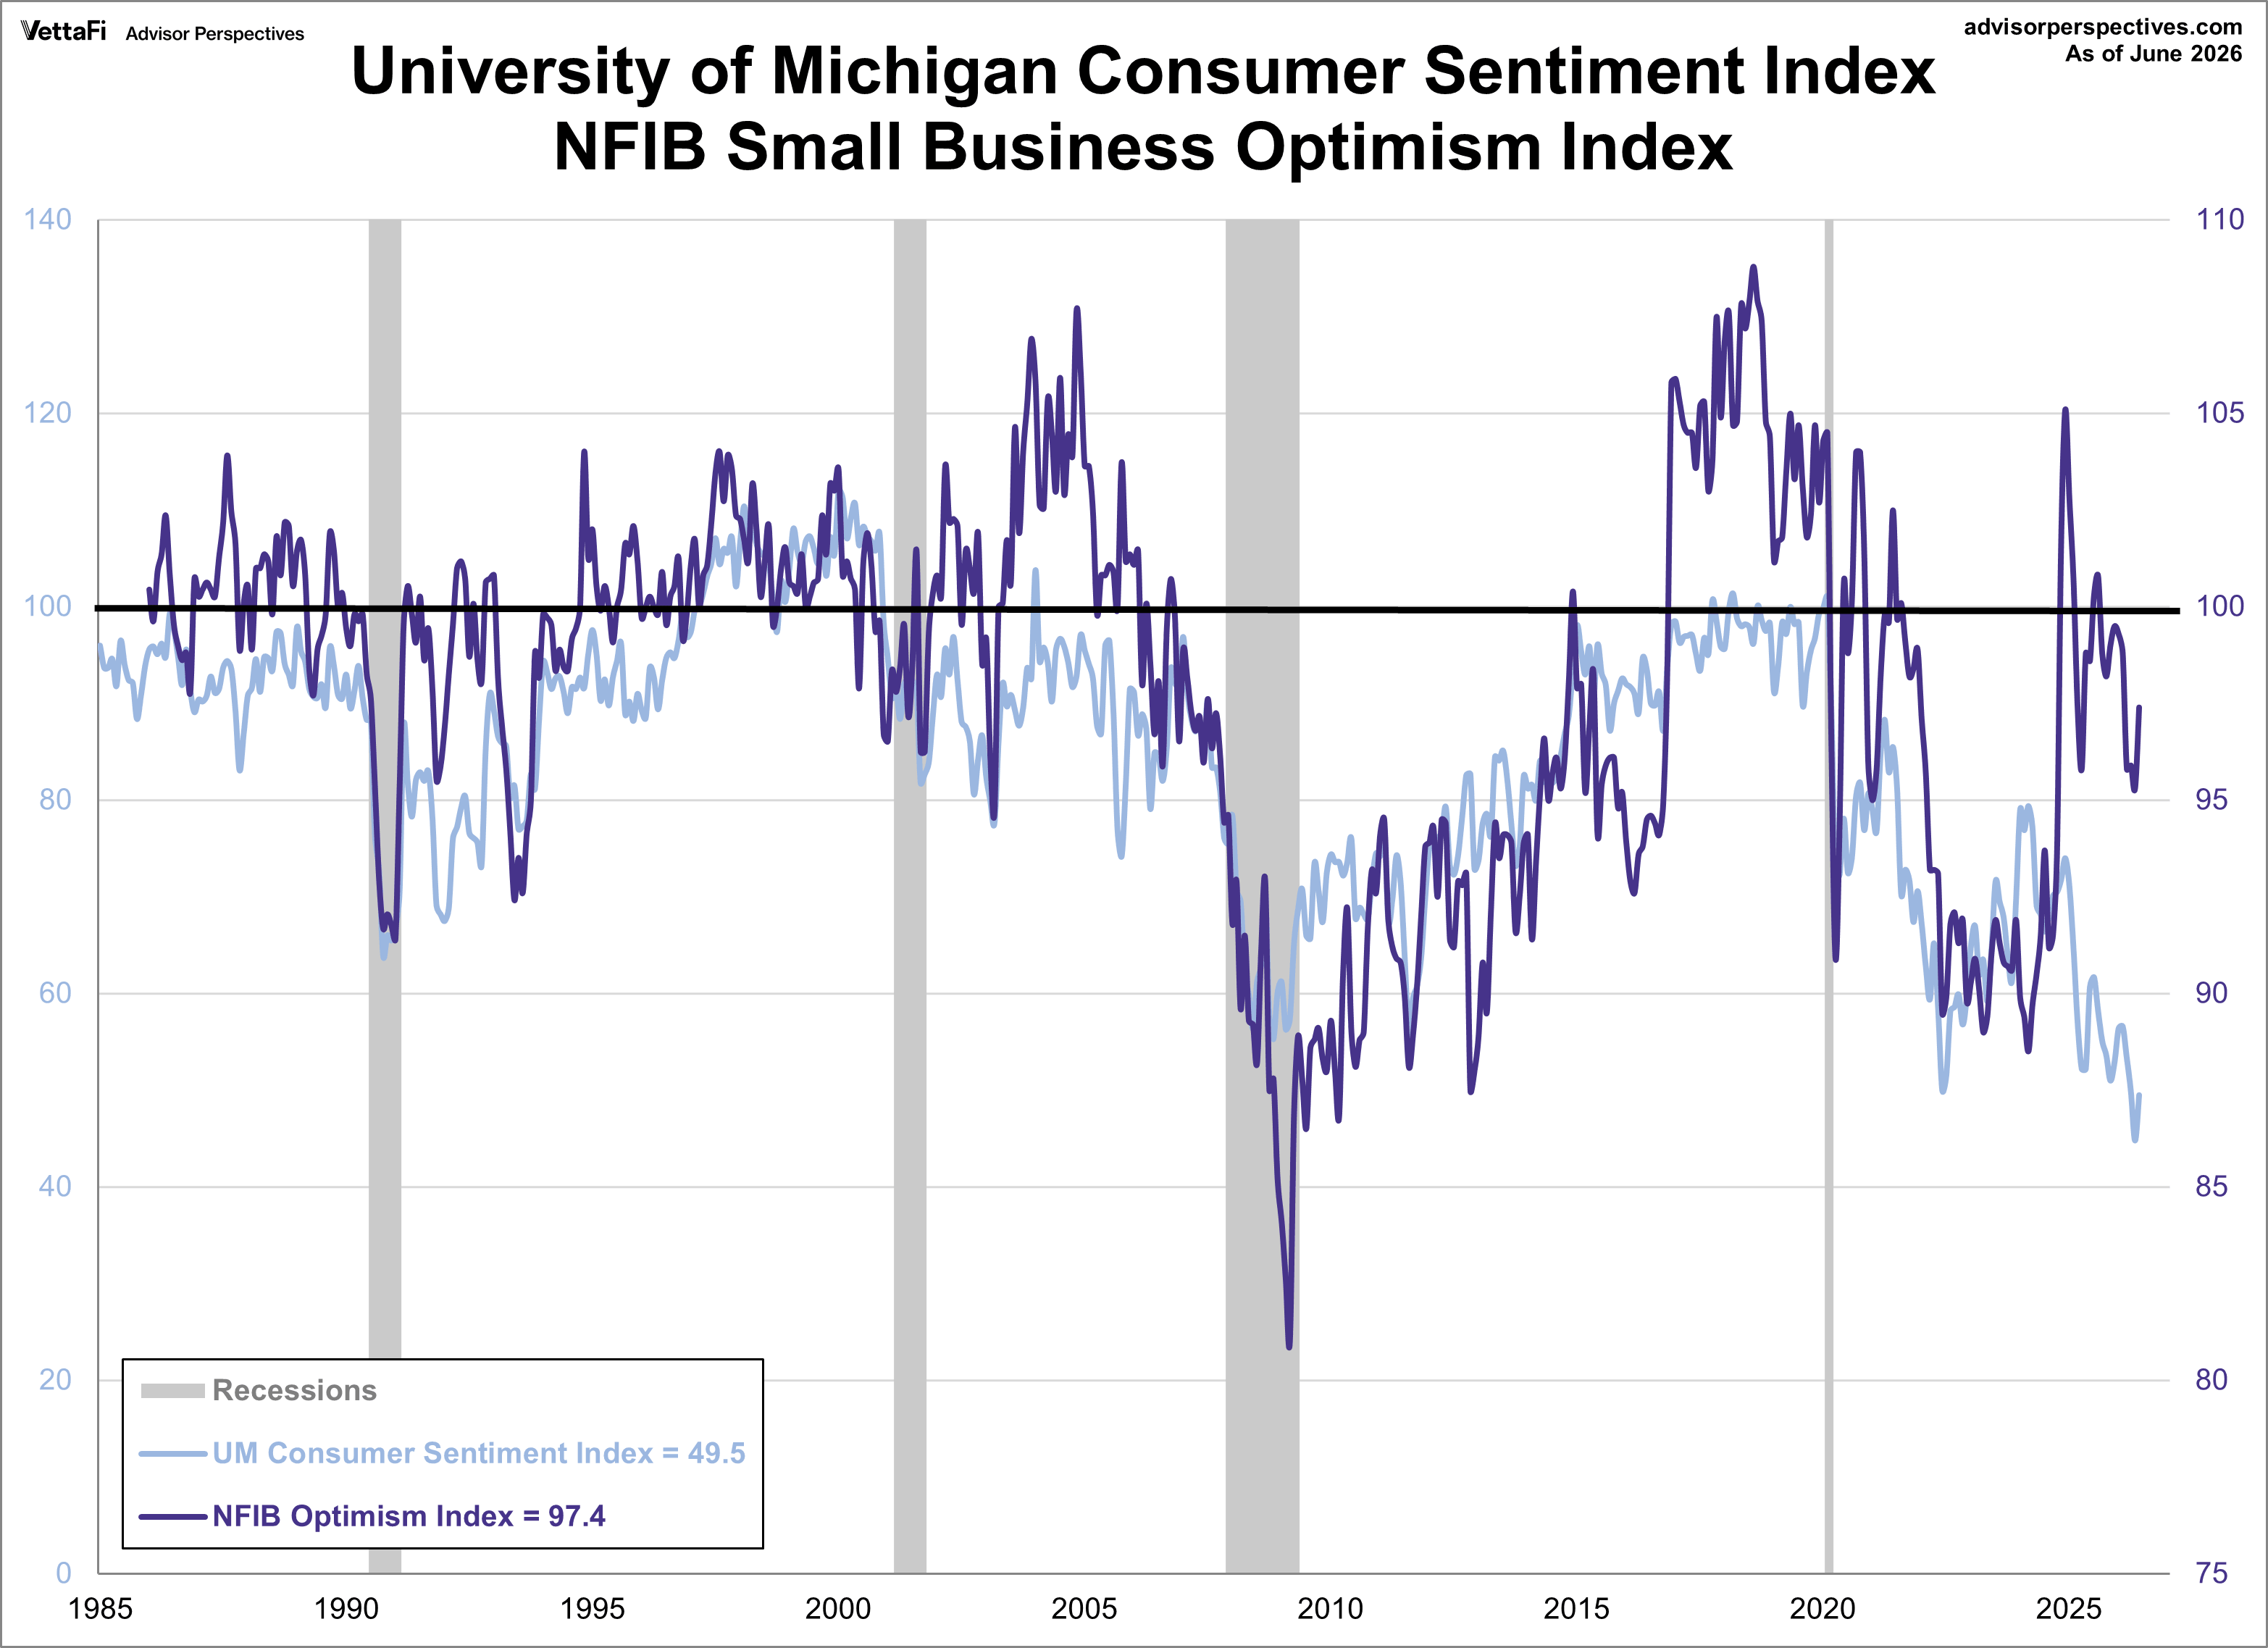
And finally, the prevailing mood of the Michigan survey is also similar to the mood of small business owners, as captured by the NFIB business optimism Index (monthly update here).
ETFs associated with sentiment include: Consumer Discretionary Select Sector SPDR Fund (XLY).
Read more updates by Jen Nash