For at least eight years, Congress has been trying and (mostly) failing to create a special set of rules for digital assets and the markets they trade on. It’s worth asking how much, if any, of that was advisable.
The latest effort, the 635-page Clarity Act, collapsed this month over an attempt to limit conflicts of interest among federal officials. The bill’s failure was a blow to the industry, which had lobbied and donated to legislators in hopes of winning a new legal framework for blockchain-based tokens and business models.
Why did crypto entrepreneurs care so much? After all, even without a consistent framework — and despite the industry’s reputation for hacking, fraud and other unsavory conduct — the global market value of spot cryptocurrencies has risen above $2.8 trillion, with trading turnover in related derivatives contracts reaching nearly $86 trillion last year.
The reason is that the industry knows that its future isn’t in the speculative coin frenzy. To go mainstream, and win broad public adoption, crypto companies need to provide familiar financial services like loans, payments and securities trading — indeed, their software can provide real advantages in that regard, including instant trade settlement and automated interest payments.

Industry leaders say that blockchain-based startups, including decentralized exchanges and brokers, can’t comply with — or compete fairly under — the long-established regulations that apply to such activities. They want legislation specific to crypto that will offer easier rules and less red tape.
See more: How Financial Advisors Add Value in Divorce Cases Involving Digital Assets
On its face, that argument sounds reasonable. Yet by now it’s clear that crypto technology isn’t so incompatible with existing banking and securities laws. Digital-asset startups have been granted banking charters, broker-dealer licenses and even (in the case of Kraken Financial) a limited-purpose Federal Reserve master account. Meanwhile, traditional banks, broker-dealers and exchanges are rewiring their own businesses to incorporate blockchain capabilities, streamlining processes such as collateral management.
Generally speaking, a bank deposit or a stock shouldn’t be regulated differently just because of the technology underlying it. Where there are gray areas, the Securities and Exchange Commission and Commodity Futures Trading Commission can work together — as indeed they already are — to provide limited exemptions or regulatory sandboxes to test innovative products and services.
Of course, regulations can be challenged in court or rescinded by future administrations. That’s fine. It’s still far from clear whether most blockchain-based businesses solve more problems than they create, while “decentralized” exchanges and brokers have a poor record in protecting clients’ assets. Does it really make sense to provide them with statutory advantages over traditional exchanges and brokers?
Better for the SEC and CFTC to continue providing limited exemptions for novel applications of the technology so that regulators can monitor businesses’ vulnerability to hacks and fraud — and see if they provide real utility. For now, Congress should focus on providing regulators with the resources they need to adequately supervise these new business models.
Many in the industry mourned the failure of the Clarity Act, but not everyone. Michael Saylor, a co-founder of Strategy Inc. and a prominent Bitcoin evangelist, called for the industry to spend the next two years (while still under a supportive administration) showing the public that it can provide useful products at lower costs. “Our safest path forward is to create products that delight customers and deploy them broadly,” he said.
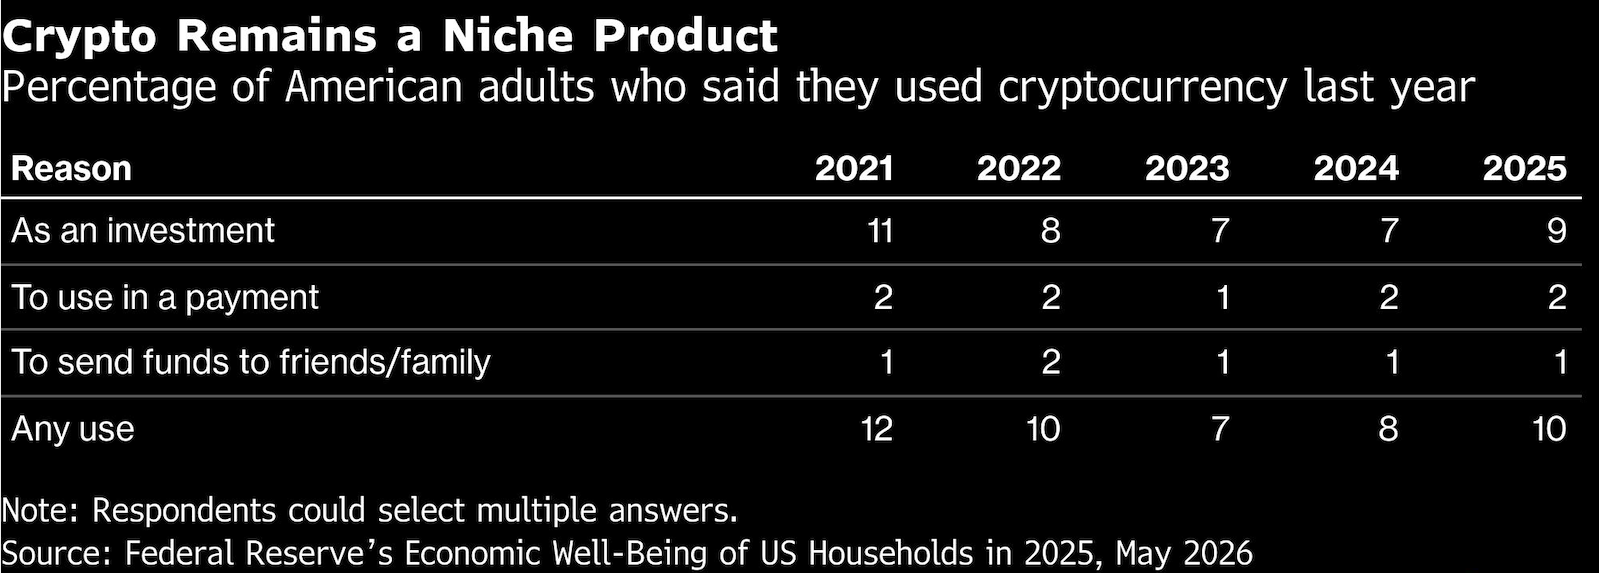
That’s the right approach. Even after close to two decades of experimentation, the crypto industry’s value to the American public remains far from obvious. On the evidence so far, there’s no need for Congress to give it special treatment.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
Read more articles by The Editors