Key Takeaways
- Global sovereign yields surged to multi-year highs last week—with the U.S. 10-year Treasury reaching 5.2%, the highest since 2007—underscoring the need for investors to reassess duration and global fixed income exposure.
- Deficit spending, persistent inflation concerns and renewed central bank tightening are pushing yields higher across the US, Japan, Germany and the UK
- Treasuries should remain a key global allocation, but rising domestic yields are giving Japanese and other foreign investors more incentive to keep funds at home
The sell-off in U.S. Treasury (UST) yields has continued pretty much in an unabated fashion In fact, multi-year high watermarks are being achieved throughout the fixed coupon maturity curve. The most widely followed development was the UST 10-year yield rising to its highest level since 2007.
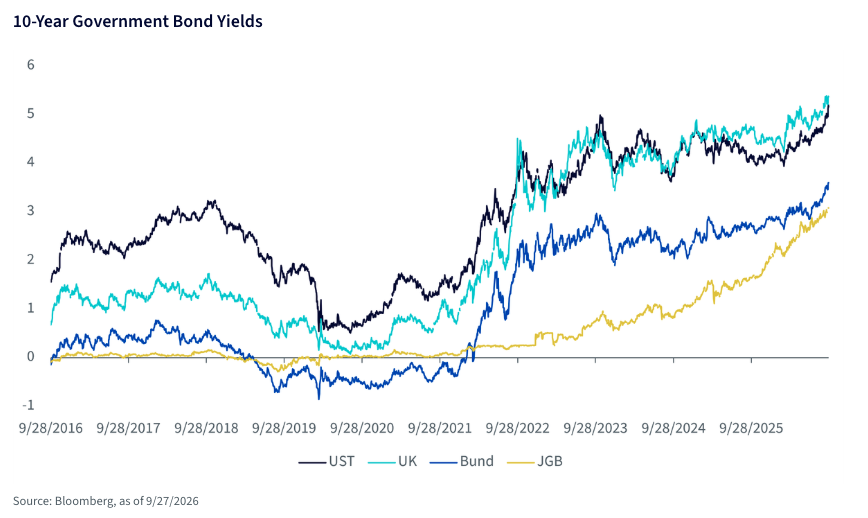
Interestingly, this soaring rate phenomenon has not been isolated to only the U.S. government bond market as sovereign debt yields have risen in a noteworthy fashion all around the key developed countries. As has been the case in the U.S., a number of foreign government bond yields have also reached multi-decade highs. Here’s some context:
- UST 10-year hit its 19-year high at 5.2% (2007)
- Japanese 10-year JGB hit its 30-year high at 3.06% (1996)
- German 10-year Bund hit its 15-year high at 3.60% (2011)
- UK 10-year Gilt hit its 18-year high at 5.36% (2008)
With these bond yields at their highest levels since the early 2000s, you may be wondering, what exactly happened to the global bond market last week? Let’s break it down.
Source: Bloomberg, as of 9/27/2026
Overall, three main factors are affecting these major global bond markets. The U.S., Europe and Japan are exposed to:
- Deficit spending
- Inflation concerns
- Central bank tightening
Simply put, deficit spending can stoke inflation and result in central bank rate hikes to counter current and/or future demand pressures. Unfortunately, these factors do not seem as if they are disappearing for quite some time, which ultimately may make those deficits even more expensive to finance.
See more: Has the Bond Market Already Done the Fed's Job?
U.S.
As we have previously written in What’s Driving Treasury Yields Higher?,there are varying factors that are impacting U.S. Treasury Yields. On top of sticky inflation, a resilient economy, the Warsh term premium and crowding out effects, the U.S. government deficit has pushed investors to demand higher yields on longer-dated Treasury bonds. Notably, two of the UST auctions last week showed weak demand, showing perhaps that current yield levels are still not overly enticing for investors.
Japan
After residing in negative territory and then being capped out under 1%, ten-year JGBs have now surpassed the 3% threshold, due to Bank of Japan (BOJ) tightening and dialed-up fiscal spending plans. Japan’s position is of particular importance because it’s historically been one of the world’s largest government debt buyers. However, given rising currency hedging costs and relatively more attractive yields in their own domestic bond market, Japanese life insurers and pension funds may now see more incentive to keep their funds at home.
Germany
Rising energy costs from the Middle East conflict have ignited inflation concerns, driving the European Central Bank (ECB) into rate-hike mode. As a result, Bund yields hit their highest levels since 2011. As we have witnessed here in the U.S., the bund market had not been anticipating ECB rate hikes at all. Now traders are projecting several hikes through 2027.
UK
The 10-year Gilt yield moved closer to multi-year highs, and the market is expecting a 25-basis point rate hike from the Bank of England in November. On top of that, their debt levels are rising close to 95% of GDP, which is triple what it was before the Global Financial Crisis. They are also carrying one of their heaviest debt burdens in more than half a century.
Conclusion
Some market commentary has questioned whether the UST market remains a key source for global investors. The answer is yes. However, with the rise in other sovereign debt market yields, Treasuries do have some potential competition. Rather than foreign investors becoming active sellers of Treasuries, we see the most likely scenario being one of continued foreign buying, but perhaps at a somewhat lesser rate.
Kevin Flanagan, Head of Investment and Fixed Income Strategy
Maggie Lucier, Senior Associate, Investment Strategy
Investors should carefully consider the investment objectives, risks, charges and expenses of the Funds before investing. U.S. investors only: To obtain a prospectus containing this and other important information, please call 866.909.9473, or click here to view or download a prospectus online. Read the prospectus carefully before you invest. There are risks involved with investing, including the possible loss of principal. Past performance does not guarantee future results.
You cannot invest directly in an index.
Foreign investing involves currency, political and economic risk. Funds focusing on a single country, sector and/or funds that emphasize investments in smaller companies may experience greater price volatility. Investments in emerging markets, real estate, currency, fixed income and alternative investments include additional risks. Due to the investment strategy of certain Funds, they may make higher capital gain distributions than other ETFs. Please see prospectus for discussion of risks.
WisdomTree Funds are distributed by Foreside Fund Services, LLC, in the U.S.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© WisdomTree, Inc.
More Economic Insights Topics >