LPL Research analyzes S&P 500 margin expansion, assessing how much is structural versus cyclical and what that means for future earnings forecasts.
It’s really starting to feel like autumn now. August PPI, CPI, and Retail Sales are in the books, the September FOMC meeting is out of the way, and we can now look forward to Jobs Week on Wall Street. Football is in full swing, and earnings season begins before you know it, with Pepsi (PEP) posting results on Thursday, October 8, followed the next morning by Delta (DAL).
Global growth remains resilient but uneven. In the United States, expansion is supported by private demand, a stable labor market and AI investment, while Europe and Japan continue to show surprising strength despite ongoing risks.
Artificial intelligence (AI) technologies are developing faster than investors anticipated just a few years ago, fueling a popular narrative that AI will trigger widespread job cuts. Yet there’s little evidence to back this view. Instead, we find that AI is changing hiring patterns, altering skill requirements and shifting the mix of work performed within firms.
While the AI trade absorbs nearly all available investor attention, owning energy covers our absolute risk while creating the risk budget to cover the AI relative risk more effectively.
Major US equity indices finished the week mixed. The NASDAQ gained 0.7 per cent while the Dow and S&P 500 slipped. The divergence reflected a tug-of-war between fears of slower AI development early in the week and a rebound in AI-linked shares by Friday.
For many advisory firms, portfolio management creates a practical tension. Standardized models can simplify implementation and support scale, yet they may not reflect a firm's investment philosophy, tax realities, legacy holdings or preferred managers. Building every portfolio internally preserves control, but it also demands time, systems and ongoing investment oversight.
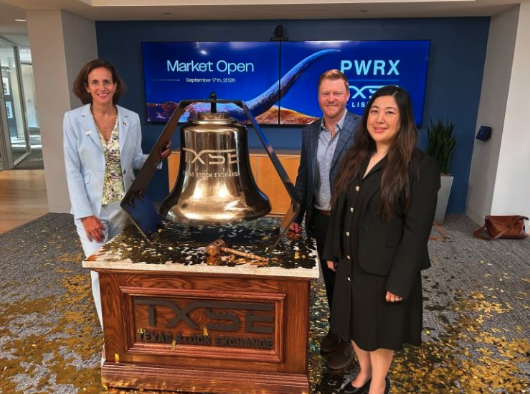
The Texas Stock Exchange (TXSE) is more than a regional milestone — it is a shift in competition among U.S. capital markets. After months of anticipation, the TXSE reached a major landmark last week as Texas Capital’s TXS and OILT ETFs became its first primary listings, followed a day later by PWRX as the first new ETF to launch on the exchange.
Markets have dealt with serious whiplash from the Federal Reserve’s dramatic policy pivot this year. In just six months, the Fed funds futures market went from pricing in two rate cuts totaling 50 basis points to now pricing in two rate hikes in 2026.
Creating an estate plan is an important step, but it is only one piece of your financial life. If your estate documents, investment strategy, retirement plan, tax strategy, and beneficiary designations are not working together, even a well-crafted estate plan may not achieve the outcome you intended. Coordinating these elements may help support your wealth is transferred efficiently, your wishes are honored, and unnecessary complications are reduced.
Federal Reserve (Fed) chair Kevin Warsh has established his hawkish credentials. Franklin Templeton CIO, Sonal Desai sees scope for further yield curve steepening and a range of selective opportunities, based on capturing income and focusing on quality rather than counting on lower rates or tighter spreads.
It wasn’t that long ago that Kevin Warsh’s leading critics were saying his biggest problem was that he wasn’t “independent” from President Trump, that if Trump told him to “jump” he’d ask “how high?” Or, in this particular situation, “how low should interest rates go?”
The Federal Reserve delivered the 25-basis-point increase the markets had largely anticipated, but the overall message was somewhat more hawkish than expected. The decision was unanimous, and the new dot plot points to another rate increase this year. Four participants apparently see the possibility of raising rates at each remaining meeting, so there is clearly a meaningful hawkish contingent on the FOMC.
The week began with calls for a potential slowdown in AI spending amid growing safety concerns and included a midweek Fed rate hike for the first time since 2023. The S&P 500 finished slightly lower for the second week in a row despite continuing signs that economic growth is strong. Shorter-term bond yields pushed higher as investors priced in the potential for additional rate hikes, both in the U.S. and abroad.
Every runner has a natural pace: the speed that we maintain under optimal conditions like flat terrain, cool temperatures and a good night of sleep. Runners can train to speed up to meet a target time, or slow down for endurance.
Some economists and market participants view inflation as one of the most important economic indicators. Market participants spend a lot of time worrying about a lot of things, but inflation is pretty close to the top of the list most of the time.
Dividend growth is back, and it’s fair to say that outperformance among dividend growth stocks may simply be overdue amid a shift in U.S. equity market leadership beyond a small group of mega-cap technology companies.
Share buybacks are when a company purchases its own shares, reducing the total number of shares on the market. Oftentimes, these buybacks occur on the open market, but companies may also look to buy shares from existing shareholders as well.
Goldman Sachs Asset Management launched two new ETFs Monday, expanding exposure to emerging and international equities. The ETF duo includes the Goldman Sachs Data Enhanced Emerging Markets Equity ETF (GEMQ) and the Goldman Sachs Data Enhanced International Equity ETF (GIEQ). That pair joins an ETF landscape in which those segments are seeing growing interest.
This has been an incredible year in that Wall Street has spent all of it raising its earnings estimates, and the second-quarter season only accelerated the trend. Analysts began the year expecting S&P 500 earnings to grow about 15%.
Early this week, I was in Los Angeles at the All-In Summit along with about 4,000 others, including tech investors, money managers and entrepreneurs. The ticket wasn’t cheap, but it was well worth it.
Chris Galipeau and Taylor Topousis discuss high-conviction insights that go beyond media headlines.
In August, a flurry of ETF-related deals were announced and expected to close by early 2027. Goldman Sachs is buying NEOS Investments. T. Rowe Price plans to add F/M Investments. Victory Capital is acquiring First Eagle.
A popular narrative for the rise in bond yields over the past few months is that the debt-funded AI capital expenditure cycle is crowding out the Treasury market. The crowding-out argument can appear compelling: AI companies are expected to continue to issue unprecedented amounts of debt at a time when Treasury supply remains elevated. Because both ultimately draw from the same pool of investor capital, yields must rise to clear the market.
As summer officially gives way to fall on September 22, it's not just the weather that's changing. The global monetary policy landscape is shifting as well. After spending much of the past two years focused on supporting growth, central banks have increasingly turned their attention back to inflation, especially with oil prices climbing back above $100 per barrel.
I typically avoid business books when I am on vacation. But I made an exception during our sojourn last month for Andrew Ross Sorkin’s 1929. Nearly a century after the Great Crash, that era is still being studied for lessons that might be relevant in the current day. The potential for financial instability is ever-present.
GMO has posted a new 7-Year asset class forecast for August 31, 2026.
This week's Federal Open Market Committee (FOMC) decision was largely in line with expectations. While many market participants and Federal Reserve (Fed) members anticipated another rate increase later this year, we remained in the camp that viewed the move as likely the last increase before the Fed adopted a wait-and-see approach, allowing geopolitical developments to stabilize and recent inflationary base effects related to the US-Iran war to fade.
The Federal Reserve increased rates by 25 basis points this week, a remarkable turnaround with major implications for portfolios of all kinds; one underexamined impacted area may be annuities.
The K-shaped economy is real, and it is old. What changed isn’t the shape of the economy; it’s just that the media found a narrative that gets lots of clicks and views, and we let headlines do our thinking for us.
Throughout this Indexing Redefined series, we explored how traditional market-capitalization indexing ties portfolio weights directly to stock prices, creating hidden concentration risks. Furthermore, we discussed how fundamental indexing offers a disciplined alternative by weighting companies according to their real-world economic footprint. In this final installment, we address the dilemma investors face in highly concentrated equity markets.
This month, our experts discuss how Federal Reserve tightening has historically affected the markets; whether European stocks might be worth a second look; and the news from the most recent Federal Open Market Committee (FOMC) meeting. We provide the supporting documentation for all claims summarized below in the linked articles.
Catherine LeGraw and B.J. Brannan of GMO's Asset Allocation team discussed the role of liquid alternative strategies in today's investment landscape.
According to the latest SPIVA U.S. Scorecard report, broader isn’t always better for active managers. Following a volatile start to the year, the S&P 500 rebounded sharply in the second quarter to gain 10% through June 30 thanks to robust corporate earnings.
Silver has already demonstrated that it can make large moves in both directions, and volatility is likely to remain part of the picture. But after the recent correction, the technical setup is becoming considerably more constructive.
Pacing isn't pausing. Calls to "pace the frontier" mean slowing the release of powerful artificial intelligence (AI) models to test and control them better, not halting development or spending.
Advisors outsourcing at least 20% of assets reported saving 9.1 hours per week, or approximately 473 hours annually. WisdomTree research found 90% of investors welcomed third-party model portfolios, suggesting clients may be more comfortable with outside expertise than advisors expect.
We are never going to get rid of the FOMC for political and practical reasons. For those of us who would like to see the market set rates without an FOMC intervening, this is as good as it’s going to get.
Janus Henderson Investors today announced two senior investment appointments that will further deepen the firm’s leadership across its global equities franchise.
The Federal Reserve raised interest rates this week, in part to reset consumer expectations on inflation. Their work is likely not done, as there is a negative surprise coming for many consumers, especially in rural America. Winter is coming, and that means the return of home heating bills. Depending on how you heat your home, your bills could be much higher this winter.
The Federal Reserve (Fed) made something clear this week that markets had been reluctant to accept. Apparently, the easing cycle isn't paused, it's over for now.
Open any market commentary today and the conversation is dominated by giants. Mega-cap technology companies command outsized shares of major indexes, and the private markets tell a similar story, as we watch companies increasingly staying private well past the point where they once would have gone public.
Artificial intelligence is advancing at a stunning, and perhaps uncontrolled speed. Last week, Evan Hubinger, the Alignment Science Lead at the AI company Anthropic estimated a greater than 10% chance that AI could eliminate humanity within a decade. Jakub Pachocki, Chief Scientist at OpenAI, recently observed 'The core problem in AI research is that of alignment - getting the AI to ‘try to do the right thing’ by human standards…
In an environment marked by the Fed’s first rate hike in three years and ongoing market uncertainty, income-focused investors face a unique dilemma. While cash alternatives offer attractive yields in the short-term horizon, they leave portfolios vulnerable to reinvestment risk should the
As ETF strategies continue to expand into new asset classes and structures, the SEC has been taking a closer look at how some of these products fit within existing regulations.
For decades, equity investors have relied on a foundational promise from Corporate America: the continuous return of surplus cash. Dividends and share repurchases represent the two primary ways by which companies deliver tangible value back to shareholders. Yet as we navigate the final stretch of the third quarter of 2026, both channels are signaling a distinct shift toward restraint.
The new investment case for global power, security and affordability. The phrase “energy transition” has served as a useful political and cultural shorthand, but it has become a misleading framework for capital allocation. Franklin Templeton Institute explodes new opportunities for investors—and where shifts in thinking may be needed.
The U.S. Federal Reserve delivered on consensus expectations by raising its policy rate by 25 basis points (bps) at its September meeting.
One of my favorite movies was the Coen Brothers movie, No Country for Old Men. It is the story of a guy who makes off with $2 million stolen by someone else. The ‘someone else’ is a super mean guy with a powerful blow gun. They are both being chased by a policeman. It was the best picture of 2007 and won four Oscars.
A rising S&P 500® might suggest few opportunities for tax-loss harvesting. But unusually wide dispersion among individual stocks is telling a different story—and potentially creating new opportunities for direct indexing.