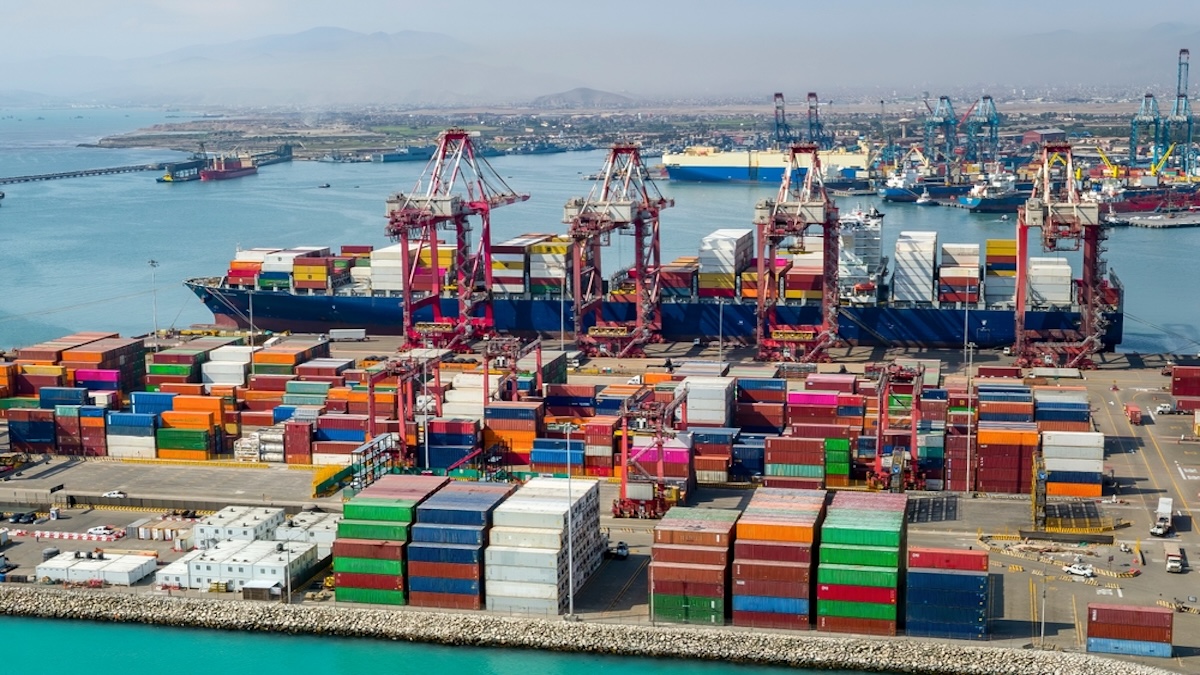
The Middle Eastern waters might be calm enough to allow for energy shipments to recover toward pre-war levels, but Asia-Pacific (APAC) economies are not yet in calm waters. Tight petroleum product supplies and higher shipping costs leave the region vulnerable to further shocks.
The next two weeks bring an unusually crowded lineup of potential market-moving catalysts, including a Federal Reserve (Fed) policy meeting, the busiest stretch of third-quarter 2026 earnings season, the Treasury’s Quarterly Refunding Announcement and the midterm elections.
We have been arguing that the reset higher in yields has restored the dual role of bonds in multi-asset portfolios: providing attractive income while once again offering the potential for meaningful risk mitigation. This month’s tech market turbulence has provided a clear example: As equities came under pressure, U.S. Treasury yields fell amid a flight to safety, allowing duration to behave like a diversifier again.
The bond market is flashing levels not seen in nearly two decades. The 10-year Treasury yield is hovering near 5%, while real yields — measured by Treasury inflation-protected securities (TIPS) — are at their highest since before the 2008 financial crisis.
Last year, U.S. charitable giving hit a record $617.20 billion, according to Giving USA. That’s the first time it’s ever topped $600 billion. Individuals gave $394.2 billion of that, foundations gave $117.15 billion, bequests added $62.19 billion and corporations contributed $43.67 billion.
This marks the first peak week of Q3 earnings season, with 1,885 companies expected to report and overall S&P 500 EPS growth holding at a robust 29.5%
The Fed is hiking to prove it can beat inflation. The danger is that it proves the point with the one economy that can’t afford to lose.
In a world that must fund trillions of dollars of sovereign debt not just in the US but all over the world. Plus, other “normal” business investments which will be even more hundreds of billions, if not trillions. And that brings us to the thrust of today’s letter: who will get access to this money and what are the returns going to be?
In late October, VettaFi hosted an interactive virtual event featuring market leaders from State Street Investment Management, Janus Henderson, and Horizon. During the presentation, advisor sentiment polls revealed a decisive shift in how many are approaching their fixed income allocation. Higher yields have restored bonds as a compelling asset class. However, advisors were looking for tools beyond a traditional index-based bond ETF.
Our Director and Head of Canadian Investment Strategy BeiChen Lin sees two main forces behind this week’s more cautious market tone: higher energy prices and renewed questions around artificial intelligence investment.
With several provisions of the One Big Beautiful Bill Act (OBBBA) taking effect in 2026, year-end planning may present new opportunities and considerations for taxpayers. It’s important to assess personal finances before the end of the year to determine if action is needed.
The S&P 500 has been a reliable index for building exposure to U.S. stocks for years, and for good reason. It’s a valuable barometer for investors who want to make sure they are tracking large-cap U.S. equities.
Manufacturing production began to recover in early 2026 after nearly three years in recession. Yet manufacturing employment has remained largely unchanged. In other words, a year and a half after tariffs were imposed with the goal of boosting manufacturing jobs, that objective remains elusive.
With the U.S. midterm elections mere weeks away, it can be easy to get swept up in the headlines and questions about what different outcomes might mean for markets.
There’s not a lot of bullishness in the silver market right now. After surging to just over $120 per ounce in January, silver corrected and has lost more than half its value.
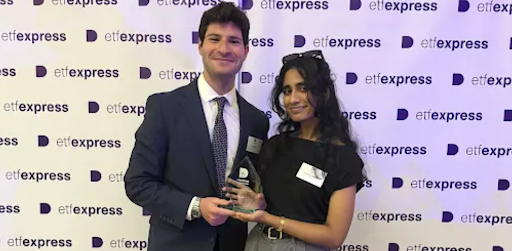
VettaFi has been recognized as the Best U.S. Index Overall Provider at the ETF Express U.S. ETF Awards 2026, building on a standout year of index innovation, strategic acquisitions, and product milestone growth across the ETP landscape.
Emerging markets continued to deliver strong year-to-date returns in 2026, although the third quarter served as a reminder that the path higher is rarely linear. After a powerful first-half rally led by artificial intelligence (AI), semiconductors and other growth-oriented sectors, markets experienced a broad correction in July before stabilizing through the remainder of the quarter.
Stock prices reflect the decisions of buyers and sellers, whose expectations can shift quickly. Enthusiasm, fear, and uncertainty can push a stock above or below a reasonable valuation—and keep it there for an uncomfortable stretch of time.
The number one question we tend to receive is: Where are long-term interest rates headed from here? Right behind it is: How do I invest in the bond market, not only for right now but also for the future? In our opinion, investors should be prepared for this elevated “normal” rate setting for the foreseeable future. We wanted to address both questions by examining how to prepare a bond portfolio for a 5% world.
The Federal Reserve is engaged in a well-documented battle with high inflation. So, many advisors and fixed income investors are evaluating Treasury inflation-protected securities (TIPS) and related ETFs.
A broad retreat in technology shares set the tone for the week. The S&P 500 fell 1.9 per cent and the NASDAQ dropped 4.5 per cent, while the Dow rose 0.7 per cent as investors rotated out of tech and into more defensive sectors.
The Magnificent Seven have dominated the technology trade, but investor attention is now shifting toward the MANGOS — a group of companies that place greater emphasis on artificial intelligence (AI) rather than traditional megacap technology.
For many bond investors, 2026 has stirred up uncomfortable memories of 2022. Yields have climbed sharply as bond prices have come under pressure and the Federal Reserve has raised its policy interest rate target.
Markets look calm on the surface, but AI-driven shifts in capital allocation, earnings quality, and funding needs are reshaping risks and opportunities beneath the index level.
Higher bond yields may offer retirees more income potential, but a diversified approach that balances income, risk, and spending needs remains important.
The Federal Open Market Committee (FOMC), the policy-setting group within the U.S. Federal Reserve, meets on 27–28 October to discuss the economic outlook and appropriate monetary policy. We expect the FOMC to hold the policy rate at 3.75%–4.0% while keeping a clear tightening bias.
Middle Eastern oil exports are approaching pre-war levels, but oil prices certainly aren’t. Brent remains above $100 a barrel, as the concern increasingly is not just how much oil is flowing today, but how much is left in reserve if supplies are disrupted again.
After years when yield was scarce and investors were pushed further out on the risk spectrum, income is investable again. High-quality bonds can once more provide meaningful cash flow, portfolio stability and a credible path to total return without requiring an aggressive call on interest rates or credit.
GMO has posted a new 7-Year asset class forecast for 3Q 2026.
US stocks have continued to climb, but the gains have been far from uniform. In most sectors, a majority of companies have trailed the index. For investors, we believe the divide between a resilient index and uneven stock-level outcomes makes selectivity and fundamental research more important.
Last week saw a further deterioration in the inflation outlook, while the Federal Reserve (Fed) appears increasingly reluctant to tighten again immediately. The September headline Consumer Price Index (CPI) rose 0.6% month/month (m/m) and 3.7% year/year (y/y), while core inflation increased 0.3% m/m and accelerated to 2.6% y/y from 2.4%.
The new policy regime the Fed has lost touch with the economy. It has eradicated a lot of market feedback by eliminating banks from trading federal funds. It has separated interest rates from money supply growth.
As investors look beyond U.S. borders for fixed income diversification, Schwab Asset Management is entering the international bond ETF race with the Schwab International Bond ETF (SCIN). Expected to begin trading on the NYSE on October 21, 2026, SCIN pairs international investment-grade bond exposure with an ultra-low 0.06% net expense ratio.
The ETF industry has officially shattered last year’s record for annual product launches. A total of 1,159 new exchange-traded products have debuted year-to-date, eclipsing the full-year record of 1,143 funds set in 2025. With more than two months remaining in the year, the rapid pace highlights issuers’ relentless push to bring innovative strategies to market.
A week filled with hotter inflation readings brought growing concerns about the sustainability of the pace of AI spending. Despite rising inflation, bond yields ended the week lower. While the S&P 500 Index of large-cap stocks fell 1.95 percent for the week, the decline was largely driven by its heavy weighting to technology stocks, which faltered by 6.37 percent.
While don’t think of myself as being old, I can’t call myself young anymore. When I go to the gym, it takes me longer to stretch than to work out. People my age debate the best vitamin supplements, not the best burger joints. When I am asked for identification at the market, it isn’t to confirm I am old enough to buy beer; it’s to see whether I am eligible for a senior discount.
Predicting the direction of interest rates is challenging enough when economic conditions are relatively stable. Add persistent inflation, a resilient economy, a cooling labor market, geopolitical uncertainty, and an expanding supply of Treasury debt, and the challenge becomes considerably greater.
Earnings now have become the central market focus this week. Bank results have been somewhat mixed, and the market will need confirmation that profits outside the largest technology companies are strengthening. I still do not believe the overall equity market is excessively valued, but investors should expect continued volatility between growth and value as expectations for AI spending shift.
The AI agent catalyst. Meta's September launch of Muse, a personal artificial intelligence (AI) agent designed to act on a user's behalf across digital workflows, crystallized the market's latest disruption narrative.
Fed rate hikes could climb further than markets expect, according to T. Rowe Price Capital Markets Strategist Tim Murray.
The US Treasury market is entering a new era. Financing government debt is becoming less about capital availability and more about the yield required to attract it.
Narratives are almost always wrong: clever stories that explain the past and say nothing about the future. One may be right. AI may become the dominant technology of the century and render much of the present economy obsolete.
This year, the software sector has been one of the worst-performing pockets of the leveraged loan market amid fears that AI would severely disrupt existing business models. The sector’s underperformance has also weighed on the leveraged loan asset class as a whole, given its more than 10% weight in the overall Morningstar LSTA US Leveraged Loan Index.
Chris Galipeau and Taylor Topousis discuss high-conviction insights that go beyond media headlines.
The Nasdaq-VettaFi Asset Allocation Summit this week included insights from leaders at key asset managers discussing the major decisions that advisors are facing. With costs rising and many investors at or near retirement, fixed income and income ETFs, specifically, took up a big part of the conversation. Leaders from BlackRock, WisdomTree, and Fidelity Investments all shared their views on both the fixed income outlook and the use cases for fixed income ETFs right now.
The link between AI capex and earnings carried roughly half of this year’s profit growth, and that support fades once spending stops accelerating, even at a record level. The earnings bill doesn’t arrive when the spending stops. It arrives when the spending stops growing.
Third-quarter earnings season kicked off this week and expectations are high. Despite the headwinds of higher oil prices and interest rates, economic growth has remained resilient, while the AI investment boom continues to gain momentum. As a result, the S&P 500 is expected to deliver 29% year-over-year earnings growth, marking a third consecutive quarter of 25%+ gains.
Plenty of story-stocks and recent alpha generators are outside AI glamor companies. Absolute and relative strength have ticked up in real-economy sectors that were beaten up as investor dollars flowed to tech. Macro conditions, such as ebbing Treasury rates and the upcoming U.S. midterm elections, are wildcards. Still, traders and portfolio managers should listen up for commentary in perhaps unusual places this earnings season.
Artificial intelligence (AI) and the Federal Reserve rate hike have dominated headlines recently—and investors might be wondering how these things will affect them.
Fall is officially underway, heralding a season of change — and what a difference three months makes. The past quarter brought a dramatic Federal Reserve policy pivot and notable shifts in market sentiment and ETF trends. But within equities, the most striking reversal occurred inside the AI trade itself.