The financial industry is being pulled between two powerful forces: bottom-up financial technology is enabling seamless integration, while top-down geoeconomic statecraft is promoting fragmentation. So much for the conventional wisdom that finance will simply become smoother, cheaper, and more globalized over time.
The bond market has become the central story for investors. The remarkable development over the past several weeks is not rising inflation expectations but rising real interest rates. Real rates have increased roughly 40 basis points in just three weeks, one of the sharpest moves I can remember over such a short period. Meanwhile, longer-term inflation expectations have actually edged slightly lower.
Bond markets continue to adjust to a more hawkish policy environment following the Federal Reserve’s recent 25-basis-point rate hike.
Financial markets continue to grapple with a fundamental question: If inflation remains above target after years of restrictive monetary policy, is interest-rate policy still aimed at the right problem?
In this video The Most Powerful Growth Stock, Chuck Carnevale, co-founder of FAST Graphs and known as “Mr. Valuation,” examines NVIDIA through the lens of growth, valuation, financial strength, and long-term return potential. He explains why growth investing is still value investing when a company’s future earnings justify the price being paid.
There is more than one reason the 10-year Treasury yield is 5.23% today. Most importantly, the Fed has stopped anchoring interest rates at artificially low levels. Fear of inflation is likely another. However, both of those are related to the massive government debt the US has created.
I’m writing this week from London, the start of a four-country tour of Europe to see clients. I typically don’t have a lot of free time while on these journeys, but I did sneak away on the weekend for an economics field trip.
AI-related borrowers have accounted for nearly a quarter of nonfinancial U.S. dollar (USD) supply year-to-date, yet spreads for non-AI issuers have not widened meaningfully. Instead, hyperscaler spreads have widened, suggesting the market is absorbing the AI supply shock at its source.
On September 23, Invesco launched the Invesco Nasdaq International Innovators 100 ETF (QQI), a fund that seeks to track the performance of the Nasdaq International Innovators 100 Index.
Retail investors buy corporate bond ETFs expecting steady coupons and ballast against stock market volatility. Traditionally, fixed-income portfolios were anchored by defensive issuers like banks, industrials and utilities.
A recent VettaFi webcast explored advice on navigating retirees' behavioral tendencies in decumulating assets in retirement.
In his latest insight, Richard Bernstein, Global Head of Macro & Customized Investing, examines why the Fed’s actions tend to lag the economic cycle, how deglobalization may limit its flexibility, and what a potentially longer period of tighter monetary policy could mean for investors.
As bond yields have risen, mortgage rates are again facing upward pressure, extending the U.S. housing market's post-pandemic affordability challenges. Beyond mortgage rates, trends in wage growth, taxes, and insurance costs also continue to shape the affordability outlook.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
In the first quarter of this year, as the Strait of Hormuz closed and oil prices exploded, Berkshire Hathaway made a couple of moves that might have flown under people’s radars.It cut its stake in Chevron by roughly a third. Then it bought an airline.
Understanding why investor optimism wins over a full market cycle is one of the most underrated edges an investor can own, and it has almost nothing to do with waving pom-poms.
The financial markets are navigating a storm. The Treasury yield sell-off intensified this week, pushing the 10-year Treasury yield up to an intraday high of 5.20%, its highest level since 2007.
Decided to go independent? Here's how to design your RIA's client model, exit plan, technology, and compliance foundation before you file paperwork or sign a custodian agreement.
I’m talking about the cash I have sitting here that I desperately want to get into the market. Earlier this year, I got a chunk of money from selling a house. I have no desire to own another home (that’s a story for another time.) Instead, I used some of the money to pay off some debt. The rest is just sitting in my savings account earning absolutely nothing.
Before evaluating whether a long-short strategy belongs in a portfolio, we think it helps to understand what's actually happening under the hood. Let's start at the beginning.
A snowball effect of asset values can similarly empower wealth effects: the tendency for consumers to spend more as the value of their investments rises. Wealth effects are surprising at first glance: household investments may be illiquid and tend not to produce substantial cash flow. However, a rising net worth builds a consumer’s confidence in their ability to afford purchases.
The BlackRock Model Portfolio Solutions team made significant allocation shifts during the week ended September 24, 2026. The team recently managed over $300 billion and often causes shockwaves in the ETF industry.
"Funflation" is on the rise, and it could bode quite well for the retail sector if the trend remains persistent.
Northern Trust Asset Management will move six mutual funds with $33 billion in assets into ETFs in early 2027, its first such conversions.
A number has been making the rounds all year, and it’s misleading. The claim: roughly 13% of credit card balances are 90 days or more past due, the worst since 2008. Here’s the twist. That number is real, and it comes straight from the New York Fed.
The U.S. economy remains resilient despite headwinds including sticky inflation, trade instability and rising geopolitical tensions. State and local government tax revenues have followed suit and have posted solid growth, aided by robust equity market returns.
The S&P 500 has remained remarkably resilient in the face of mounting macro headwinds. Despite oil prices topping $100 per barrel, 10-year Treasury yields climbing above 5%, and a renewed shift toward tighter monetary policy, the index continues to hover near record levels.
Second-quarter earnings were strong, particularly in technology, but crowded ownership often determined whether good news was rewarded. The selloff in semiconductors arguably reflected crowded positioning and concerns surrounding the sustainability of the earnings boom. The net result: multiples compressed while earnings revisions held up.
Artificial intelligence (AI) leadership is no longer a developed-market monopoly. Emerging markets (EM) now have their own AI champions, and productivity gains may follow. For bond investors, we expect the implications to differ by country—driven by industry composition, capital intensity, digital infrastructure and speed to adoption.
The Treasury Department will buy back another $6 billion in long-term Treasuries today (Thursday, Sept. 24) as it continues efforts to tamp down rising yields.
The yield on the 30-year hit a multi-decade high this week, spiking amid continued fiscal and monetary concerns. The 30-year hitting 5.45%, its highest mark since 2004, comes amid an already busy year for bonds.
In September 2024 and June 2025, I wrote memos that were critical of governments’ attempts to override the laws of economics, based on my conviction that trying to do so is likely to prove ineffective and potentially harmful.
Asset owners want private-market exposure, but liquidity remains their biggest hurdle, an opening advisors can meet with public alternatives.
This week, there are a few things that we need to pay attention to: the large move in interest rates and what it means (and more importantly, what it doesn’t mean!); and the constant barrage of doom and gloom on energy and AI. Let’s jump in.
I do not know whether quantum computing is in that kind of window right now. Nobody does, and I am suspicious of anyone who claims certainty in either direction. What I can say is that the pattern-matching is uncomfortably familiar.
Creating significant wealth requires concentration of capital, attention, risk, and decision-making.
Last week we looked at the Federal Reserve’s inflation problem. This week, let’s look at the other half of its mandate: maximum employment.
The exchange-traded fund (ETF) market is pacing toward a record-breaking year in 2026, driven by an unprecedented wave of new product launches and historic capital inflows.
Since ChatGPT was first released in 2022, the artificial intelligence (AI) trade has dominated US equity markets. Gains have been driven by three interrelated forces: enthusiasm for artificial intelligence, growing concentration in the largest technology companies and strong price momentum.
This year has presented no shortage of challenges for investors. Geopolitical conflict, trade tensions, rising energy prices, shifting interest rate expectations and an increasingly active political backdrop have each taken turns dominating the headlines. Yet despite these obstacles, the economy has continued to expand, corporate profits have marched higher and markets have climbed one wall of worry after another.
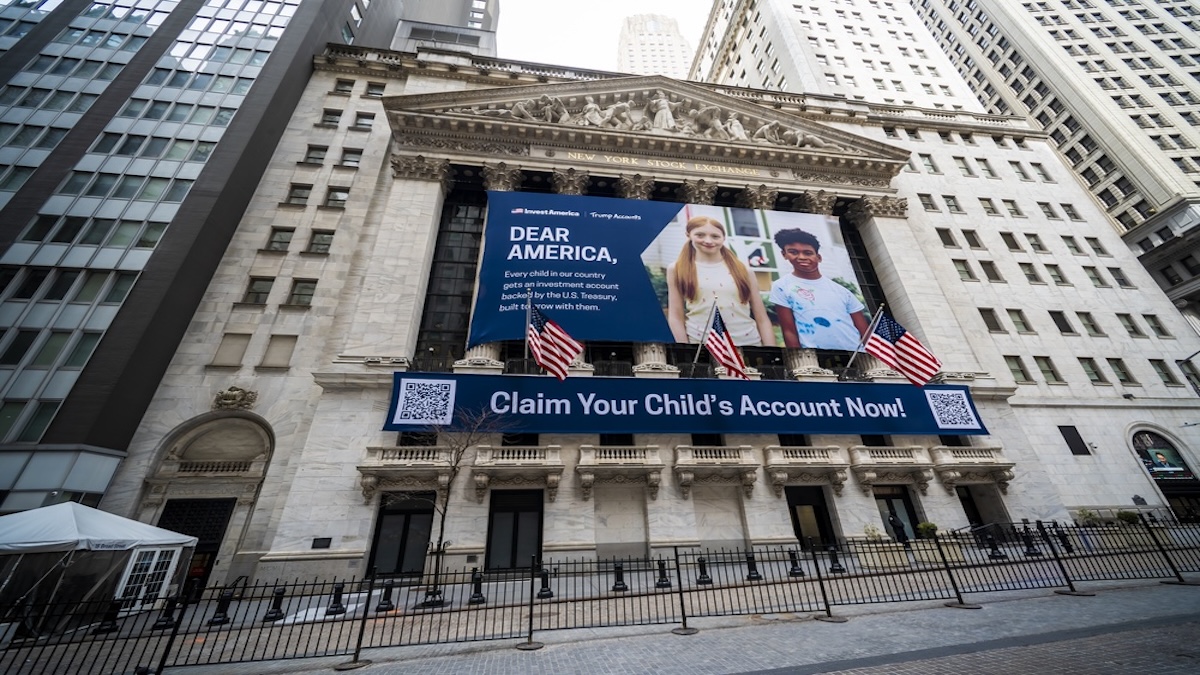
Trump Accounts are now available nationwide. Explore how the new tax-advantaged accounts work, who can contribute and key considerations for families evaluating their long-term savings options.
Confluence Investment Management offers various asset allocation products, which are managed based on “top down,” or macro, analysis. We publish asset allocation thoughts on a bi-weekly basis, updating the report every other Monday, along with an accompanying podcast.
Doshi said gold holding $4,000 during the correction and later rallying to $4,700 before last week's Fed rate hike strengthened his conviction that the broader gold bull market remains intact despite continued headwinds from the Iran war oil shock.
The Federal Reserve hiked rates, and we expect there are more to come. With a hawkish Fed and a resilient economy, long-term yields may stay elevated.
The U.S. economy has traveled farther than most forecasters expected. Strong household spending, healthy labor markets and continued business investment have kept the expansion on course.
The rise in Treasury yields has prompted a familiar set of explanations. Some investors have pointed to government borrowing and persistent inflation, while others have focused on the possibility that artificial intelligence will lift economic growth and interest rates.
Investment bubbles are inherently dangerous beasts. Like a natural Ponzi scheme, an investment bubble needs to draw in ever larger amounts of capital to keep it going. Nothing attracts capital like apparent success, so an inflating bubble that is creating fortunes for those who got in early will inevitably draw in capital. Unfortunately, this means the amount of money lost when the bubble bursts can outstrip the gains created on its way up.
We know from recent history why this question feels so timely. Fixed income remains a foundational portfolio building block, offering low-correlated or uncorrelated diversification and downside risk mitigation. However, holding long-dated bonds in recent years has been notoriously painful.
Looking ahead, markets are priced for additional hikes. And our base case is that the FOMC will likely deliver one or two more 25-bp rate hikes through this year and into early next. However, looking further out, anticipating appropriate Fed policy through a financial-conditions-targeting framework has its own limitations. Hence, a neutral rate anchor is still useful.
The appeal of a portfolio of individual bonds for many investors are the known qualities that they can provide: a known stream of cash flow, a known redemption value, a known redemption date, and a known yield; all of which are locked in at the time of purchase.