In the span of just two weeks, Meta Platforms Inc. has gone from a market afterthought to one of its hottest stocks, as investors finally like what Facebook’s parent is saying about its artificial intelligence plans.
Artificial intelligence is reshaping every business, including ours. But the hardest challenge is not adopting it. It is rewiring your company around it. How corporate leaders respond to that test will determine whether AI shrinks their ambition or raises it.
The median house price in Nantucket, Massachusetts, is nearly $4 million. It was just $500,000 in 1995. This sounds like a stunning increase in one of the hottest and least accessible real estate markets in the country.
The current level of stock market valuations remains – easily – the most speculative extreme in U.S. financial history, beyond both the 1929 and 2000 extremes. Our baseline estimate is that the S&P 500 has a material risk of losing something on the order of 75% over the completion of this cycle.
Investors should consider where in the capital structure they are best compensated for risk. Equity may offer income with upside potential from active asset management, whereas debt may offer income with downside mitigation.
The first half of 2026 reinforced an important lesson for fixed income investors: Tax-loss harvesting opportunities don’t always arrive at year-end, often appearing during short periods of market dislocation when interest rates rise, new-issue supply increases or investor sentiment shifts.
When it comes to space stocks, Elon Musk’s SpaceX (SPCX) is clearly the big kahuna. After all, the company just completed the largest initial public offering (IPO) in history, rapidly joining the $1 trillion-plus market capitalization club in the process. However, the broader space economy extends beyond a single company.
The tech-heavy NASDAQ benefited from a semiconductor rebound and renewed enthusiasm for AI infrastructure names. The Dow, weighted more toward “old economy” stocks than high-growth names, captured none of last week’s gains.
LPL Research examines how sticky inflation, Fed leadership changes, and AI-driven borrowing are shaping the fixed income outlook for 2026.
Historically, many in the pension industry viewed funding above the "plan termination level" as having little incremental value. Once a plan reached “plan termination level”, thought of as roughly 110% funding, conventional wisdom suggested additional surplus had little economic value because it is effectively "trapped capital."
It has been an eventful six months, and we are delighted that the Equity Dislocation Strategy has risen to the occasion. The Strategy generated a 9.05% net return in the first half of 2026, compared with a 1.3% return for MSCI ACWI Value minus MSCI ACWI Growth, a broad proxy for the value-growth spread.
The Fed's recent shift into a more hawkish mode creates concern about banking profits later this year, but second-quarter results are seen strong thanks to IPOs, mergers.
Regardless of how inflation is measured or debated, households continue to feel the cumulative effect of higher prices. The cost of goods and services have risen at a high pace over the past several years, and wage growth has not always kept pace evenly across households.
After a wild last 12 months in a technology stock boom – and more recent volatility – the question du jour, in our view, is not whether AI is transformative.
Every major geopolitical crisis has two types of effects: those that occur during the crisis itself and those that remain on a long-term basis, perhaps even permanently. The US-Iran conflict is no exception.
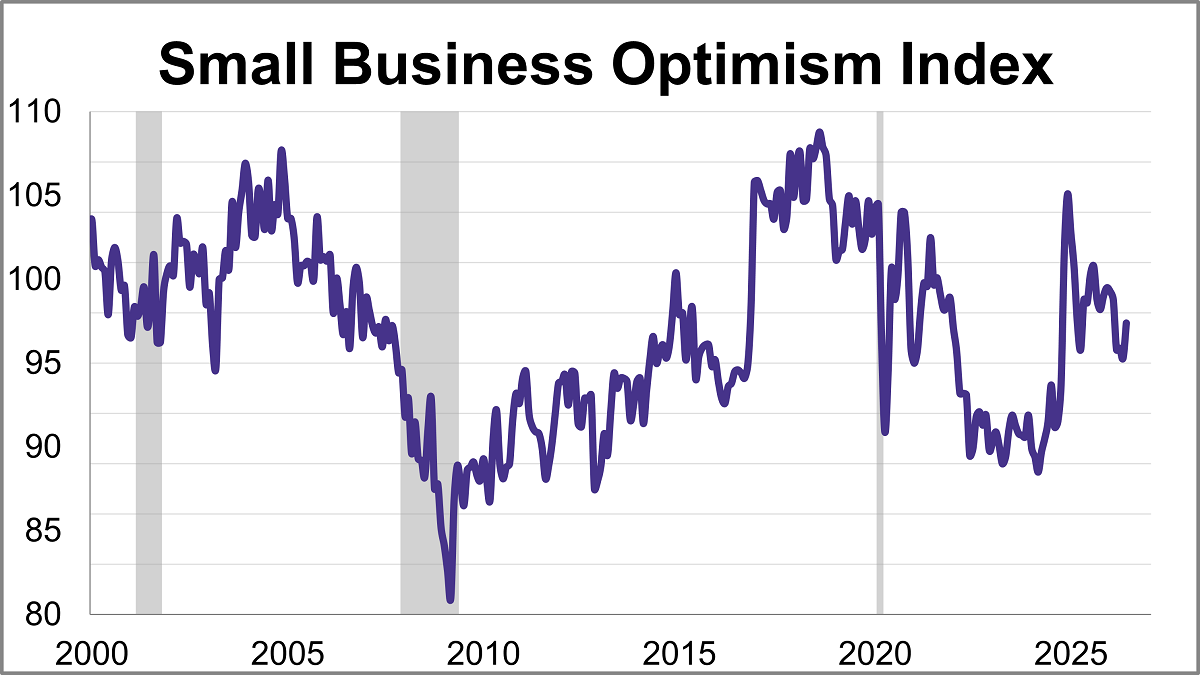
The NFIB Small Business Optimism Index rose 2.1 points to 97.4, reaching its highest level since February. However, the index remains below its historical average for a fourth straight month.
The June release of the Consumer Price Index for Urban Consumers (CPI-U) places the year-over-year inflation rate at 3.53%. This pushes inflation back below the post-WWII average of 3.72% for the first time since March. Meanwhile, this marks the fourth consecutive month that the current rate is above the 10-year moving average, which currently sits at 3.29%.
This series has been updated to include the June release of the consumer price index as the deflator and the monthly employment update. The latest hypothetical real (inflation-adjusted) annual earnings are at $54,560, down 5.7% from over 50 years ago.
Advances in data aggregation, secondary market pricing, and index construction are delivering institutional‑grade insights to a wider audience. Improving access to data and technology helps to build a more transparent bridge that supports confident participation in the growing private markets ecosystem.
Goldman Sachs Group Inc. trounced its own Wall Street stock-trading records, posting $7.42 billion for a quarter that saw indexes rip higher and ongoing market volatility around artificial intelligence and war in the Middle East.
To close the visibility gap, analysis must begin with the “borrower model,” not the fund. Once you know the types of businesses in a portfolio, their industry, revenue band, and geography, you can evaluate them against a statistically robust universe of similarly situated companies.
The US Bureau of Labor Statistics said Tuesday that the Consumer Price Index fell 0.4% in June, bringing the inflation rate over the past 12 months down to 3.5%. That’s good but not good enough. Inflation is still too high.
Over the next 20 years, the industry’s great wealth transfer is expected to put more than $84 trillion in the hands of new family members and other beneficiaries as Baby Boomers increasingly enter their 80s. This large migration of assets could also signal a great client exodus for advisors, if they aren’t able to connect with the new stewards of this wealth.
A client called me last week wanting to know how to claim a $7,500 tax refund he thought he’d missed. His question was based on an email sent in early July to Social Security recipients from Frank J. Bisignano, commissioner of the Social Security Administration.
US stocks rose on Tuesday as investors parsed latest inflation data and Federal Reserve Chairman Kevin Warsh’s remarks.
Shares of software and IT services companies plunged Tuesday after International Business Machines Corp. reported preliminary results that missed analyst expectations, reigniting questions about the sector.
What’s good for the US dollar isn’t always good for US bonds — but investors are finding ways to work around it.
Fixed income investors continue to grapple with an uncertain macro environment, dominated by higher-for-longer interest rates and a new-look U.S. Federal Reserve, in which rate hikes may be forthcoming. Rather than make a directional bet on interest rates to combat duration risk, consider floating-rate ETFs, a compelling option.
Every year in early July, we update our interactive Periodic Table of Commodities Returns to reflect the performance of raw materials in the first six months of the year. Maybe I’m biased, but I believe it’s one of the clearest snapshots of the commodities landscape you’ll find anywhere.
While tariff uncertainty hasn’t completely disappeared, it has diminished, and firms are feeling less uncertain about the future.
Over the past few weeks, data has continued to point to a U.S. labor market that is healing after showing signs of weakness starting in late 2024 and persisting for nearly the entirety of 2025—a condition that spurred the Fed to cut rates even as inflation remained stuck above its 2 percent target.
The first wave of upgrades came after the AI hyperscalers reported, by and large, strong earnings. But most of the improvement has stemmed from the rest of the non-financials index, with analysts quadrupling their one-year aggregate EBITDA (earnings before interest, taxes, depreciation, and amortization) growth expectations, from 5% at the end of January to more than 20% as of 30 June.
If you knew you were standing inside a stock market bubble, you wouldn’t be standing in it for long. You’d sell. So would I, and so would everyone reading this. And if spotting market bubbles was something everyone could do in real time, the bubble couldn’t form in the first place.
Despite renewed geopolitical tensions in the Middle East, markets continue to display remarkable resilience. Major equity averages sit within striking distance of new all-time highs while oil, perhaps the biggest surprise of the year, remains anchored in the low $70s despite renewed hostilities.
As we move toward the mid-term elections, many are making the argument that “democracy is at risk.” We get politicians making this argument, but when supposedly sober political and economic analysts start to make it, we do get worried.
Given how crucial the fixed income sleeve can be to one’s portfolio, the recent concerns over inflation have caused many advisors and investors to rethink how they go about their exposure. This includes debating over active and passive funds, and reevaluating the type of bond duration that is most attractive at this moment.
Morningstar data shows most active strategies lag passive indexes, but selective active fixed income ETFs can generate alpha.
What the heck is going on at Stanford? Theo Baker’s How to Rule the World explains. The book answers the question by centering on Baker’s pursuit at The Stanford Daily of the MTL-associated scientific frauds. And an astonishing journey it is.
Bear flattening trades, inverted yield curves, and frantic style rotations (factor or sector) are not definitive warnings of a market peak. They are extremely informative about where the economy, markets, and investor sentiment stand, but they do not tell investors whether or when the economic or market cycle will turn.
The continued growth of active ETFs reflects a broader shift in portfolio construction across the advisory industry. Advisors increasingly seek investment vehicles that combine flexibility, transparency, scalability, and tax-aware implementation. Dividend growth strategies may align particularly well with the ETF structure because both emphasize long-term investor outcomes and efficient portfolio implementation.
The Federal Reserve’s plans for interest rates in the second half of 2026 appear very much up in the air. That said, advisors and fixed income investors may want to renew their focus on short duration bonds and related ETFs.
In his zeal to avoid signaling where interest rates are headed, Federal Reserve Chairman Kevin Warsh has obscured something else that’s crucial to investors, analysts and other policymakers: How he would react when challenged by the economy.
Investors are flocking back to Apple Inc. as nervousness about artificial intelligence spending weighs on the stocks of chipmakers and cloud-computing giants.
South Korea’s AI-fueled stock rally came under renewed pressure Monday as SK Hynix Inc. tumbled by a record 15%, underscoring growing investor concerns that the boom has become overstretched.
The official data will be released tomorrow, but if past trends continue, the US inflation rate will come in higher than most Americans are used to, but still relatively low.
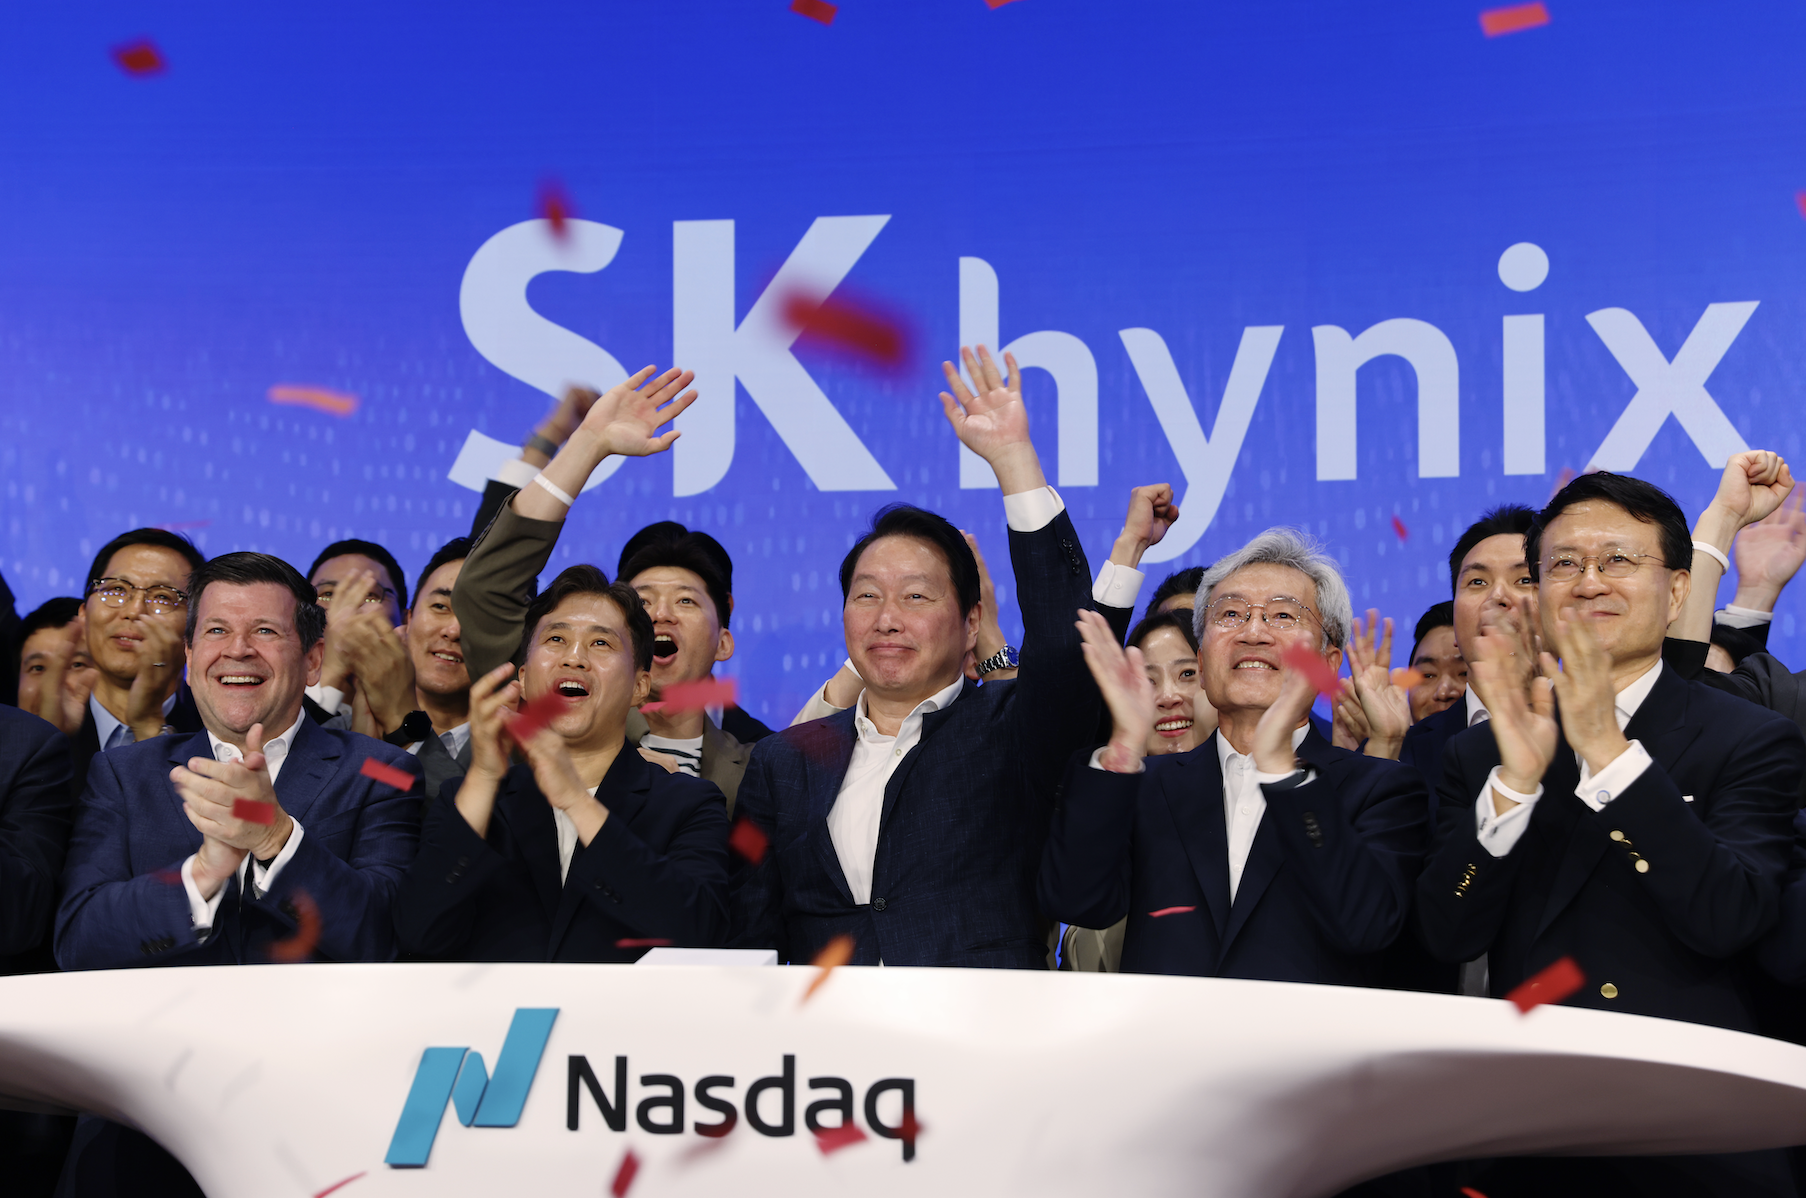
Investors who piled into SK Hynix’s $28 billion blockbuster Nasdaq debut on Friday should be aware: The business model on which the world’s leading memory chip makers are thriving is set to shift to one that requires a bit more strategic and financial gambling.
What makes this earnings setup truly unique is the behavior of Wall Street analysts over the last 90 days. Because corporate guidance tends to be conservative, analysts historically cut estimates ahead of time.
The AI capex risk profile has gotten sharper since then, and the argument needs tightening in a few places. The bull case and the tail risk are now the same buildout, but they are running in different directions.
This week a number of articles caught my attention. The only thing that ties them together is their impact on the US and global economy. Economic anomalies: things we were not looking for but show up and force us to pay attention. Today in the summer heat, let’s take a look at a few of them.
For investors using direct-indexed equity strategies, tax-loss harvesting becomes a major focus, as it may help improve after-tax returns—but we think the calendar for tax-loss selling can make a big difference. Weekly tax-loss harvesting, in our view, offers the potential for more efficient tax-loss harvesting and more effective index tracking in turbulent markets.